


EN
Amazon.com Stock: Is Wall Street Bullish or Bearish?
With a market cap of $2.6 trillion, Amazon.com, Inc. (AMZN) is a global technology and retail company that sells consumer products, digital content, and subscription services through its online platforms and physical stores, while also offering cloud computing through AWS. It serves a wide range of customers including consumers, businesses, developers, and content creators across North America and international markets.
Shares of the Seattle, Washington-based company have underperformed the broader market over the past 52 weeks. The stock has gained nearly 7% over this time frame, while the broader S&P 500 Index ($SPX) has rallied 11.1%. Moreover, shares of the company have risen 3.3% on a YTD basis, compared to SPX's 10.7% gain.
Zooming in further, AMZN stock has outpaced the State Street Consumer Discretionary Select Sector SPDR ETF's (XLY) 1.3% drop over the past 52 weeks.
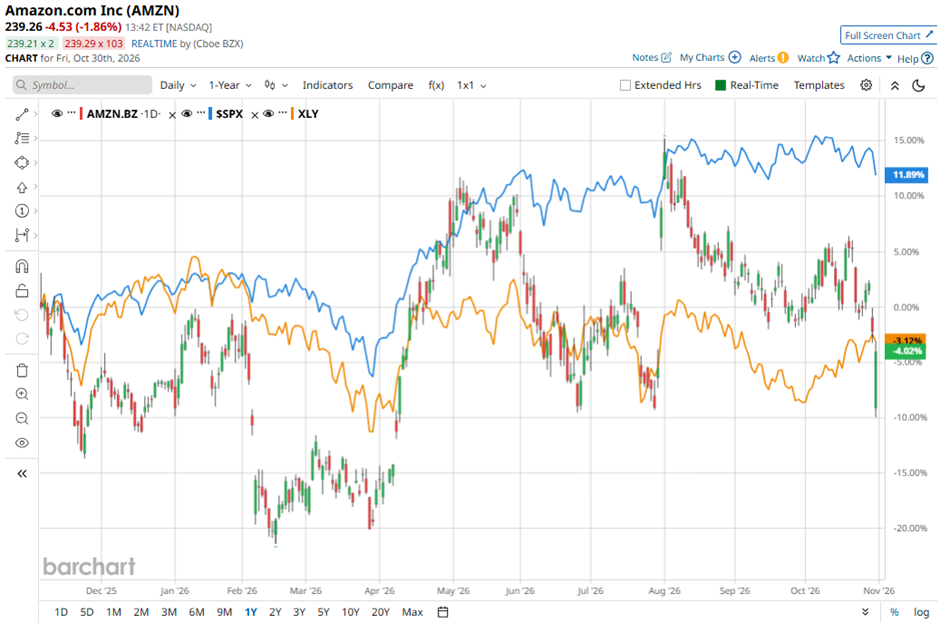
Amazon.com shares fell 2.3% following its Q3 2026 results on Oct. 29, as its aggressive AI infrastructure spending triggered concerns about cash flow, with trailing 12-month cash burn reaching $42.4 billion and capital expenditure hitting $77.26 billion, approximately $20 billion above analysts’ estimates. Investor concerns were compounded by weaker-than-expected Q4 revenue guidance of $240 billion - $247 billion, with the $243.5 billion midpoint below the analyst estimate, while advertising sales rose just 12% to $19.6 billion, missing expectations.
Although AWS revenue surged 39% to $46 billion, its fastest growth in nearly five years, the management warned that 2027 capital expenditure would be meaningfully higher than 2026, when Amazon already expects to spend $220 billion, intensifying worries that AI investments could continue to weigh on free cash flow.
For the fiscal year ending in December 2026, analysts expect AMZN's EPS to grow 11.6% year over year to $8. The company's earnings surprise history is mixed. It has exceeded Wall Street's earnings expectations in one of the past four quarters while missing on three other occasions.
Among the 56 analysts covering the stock, the consensus rating is a “Strong Buy.” That’s based on 47 “Strong Buy” ratings, six “Moderate Buys,” and three “Holds.”
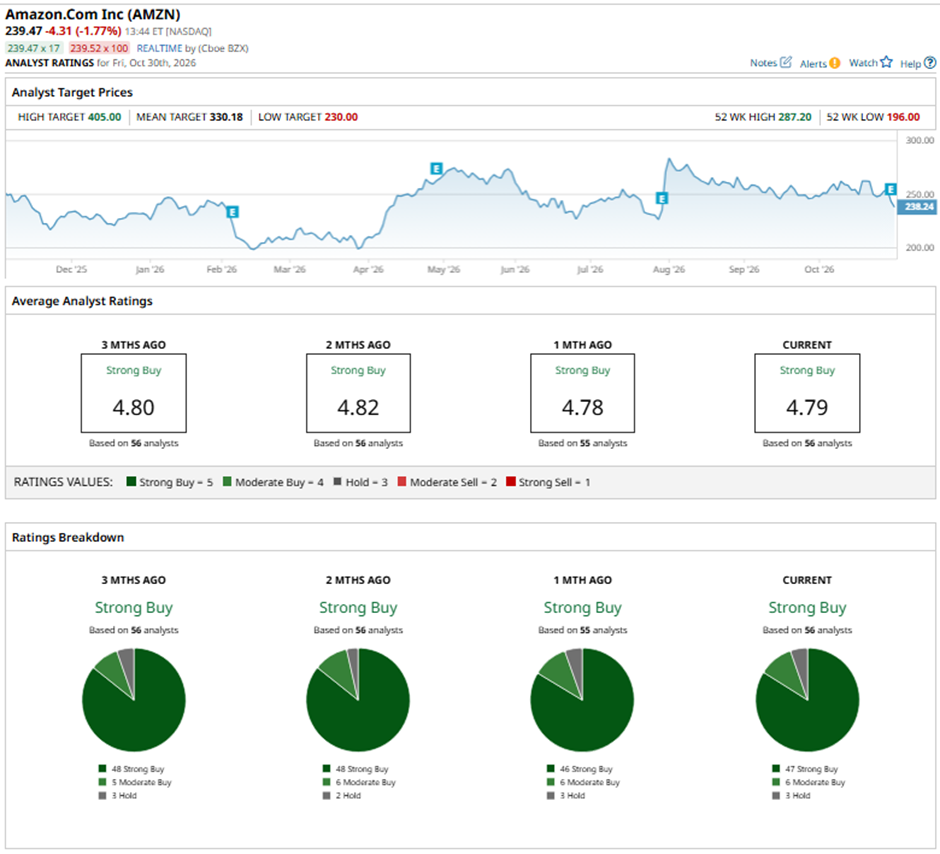
This configuration is slightly less bullish than three months ago, with 48 analysts suggesting a "Strong Buy."
On Oct. 30, Scotiabank cut its price target on Amazon.com to $300 while maintaining an “Outperform” rating.
The mean price target of $330.18 represents a premium of 37.9% to AMZN's current levels. The Street-high price target of $405 implies a potential upside of 69.1% from the current price levels.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.