


EN
Is United Community Banks (UCB) Fully Priced As Third Quarter Loss Meets Higher EPS Guidance?
United Community Banks (UCB) has just paired a third quarter loss with fresh guidance that points to higher earnings per share in the fourth quarter, a mix that gives investors plenty to unpack.
Recent trading shows that United Community Banks has absorbed the third quarter loss and fresh guidance into a mixed price pattern. A 1-day share price return of 1.78% and a 30-day share price return of 10.74% have helped build momentum on an 18.31% year to date share price gain, while a 31.09% 1-year total shareholder return and 75.08% 3-year total shareholder return point to a stronger longer run record than the latest quarter alone might suggest.
Scan how United Community Banks stacks up against other financials showing strong momentum and earnings stories in the carefully filtered 30 high quality undervalued stocks.
The third quarter hit and the guidance rebound are already reflected in the price to a degree. For United Community Banks, after this run, is the bigger swing in value largely spent or only getting started as you now line up the valuation metrics?
Most Popular Narrative: 7% Undervalued
On the most followed view, United Community Banks carries a fair value of about $40.17 against a last close of $37.21. This leaves a modest valuation gap that investors are watching closely as management reallocates capital.
The main thing that has to go right is successful redeployment of Navitas sale proceeds and securities restructuring cash into core loans while maintaining the bank's conservative credit culture and disciplined expense and capital management.
See why 4 investors see United Community Banks as 7% undervalued.
Result: Fair Value of $40.17 (UNDERVALUED)
Still, higher deposit costs and the risk that securities restructuring losses are not fully earned back could both chip away at the upside story for United Community Banks.
Find out about the key risks to this United Community Banks narrative.
Another View: United Community Banks On Earnings Ratios
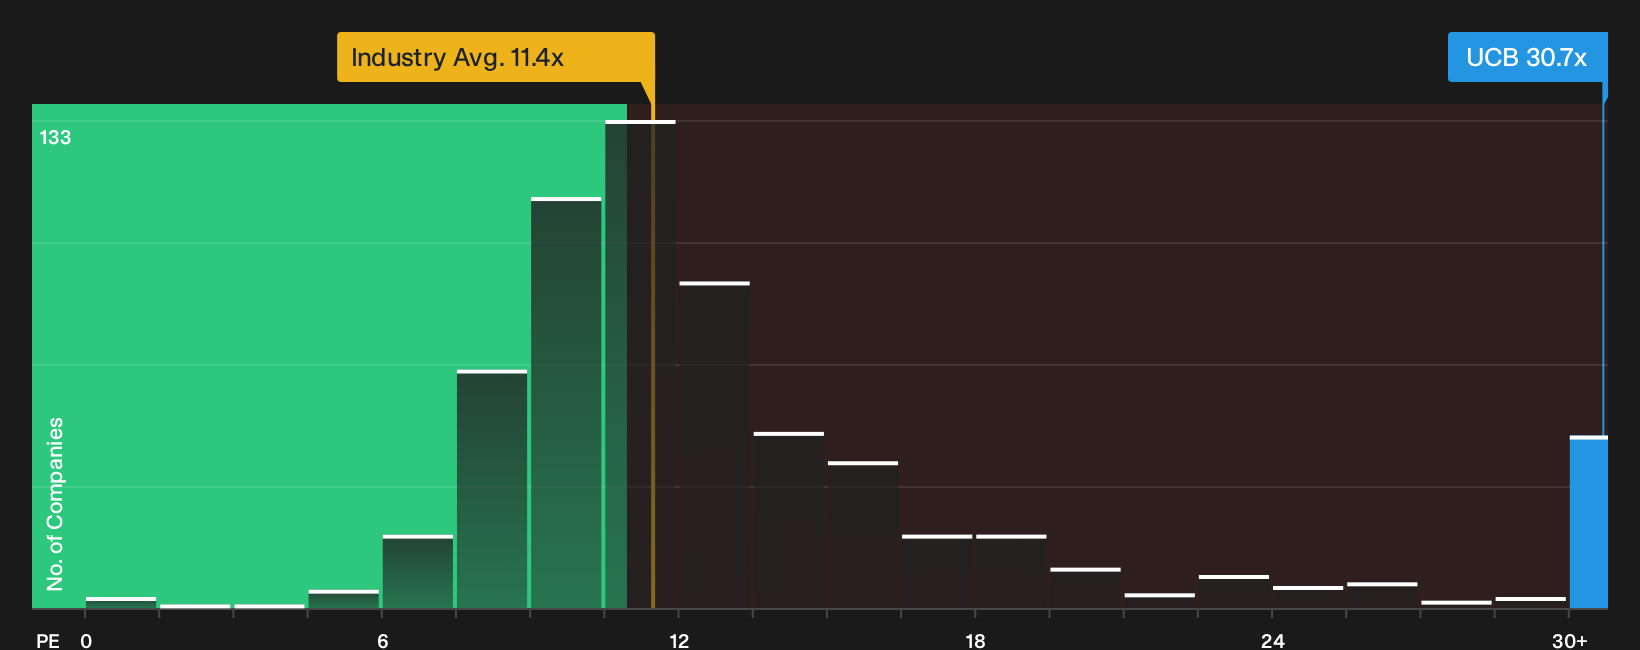
The fair value estimate of $40.17 from the narrative sits beside a very different signal from plain P/E math. United Community Banks trades on a 30.7x P/E, while the US Banks industry sits around 11.4x and the fair ratio points closer to 23.7x. That kind of premium raises a simple question for investors: Is the upside story already heavily priced in?
To see how these valuation gaps fit together with earnings quality, capital levels, and peers, take a closer look at our detailed ratio workup in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on valuation and sentiment can be useful. Move quickly, review the underlying data for United Community Banks, and weigh both the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond United Community Banks?
If you stop with United Community Banks, you miss a wider field of opportunities. Put a few minutes into fresh ideas now and your future self may be grateful.
- Target quality at a discount by scanning companies that combine strong fundamentals with room for potential upside using the 30 high quality undervalued stocks.
- Prioritize resilience and sleep-at-night potential by filtering for businesses with robust finances through the 30 resilient stocks with low risk scores.
- Hunt for under-the-radar potential by checking companies with solid numbers that are flying below most radars in the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com