


EN
What Autotrader Group Investors Missed Before The Fall
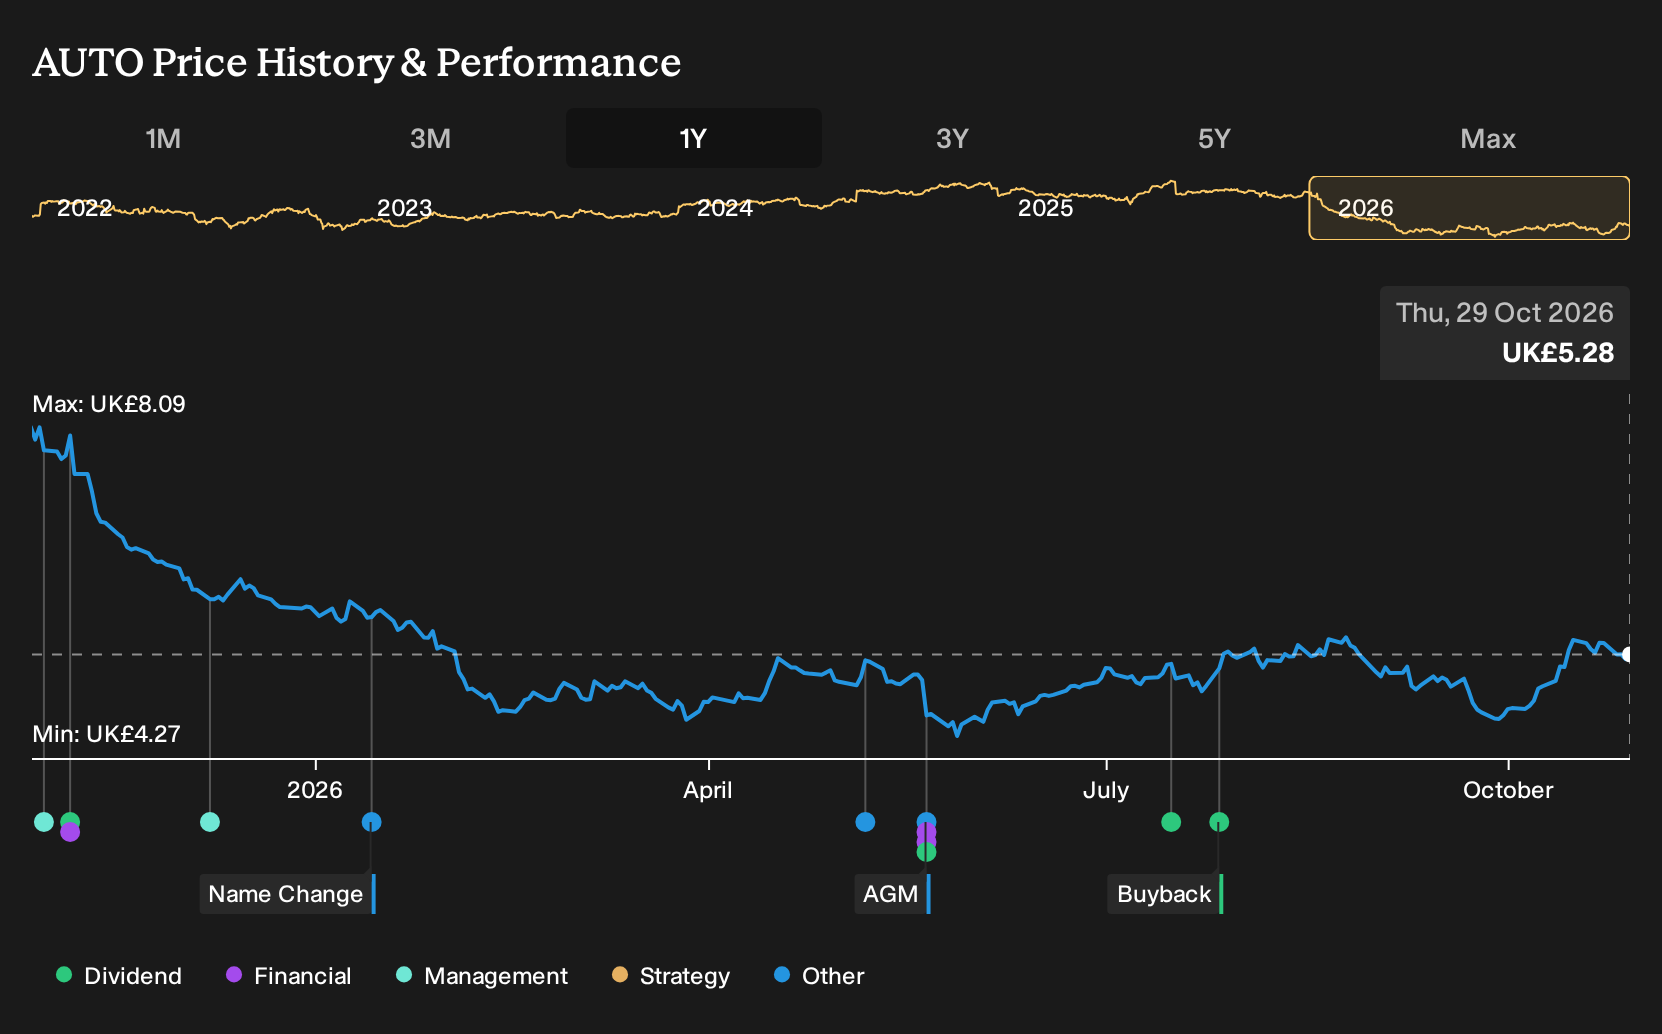
Autotrader Group has spent the past year popping up in market headlines for the right reasons, from leading FTSE 100 gains on strong UK GDP data to riding tech sector strength while banks sagged on tax fears. Investors who held Autotrader Group over the past year are down 33.3%, including dividends. If you had bought before those upbeat sessions, how do those gains and the flat profit in the latest results square with that outcome?
Autotrader Group has already moved. See which of 11 high quality undervalued stocks still trade below our estimates.
The Argument Autotrader Group Investors Were Really Weighing
The shares cost £7.94 at the start of the period, and anyone looking at Autotrader Group then was really deciding which story felt more convincing.
On the upbeat side, the Deal Builder and Co-Driver AI pitch came with a Fair Value of £8.53, a suggested worth above the market based on expectations for 6.3% annual revenue growth and profit margins rising toward 49.0% by about 2028.
The cautious view carried a Fair Value of £6.5, implying pressure instead, built around 5.8% assumed annual revenue growth while warning that shared mobility, tougher urban rules and direct sales models could squeeze the traditional dealership base.
What The Evidence Did To The Autotrader Group Argument
Autotrader Group reported H2 2026 revenue of £306.6m against £298.6m in H2 2025, which helped the upbeat growth story. Net income stayed at £143m and the net margin moved from 47.9% to 46.6%, so the profitability stretch in the bullish case remained unproven. Overall, the evidence cut both ways.
The key assumption here was margin expansion. For any other stock built on a similar story, you would track revenue, absolute profit and the reported net margin each period to see if higher sales are actually turning into richer economics.
What The Fall In Autotrader Group Really Prices In
Autotrader Group now trades at £5.28, with this Narrative arguing that its Fair Value sits above that level based on AI tools and capital returns.
The distinctive pitch centres on Deal Builder and data products turning traffic into higher quality revenue. For the Narrative's higher figure to hold, Deal Builder likely needs to become the default UK used car journey, while retailers stay engaged.
"The shift to Deal Builder as the default used car buying journey, with a target of full retailer penetration in FY27, opens room for Auto Trader to earn incremental fees around finance, reservations and value added services attached to each digital transaction. This would move a greater share of the used car profit pool into high margin marketplace revenue."
One Narrative disagrees with today's price. → See where this Narrative says Autotrader Group should trade
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 17% below our estimate - targets higher demand by aligning new capacity and launches with broader retail reach.
- Company 2 - 31% below our estimate - grows fee income by directing real asset and tax-efficient fund inflows.
- Company 3 - 18% below our estimate - wins experienced lawyers moving from partnerships to a tech-enabled, higher fee share model.
That is three of the list. See all 10 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com