


EN
Alcon (SWX:ALC) Secured FDA Approval For BRYTLY, Is The Upside Already Priced In?
FDA approval for BRYTLY puts Alcon stock in focus
Alcon (SWX:ALC) just secured U.S. FDA approval for its BRYTLY redness reliever eye drops, a new over the counter option that broadens its consumer eye care lineup and draws fresh investor attention.
Recent trading reflects that BRYTLY is landing in a market that is starting to pay attention again. Alcon’s share price is CHF58.76, with a 1 month share price return of 8.01% and a 3 month share price return of 6.10%, yet the year to date share price return is still down 7.52% and the 5 year total shareholder return has declined 23.64%. This suggests that momentum has picked up lately even though the longer record remains under pressure.
Scan how Alcon compares with other healthcare stocks showing fresh momentum by reviewing a curated 200 high quality undervalued stocks that pair resilient balance sheets with stronger cash generation potential.
Alcon now sits in an awkward middle ground. Recent gains and the BRYTLY launch are pulling investors in, while the weaker long term record argues for patience and a better entry. So what does the current valuation actually say?
Most Popular Narrative: 21% Undervalued
Alcon’s most followed narrative pegs fair value at CHF74.71, well above the last close at CHF58.76. This puts the recent BRYTLY optimism in a much wider earnings and cash flow context.
The main requirement is that Alcon continues to shift its mix toward higher value technologies such as advanced technology IOLs, premium contact lenses and premium dry eye treatments, while also executing on cost efficiency programs and new product launches.
The numbers suggest the share price reflects limited credit for this narrative around premiumization, margin expansion and emerging retina therapies, despite recent guidance increases and capital returns.
See why 28 investors see Alcon as 21% undervalued.
Result: Fair Value of CHF74.71 (UNDERVALUED)
Still, if cataract procedure capacity stays tight, or newer premium products such as advanced IOLs fail to scale as expected, the Alcon narrative could quickly look stretched.
Find out about the key risks to this Alcon narrative.
Another View: What Alcon’s P/E Ratio Signals
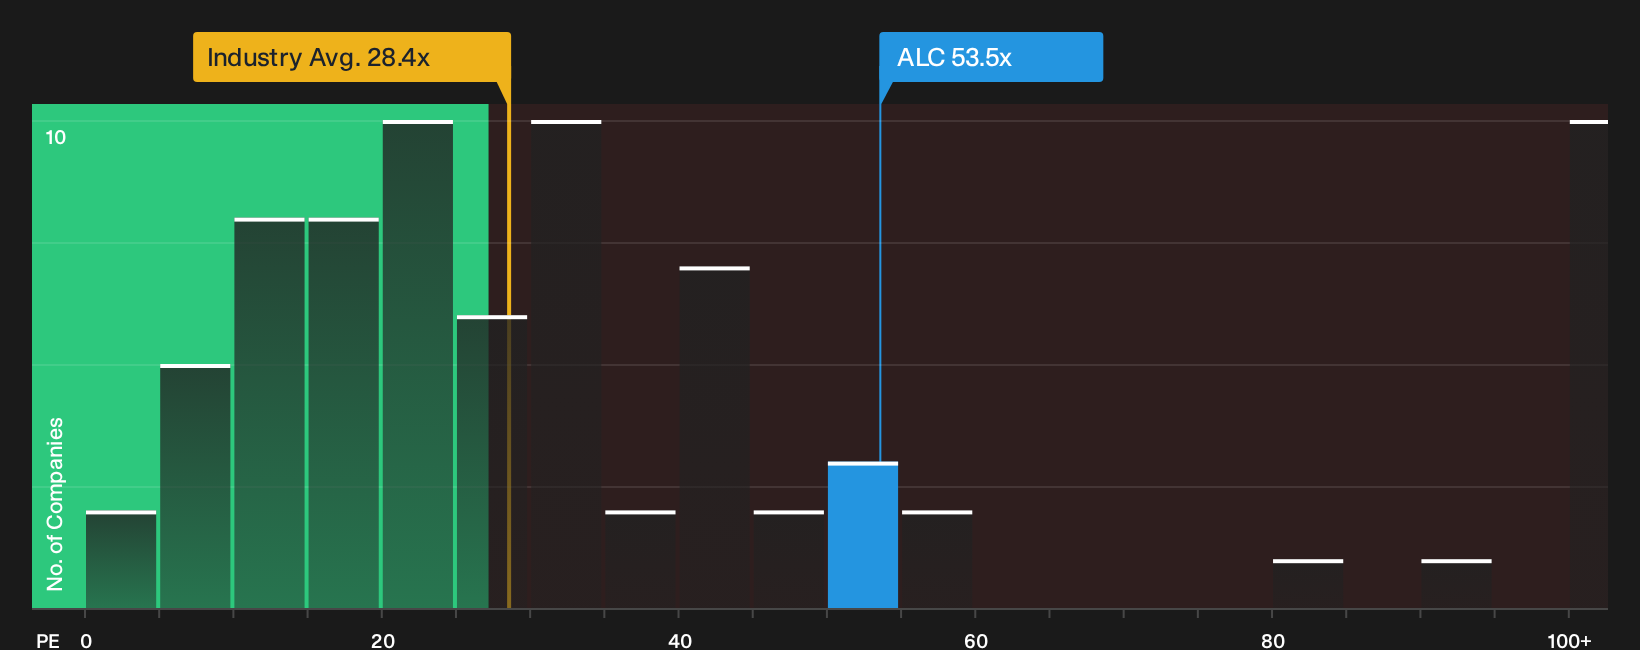
Alcon looks inexpensive compared with the CHF74.71 fair value line, yet the current P/E of 53.5x tells a different story. The stock trades well above the fair ratio of 40.8x and also above both peer averages of 27.7x and 28.8x, which indicates meaningful valuation risk if expectations cool.
For a closer look at how this premium could adjust if sentiment or earnings forecasts change, see the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Alcon’s outlook can be useful if you are prepared to move quickly and work through the data yourself. To weigh both the concerns and the upside case side by side, start by reviewing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Alcon?
You do not need to stop with Alcon. Broaden your watchlist with a few focused stock ideas that bring different strengths to your portfolio thinking.
- Target steady compounding potential by reviewing a 223 dividend fortresses built around income resilience and payout strength.
- Hunt for mispriced quality by scanning a 605 high quality undiscovered gems that highlights under-the-radar businesses with solid fundamentals.
- Protect your downside first by filtering through a 220 resilient stocks with low risk scores that screens for resilient balance sheets and calmer volatility profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com