


EN
Will Tightened Distribution Guidance Change Cheniere Energy Partners Stock Narrative
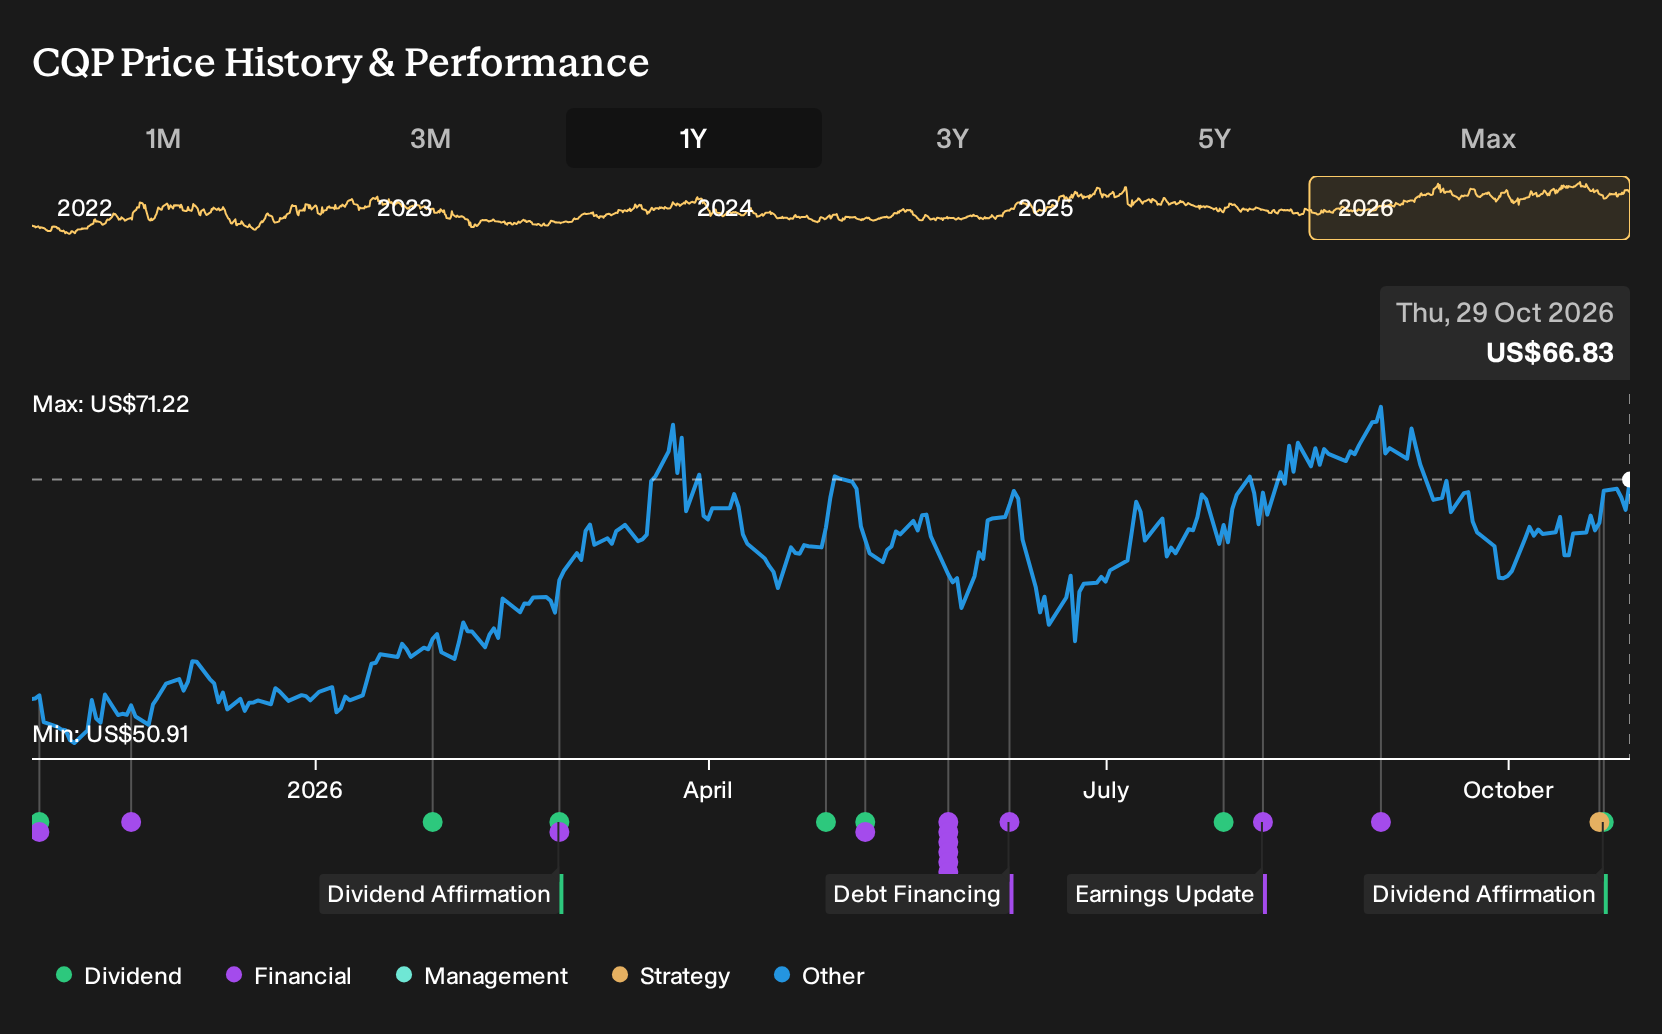
- Cheniere Energy Partners reported third quarter 2026 revenue of US$2,574 million and net income of US$639 million, tightened full year 2026 distribution guidance to a range of US$3.30 to US$3.40 per common unit, and declared a US$0.890 cash distribution, combining base and variable amounts.
- The partnership combined stronger earnings, more focused 2026 distribution guidance, and a long term LNG sale and purchase agreement with QatarEnergy that runs into the 2050s. Together, these developments clarify both current cash generation and contracted future LNG demand.
- We will look at how Cheniere Energy Partners' investment narrative evolves as tighter 2026 distribution guidance reframes expectations for future cash flows.
Scan a curated group of high-yield peers with disciplined payout policies by checking the 7 dividend fortresses alongside Cheniere Energy Partners’ updated 2026 distribution guidance.
What Is Cheniere Energy Partners' Investment Narrative?
To own Cheniere Energy Partners, you have to be comfortable with a capital heavy LNG infrastructure business that depends on long term contracts and disciplined execution at Sabine Pass. The recent quarter put that reality in focus. Management reported US$2,574 million of third quarter revenue and US$639 million of net income, then paired it with tighter 2026 distribution guidance of US$3.30 to US$3.40 per unit and a US$0.890 payout. Those moves point to an emphasis on cash generation and measured distributions rather than rapid expansion at any cost.
The near term story revolves around running the existing liquefaction trains reliably, progressing the Sabine Pass Expansion Project, and managing a high debt load without stretching the balance sheet. The new QatarEnergy contract into the 2050s and the mix of base and variable distributions point to a business leaning on contracted demand and flexible payouts to handle LNG pricing swings, earnings forecasts that call for declining profits, and large ongoing project spending. In the short term, the news looks more material for how investors frame cash flow stability than for changing the fundamental project risk profile.
Even so, there is a single structural issue in Cheniere Energy Partners' setup that could undermine this whole income story if ...
There's only one way to know the right time to buy, sell or hold Cheniere Energy Partners. Head to Simply Wall St's company report for the latest analysis of Cheniere Energy Partners's Fair Value.
Exploring Other Perspectives
Simply Wall St Community members have only submitted two fair value estimates for Cheniere Energy Partners so far, with numbers stretched from about US$2.42 to roughly US$60. That kind of gap shows just how far opinions can spread. Set those views against fresh earnings, tightened 2026 distribution guidance, and the long dated QatarEnergy contract, then decide which camp your own expectations sit closest to.
Explore another Cheniere Energy Partners fair value estimate, including one that suggests as much as 96% downside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cheniere Energy Partners research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cheniere Energy Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cheniere Energy Partners' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cheniere Energy Partners?
Once you have formed a view on Cheniere Energy Partners, it can help to compare that income story with other businesses that share some of the same traits, whether that is resilient balance sheets, higher yields, or potential mispricing. The Simply Wall St Screener lets you quickly line up alternative opportunities that fit those preferences.
- If capital preservation matters most to you, start with companies that screen well for financial resilience through the 30 resilient stocks with low risk scores.
- For investors focused on dependable income, weigh Cheniere Energy Partners against other high-yield candidates in the 7 dividend fortresses.
- If you are hunting for potential mispriced opportunities with stronger fundamentals, broaden your watchlist using the 30 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com