


EN
Dear Tower Semiconductor Stock Fans, Mark Your Calendars for November 2
Over the past year, the artificial intelligence (AI) boom has thrust several semiconductor players into the spotlight, and Israel-based Tower Semiconductor (TSEM) is emerging as one of the companies to watch. A leading and fast-growing contract manufacturer of silicon photonics (SiPho) chips, Tower is capitalizing on surging demand for the technology that enables high-speed optical connections between AI data center servers.
By using light instead of traditional copper cables to transfer data between processors, silicon photonics can significantly improve networking speeds and energy efficiency. As AI adoption accelerates and data centers increasingly prioritize performance and power efficiency, operators are upgrading legacy infrastructure and shifting from copper-based connections to silicon photonics.
And Tower has established itself as a market-leading specialty foundry for these advanced integrated circuits, which are critical to high-speed AI optical transceivers. Adding to the excitement, another major catalyst is just around the corner. Tower Semiconductor is set to release its fiscal 2026 third-quarter earnings before the market opens on Monday, Nov. 2. So, with earnings on the horizon, here's a closer look at Tower Semiconductor stock and what investors should watch.
About Tower Semiconductor Stock
Tower Semiconductor is a leading manufacturer of high-value analog semiconductor chips, providing technology, development, and manufacturing solutions to companies across several industries, including consumer electronics, industrial, automotive, mobile, infrastructure, medical, aerospace, and defense. The company works closely with customers through long-term partnerships, helping them develop chips tailored to their specific requirements.
Tower offers a wide range of customizable semiconductor technologies, including silicon photonics, SiGe, BiCMOS, mixed-signal/CMOS, RF CMOS, CMOS image sensors, non-imaging sensors, display technologies, and integrated power management solutions. It also provides design support to help customers develop chips faster and more accurately. Additionally, its services include developing, transferring, and optimizing manufacturing processes for integrated device manufacturers (IDMs) and fabless semiconductor companies.
To meet customer demand and provide access to additional manufacturing capacity, Tower operates a network of facilities across numerous countries. It owns one 200mm manufacturing facility in Israel and two 200mm facilities in the U.S. In Japan, it operates two facilities (one 200mm and one 300mm). It also shares a 300mm manufacturing facility in Agrate, Italy, with STMicroelectronics (STM).
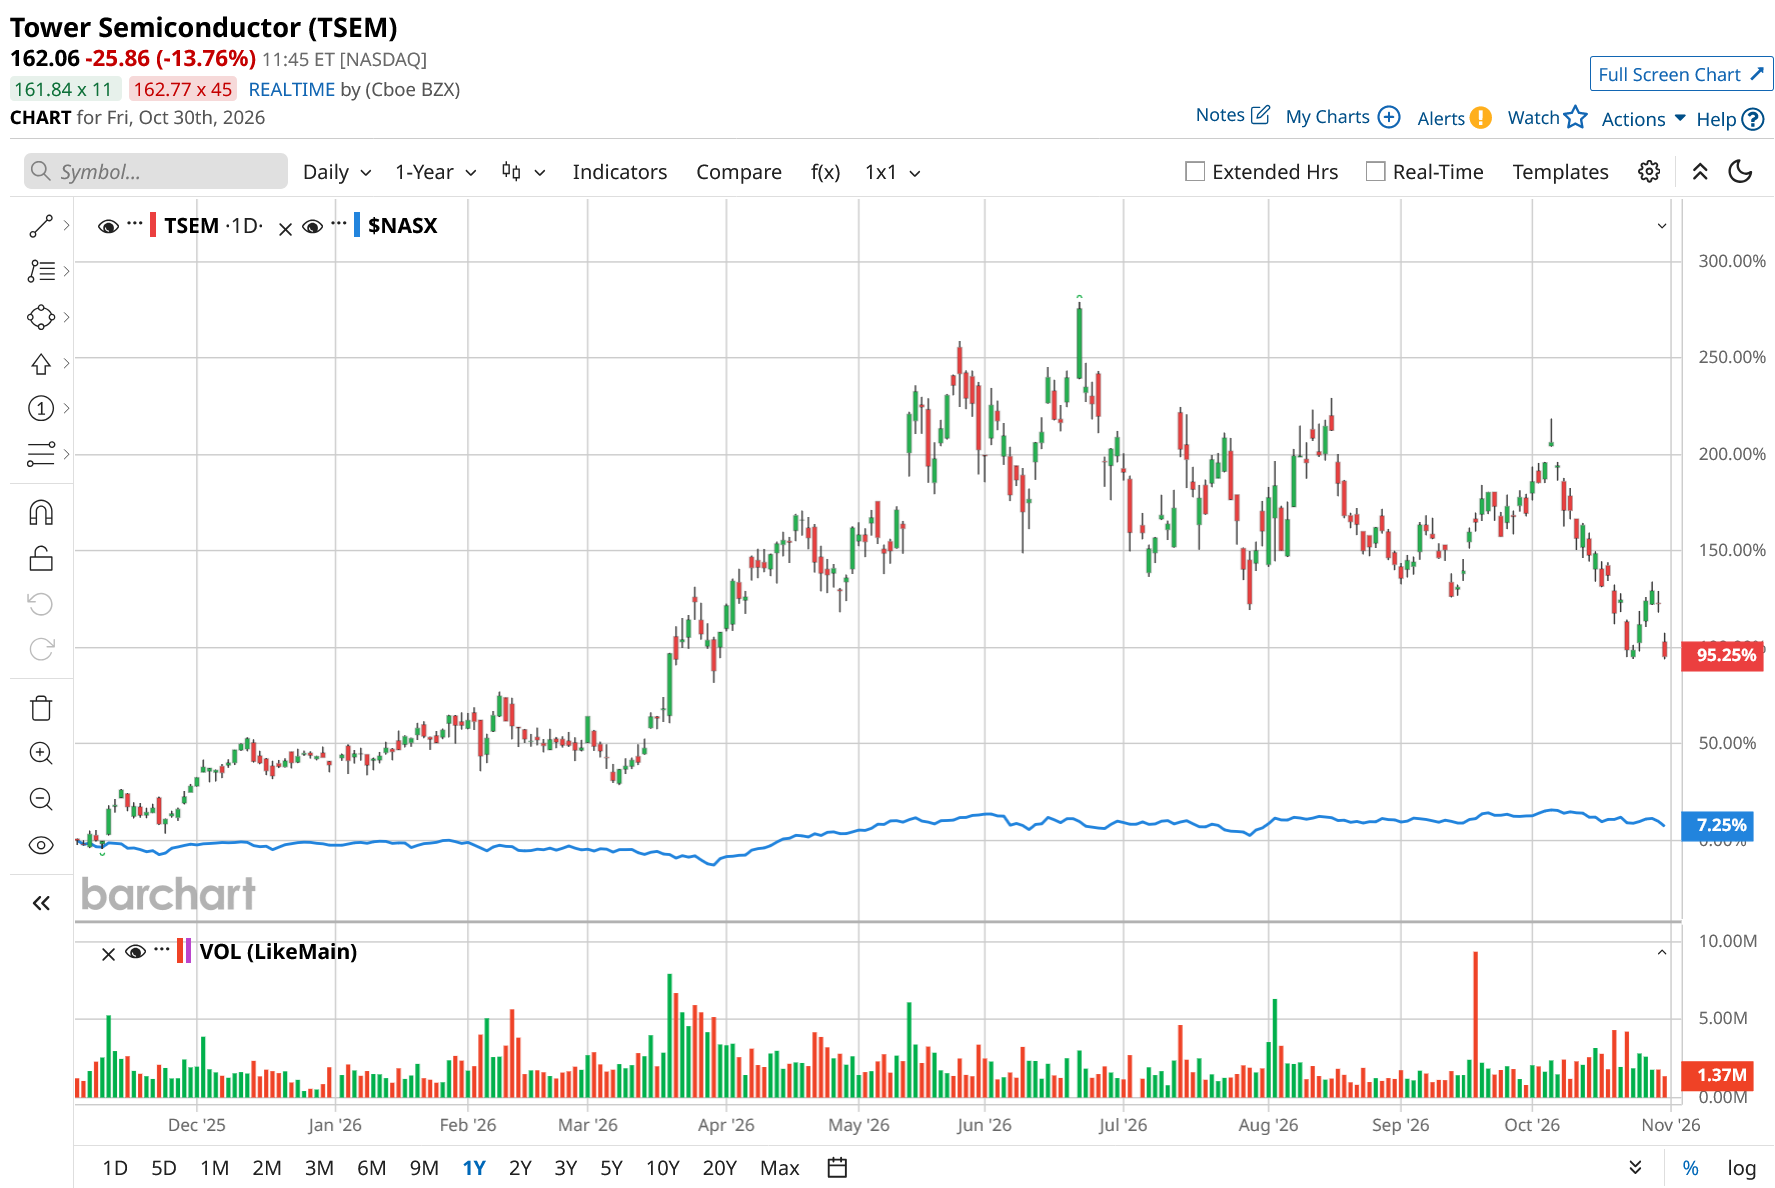
With a market capitalization of approximately $21.33 billion, Tower Semiconductor has emerged as a major beneficiary of the AI-driven semiconductor boom. Investor enthusiasm around its growth opportunities has translated into impressive gains, with the stock surging 97% over the past year, far outpacing the broader S&P 500 Index ($SPX), which advanced just 12% over the same period. Until the recent marketwide selloff of AI names, the rally had shown little signs of slowing in 2026, with Tower shares climbing another 41% year-to-date (YTD), still comfortably outperforming the broader market's 11.3% gain. It is to be seen if the rally finds fresh steam after the dust settles, but Tower's stellar earnings suggest it will.
A Look Inside Tower Semiconductor’s Q2 Earnings Report
Tower Semiconductor delivered a standout second quarter in 2026, combining strong revenue growth with a sharp improvement in profitability and record-breaking financial milestones. The results highlighted the growing contribution of its specialized semiconductor technologies, particularly SiPho, amid rising demand from the AI infrastructure market.
In early August, the company reported record quarterly revenue of approximately $460 million, up 11% sequentially from the previous quarter and 24% year-over-year. The top line also comfortably beat Wall Street's consensus estimate of approximately $454.7 million. However, revenue growth was only part of the story, as Tower also delivered a significant improvement in operating performance.
Gross profit reached a quarterly record of $138 million, soaring 72% from $80 million in the second quarter of 2025. Operating profit, excluding non-recurring items, also hit a record $90 million, more than doubling the $40 million reported in the year-ago quarter.
Profitability reached new heights across the board, with gross margin climbing to 30%, operating margin reaching 20%, and net profit margin also hitting 20%. The improvement reflects stronger manufacturing efficiencies, effective cost management, and a favorable shift toward higher-value specialized products. Net profit jumped nearly 95% year over year to $90.77 million. On an adjusted basis, earnings per share came in at $0.88, up almost 76% from the prior-year quarter and comfortably ahead of analysts' expectations of $0.77.
Tower also generated healthy operating cash flow while continuing to invest heavily in expanding its manufacturing capabilities. Cash flow from operating activities reached $177 million in Q2 2026, compared with $123 million in Q2 2025. Meanwhile, net investments in property and equipment totaled $187 million, up from $111 million in the year-ago period, reflecting the company's continued commitment to expanding capacity and supporting future growth.
One of the biggest highlights was the explosive growth in Tower's SiPho business, which is increasingly benefiting from the expansion of AI data centers. SiPho revenue reached a $680 million annual run rate in Q2 2026, up triple-digit year over year from $180 million in Q2 2025.
Management expects this momentum to continue, targeting a SiPho revenue annual run rate of more than $1 billion by the fourth quarter of 2026, with significant growth expected to carry through 2027. Looking ahead, Tower issued an upbeat revenue outlook for the third quarter of 2026, projecting record revenue of $520 million, plus or minus 5%.
At the midpoint, this guidance implies 31% year-over-year growth and a 13% increase from the second quarter, signaling continued strength in customer demand. Management also raised its 2028 business model targets, now projecting $3.6 billion in revenue and $1.2 billion in net profit. Notably, the company indicated that this projected business is already fully spoken for by customers, underscoring the strong demand and customer commitments supporting its longer-term growth ambitions.
What Do Analysts Think About TSEM Stock?
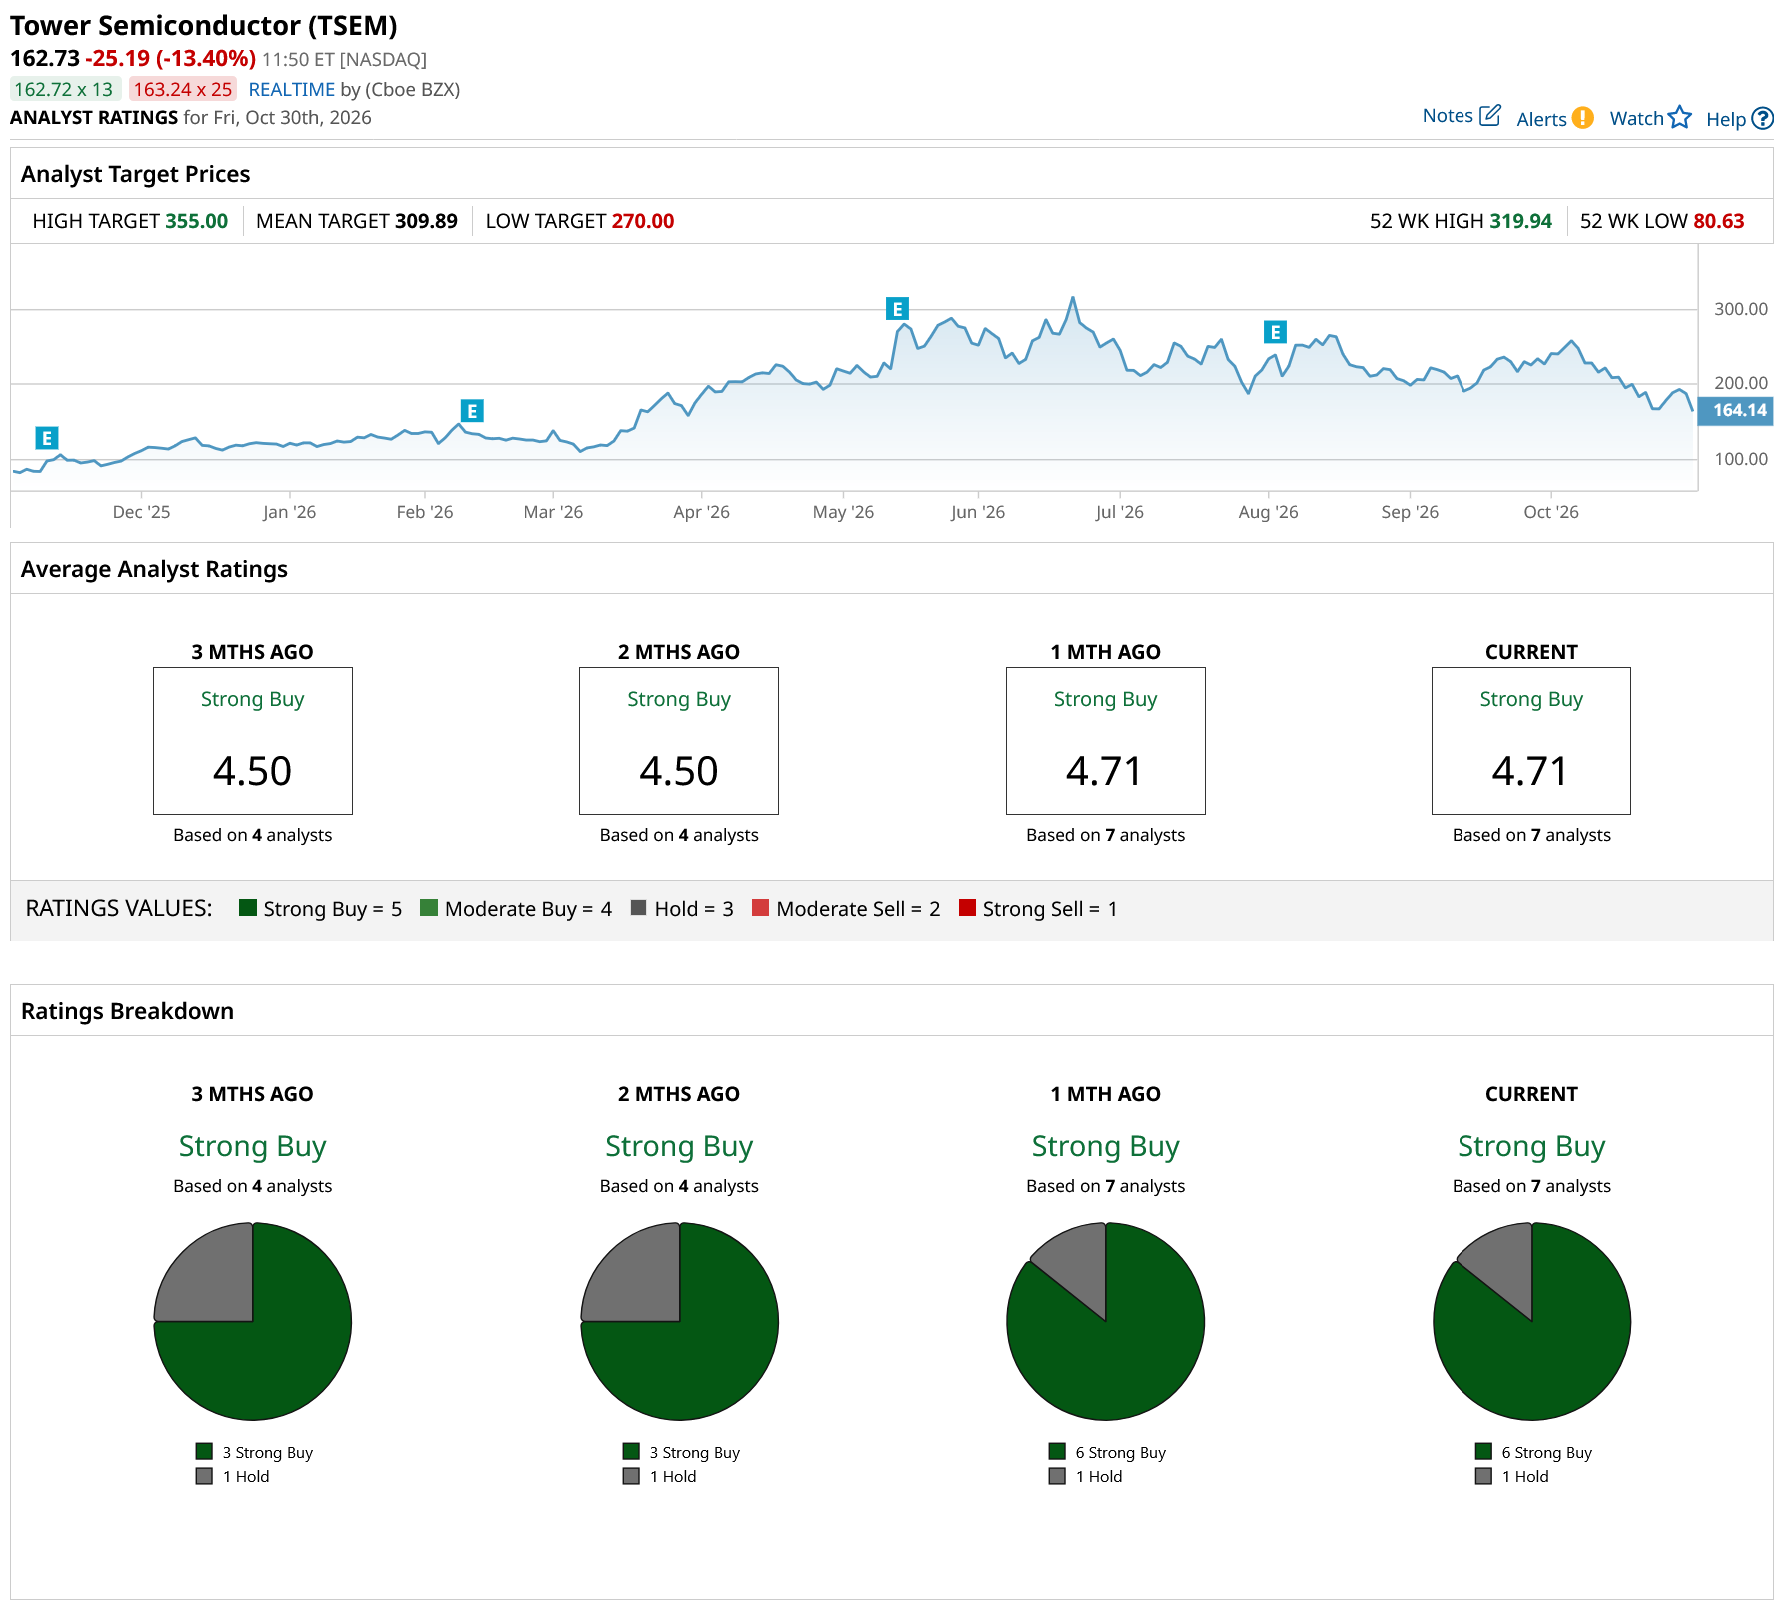
Wall Street is firmly bullish on Tower Semiconductor heading into its upcoming earnings report, with the stock carrying a consensus “Strong Buy” rating. Of the seven analysts covering TSEM stock, six recommend a “Strong Buy,” while just one maintains a “Hold” rating. The optimism is also reflected in analysts’ price targets. The average target of $309.89 points to roughly 90% upside from current levels, while the Street-high target of $355 suggests the stock could climb as much as 118%.
On the date of publication, Anushka Mukherji did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.