


EN
Is Kodiak Gas Services (KGS) Fully Valued Following Margin Pressure And Weak Cash Flow?
Why rising costs and valuation are in focus for Kodiak Gas Services
Recent market commentary around Kodiak Gas Services (KGS) centers on margin pressure, as operating costs outpace revenue growth. This is squeezing EBITDA and leaving free cash flow weak enough to raise fresh questions about the stock’s relatively high P/E multiple.
The share price of Kodiak Gas Services has moved sharply in both directions this year, with a strong year-to-date share price return of 28.08% but a 90-day share price decline of 17.88%. The 3-year total shareholder return of 217.87% shows how long term holders have still fared very well. Recent weakness over the past month and quarter, despite a 9.39% 7-day share price rebound to US$48.21, points to fading short term momentum as investors reassess cost inflation, free cash flow pressure and the stock’s richer P/E multiple against that track record.
Compare Kodiak Gas Services with other contract infrastructure operators facing similar cost pressure by scanning our hand picked list of list of solid balance sheet and fundamentals (23 results)
The swing in Kodiak Gas Services now forces a simple question. Are investors finally reacting to rising costs and thin free cash flow, or has sentiment moved faster than the business justifies as the P/E climbs?
Most Popular Narrative: 39% Undervalued
The most followed narrative puts Kodiak Gas Services’ fair value at $79.50, well above the last close at $48.21. This frames today’s valuation debate squarely around whether its long term infrastructure build out can support that gap.
The current valuation is described as implying that the share price does not fully reflect Kodiak’s plan to grow its compression fleet toward at least 5.2 million horsepower and build a roughly 2 GW power fleet, while funding this with a stronger balance sheet, higher discretionary cash flow, and ongoing dividends and buybacks.
See why 4 investors see Kodiak Gas Services as 39% undervalued.
Result: Fair Value of $79.50 (UNDERVALUED)
Still, if lube oil and other operating costs keep outpacing efficiency gains, or if free cash flow stays weak after heavy power spending, the Kodiak Gas Services undervaluation story could quickly lose traction.
Find out about the key risks to this Kodiak Gas Services narrative.
Another View: Kodiak Gas Services Looks Expensive On Earnings
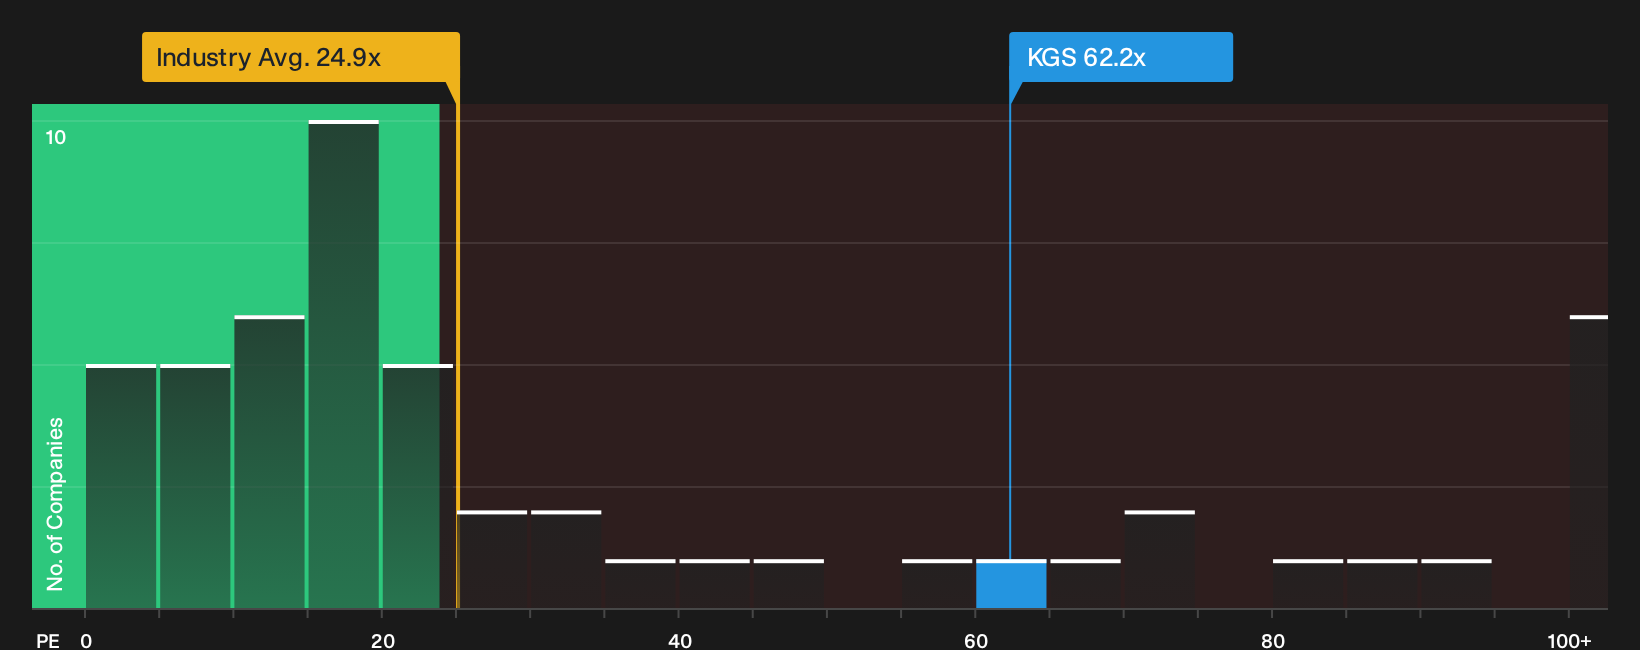
On the flip side of the “39% undervalued” story, Kodiak Gas Services trades on a P/E of 62.2x. That is well above both the US Energy Services industry at 23.5x and the stock’s fair ratio of 26.9x, which points to meaningful valuation risk if sentiment cools.
For investors, the question is whether Kodiak’s future earnings can stretch enough to close that gap before the market decides to pull the multiple closer to the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Kodiak Gas Services is clearly split, which is exactly why it pays to move quickly and review the underlying numbers yourself. To weigh both sides of the debate in one place, start with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Kodiak Gas Services?
If Kodiak Gas Services has you thinking harder about valuation and risk, treat that curiosity as a signal. The next opportunity rarely waits for hesitation.
- Scan for mispriced quality by reviewing our curated 30 high quality undervalued stocks that balance solid fundamentals with the potential for better entry points.
- Prioritise resilience first by checking a 30 resilient stocks with low risk scores that screens for steadier balance sheets and lower overall risk scores.
- Hunt for under-the-radar opportunities through a 18 high quality undiscovered gems built to surface strong fundamentals that the broader market may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com