


EN
How Raised Guidance Will Impact Takeda Pharmaceutical Stock Investors
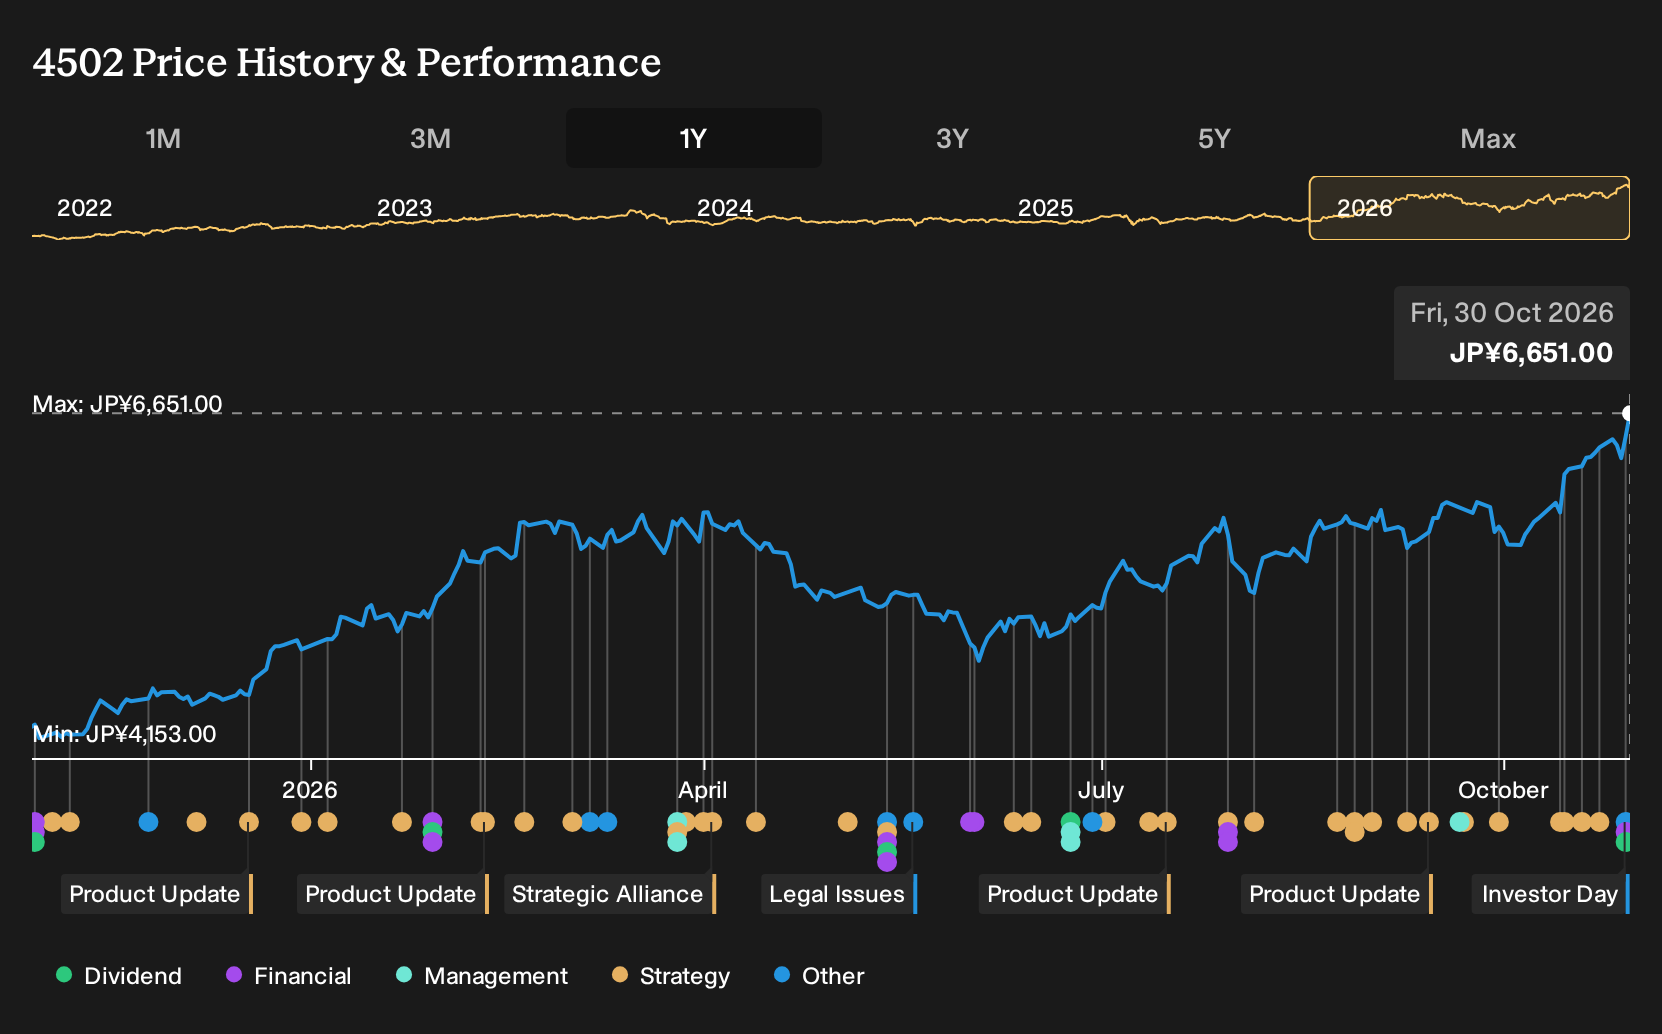
- Takeda Pharmaceutical raised its fiscal 2026 guidance, now targeting JPY 4,700.0b in revenue, JPY 453.0b in operating profit, and JPY 209.0b in net income. The company also lifted second quarter fiscal 2027 dividends to JPY 102.00 per share from JPY 100.00 a year earlier.
- Positive late stage data for arcotatug tavatecan in advanced gastric cancer and new launches such as ORZEYFUL and MIMRYLO highlight Takeda Pharmaceutical’s emphasis on new products and clinical assets, while its transformation program channels cost savings back into the pipeline.
- The focus now turns to how Takeda Pharmaceutical’s upgraded earnings outlook, supported by cost savings, influences the broader investment narrative.
What Is Takeda Pharmaceutical's Investment Narrative?
To own Takeda Pharmaceutical, you have to buy into a simple idea. Management is trying to turn an unprofitable global drug maker into a cleaner, higher margin business built around a focused pipeline and a handful of high value launches. The raised 2026 guidance, cost savings and the dividend lift suggest confidence in near term execution. Products like ORZEYFUL, MIMRYLO, Entyvio and the CLDN18.2 asset arcotatug tavatecan matter most over the next couple of years, because they are the bridge between today’s heavy R&D and the profitability analysts expect.
The flip side is that this is still a capital hungry model. Pipeline bets, large trials and launches demand cash at a time when Takeda Pharmaceutical carries debt that, by third party assessments, is not well covered by operating cash flow and when the 3.07% dividend is flagged as not well covered by earnings. The upgraded outlook and positive trial readouts ease some pressure on the story, but they do not remove the need for cleaner cash generation.
That said, there is a less comfortable piece of the Takeda Pharmaceutical story that sits in plain sight yet …
There's only one way to know the right time to buy, sell or hold Takeda Pharmaceutical. Head to Simply Wall St's company report for the latest analysis of Takeda Pharmaceutical's Fair Value.
Exploring Other Perspectives
One alternate take on Takeda Pharmaceutical leans hard into pricing risk. The most pessimistic analysts were assuming revenue around ¥4,750.4b and earnings of ¥274.4b by 2029, with a rich 38.7x P/E needed to justify their lower target. Those views did not factor in this guidance hike or the latest trial wins, so opinions may shift.
Explore 2 other Takeda Pharmaceutical fair value estimates, including one that suggests it could be worth just ¥6760.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Takeda Pharmaceutical research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Takeda Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Takeda Pharmaceutical's overall financial health at a glance.
Looking For More Investment Ideas Beyond Takeda Pharmaceutical?
If the Takeda Pharmaceutical story has sharpened your thinking about risk, reward and pipeline execution, you can use that same lens across a broader watchlist with the Simply Wall St Screener.
- For investors who want potential mispriced opportunities with solid fundamentals, scan through 14 high quality undervalued stocks and see which businesses might merit a closer look.
- If income and capital protection matter most to you, focus on steady payers in the 28 dividend fortresses that combine yield with a foundation of underlying fundamentals.
- For a steadier ride through market swings, start with the 24 resilient stocks with low risk scores and concentrate on companies that score well on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com