


EN
Profit Warning Might Change The Case For Investing In Yue Yuen Industrial (Holdings) (SEHK:551)
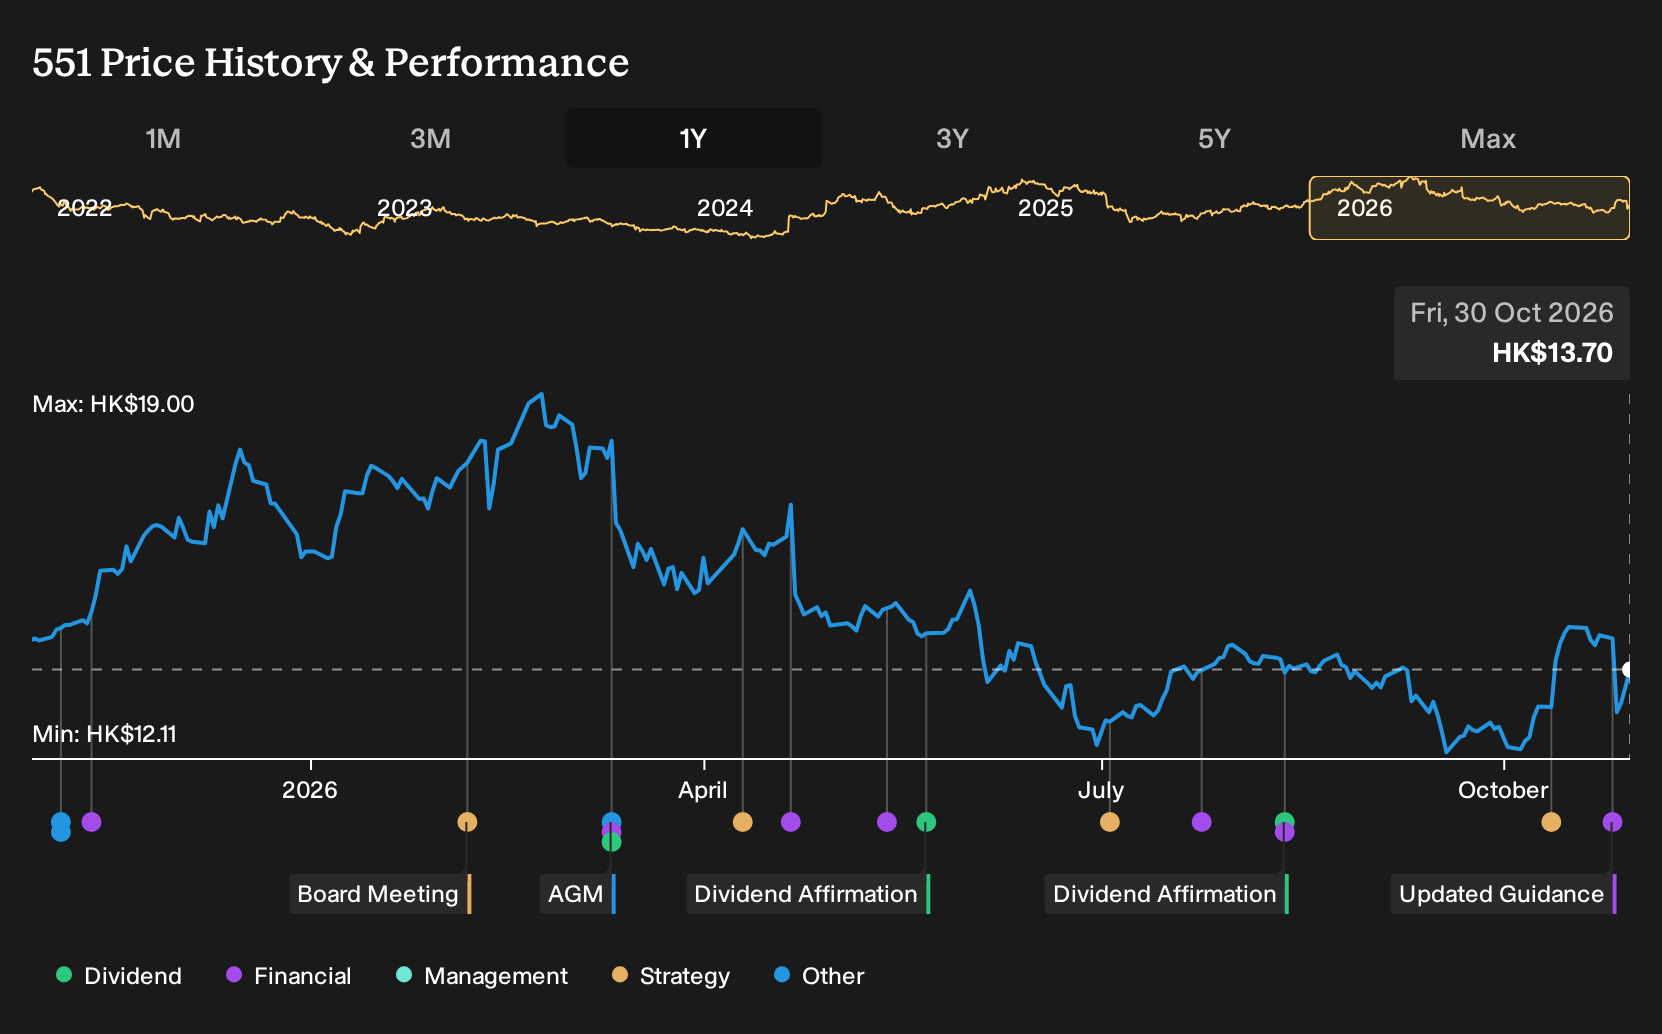
- Yue Yuen Industrial (Holdings) reported that profit attributable to owners for the nine months ended September 30, 2026 is expected to decline by about 50% to 55% from US$278.7 million a year earlier, driven by weaker demand, higher costs and pressure on production efficiency in its manufacturing operations.
- The group linked a 3.8% drop in manufacturing revenue to volatile ordering patterns, conservative inventory stances and tariff sharing, indicating that shorter lead times and cautious brand customers can compress both scale and margins even when order trends improve later in the period.
- This article will examine how Yue Yuen Industrial's investment narrative is affected by profit pressure tied to weaker demand and rising manufacturing costs.
What Is Yue Yuen Industrial (Holdings)'s Investment Narrative?
For Yue Yuen Industrial, the core belief is that a large, diversified footwear manufacturer serving global brands can still be an attractive platform if it can protect margins in a choppy order cycle. The latest guidance, pointing to a 50% to 55% drop in profit attributable to owners for the first nine months of 2026, stresses that short term. Demand volatility, shorter lead times and tariff sharing are hitting scale and pricing, which directly affects the manufacturing segment that generates most of Yue Yuen Industrial's revenue.
Execution around capacity use, cost control and mix becomes the immediate catalyst. The business already runs with relatively low net profit margins of 3.5%, down from 4.6% a year earlier, so every bit of operating deleverage matters. Forecasts still point to earnings growth of 13% per year, but the new guidance tests how quickly that can show up in reported numbers, and whether high quality earnings and a long tenured management team can offset pressure on returns such as a forecast 6.7% Return on Equity in three years.
That said, one issue still hangs over the Yue Yuen Industrial story that many readers might not have fully weighed yet...
There's only one way to know the right time to buy, sell or hold Yue Yuen Industrial (Holdings). Head to Simply Wall St's company report for the latest analysis of Yue Yuen Industrial (Holdings)'s Fair Value.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between HK$12 and about HK$29.54, which is a wide band for the same stock. Those estimates were formed before the October 26 guidance on a 50% to 55% profit drop at Yue Yuen Industrial. You should expect opinions to diverge further and explore multiple viewpoints.
Explore 2 other Yue Yuen Industrial (Holdings) fair value estimates, including one that suggests up to 12% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Yue Yuen Industrial (Holdings) research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Yue Yuen Industrial (Holdings). The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yue Yuen Industrial (Holdings)'s overall financial health at a glance.
Looking For More Investment Ideas Beyond Yue Yuen Industrial?
Yue Yuen Industrial's latest update may prompt you to broaden your watchlist and compare it with other businesses facing different demand, pricing and balance sheet profiles. A quick way to do that is to scan wider markets using focused stock lists that surface traits you care about, whether that is stability, value or income.
- If capital preservation sits high on your checklist, start with a curated group of companies that show resilient fundamentals and lower risk profiles through the 220 resilient stocks with low risk scores.
- For readers who want potential value opportunities backed by stronger balance sheets and cash flows, filter the market using the 200 high quality undervalued stocks and compare those ideas against Yue Yuen Industrial's current setup.
- If reliable portfolio income is a bigger priority, target higher yielding payers that still focus on resilience by scanning the 222 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com