


EN
How Investors Are Reacting To MillerKnoll (MLKN) Permanent CEO Appointment
- On 21 October 2026, MillerKnoll appointed long time insider Jeff Stutz as permanent Chief Executive Officer, formalizing his move from Interim CEO after prior roles as COO and CFO overseeing global operations and finance.
- Stutz’s deep experience across MillerKnoll’s international contract operations, manufacturing footprint, and financial management concentrates commercial, operational, and capital allocation decisions under one leader. This is important for how the business balances cost actions with growth investments.
- The focus now turns to how MillerKnoll’s investment narrative could be reshaped by Jeff Stutz taking the permanent CEO role.
MillerKnoll Investment Narrative Recap
To own MillerKnoll, you need to believe the company can turn its multi segment footprint into steadier earnings and cash generation while dealing with uneven demand in North America Contract and tariff related pressure. The short term swing factor still looks like execution on cost control and footprint rationalization so that existing revenue converts more cleanly to profit.
The biggest near term risk remains a prolonged soft patch in key contract end markets layered on top of tariff headwinds, especially with debt not well covered by operating cash flow. Jeff Stutz taking the permanent CEO role largely reinforces, rather than changes, that operating playbook.
The most relevant update tied to this leadership move is Stutz’s long run in MillerKnoll’s finance and operations seats, from CFO to COO to Interim CEO. That track record matters for investors focused on earnings quality, where MillerKnoll has recently moved back into profitability and carries a valuation that some external analysis views as below estimated fair value.
Leadership that has already overseen international contract operations, Europe based brands and restructuring work sits directly on the key catalysts around Global Retail profitability, tariff mitigation and cost discipline. For a shareholder, the question is whether this continuity improves execution on those existing plans enough to offset tariff, demand and leverage risks already flagged in prior analysis.
MillerKnoll Consensus Targets Underpinning the New CEO Era
MillerKnoll's current projections indicate $4.3 billion in revenue and $180.7 million in earnings by 2029. This corresponds to analyst assumptions of 4.1% yearly revenue growth and an earnings increase of about $82.8 million from $97.9 million today.
Uncover why MillerKnoll's fair value indicates a 55% potential upside to its current price that could narrow quickly.
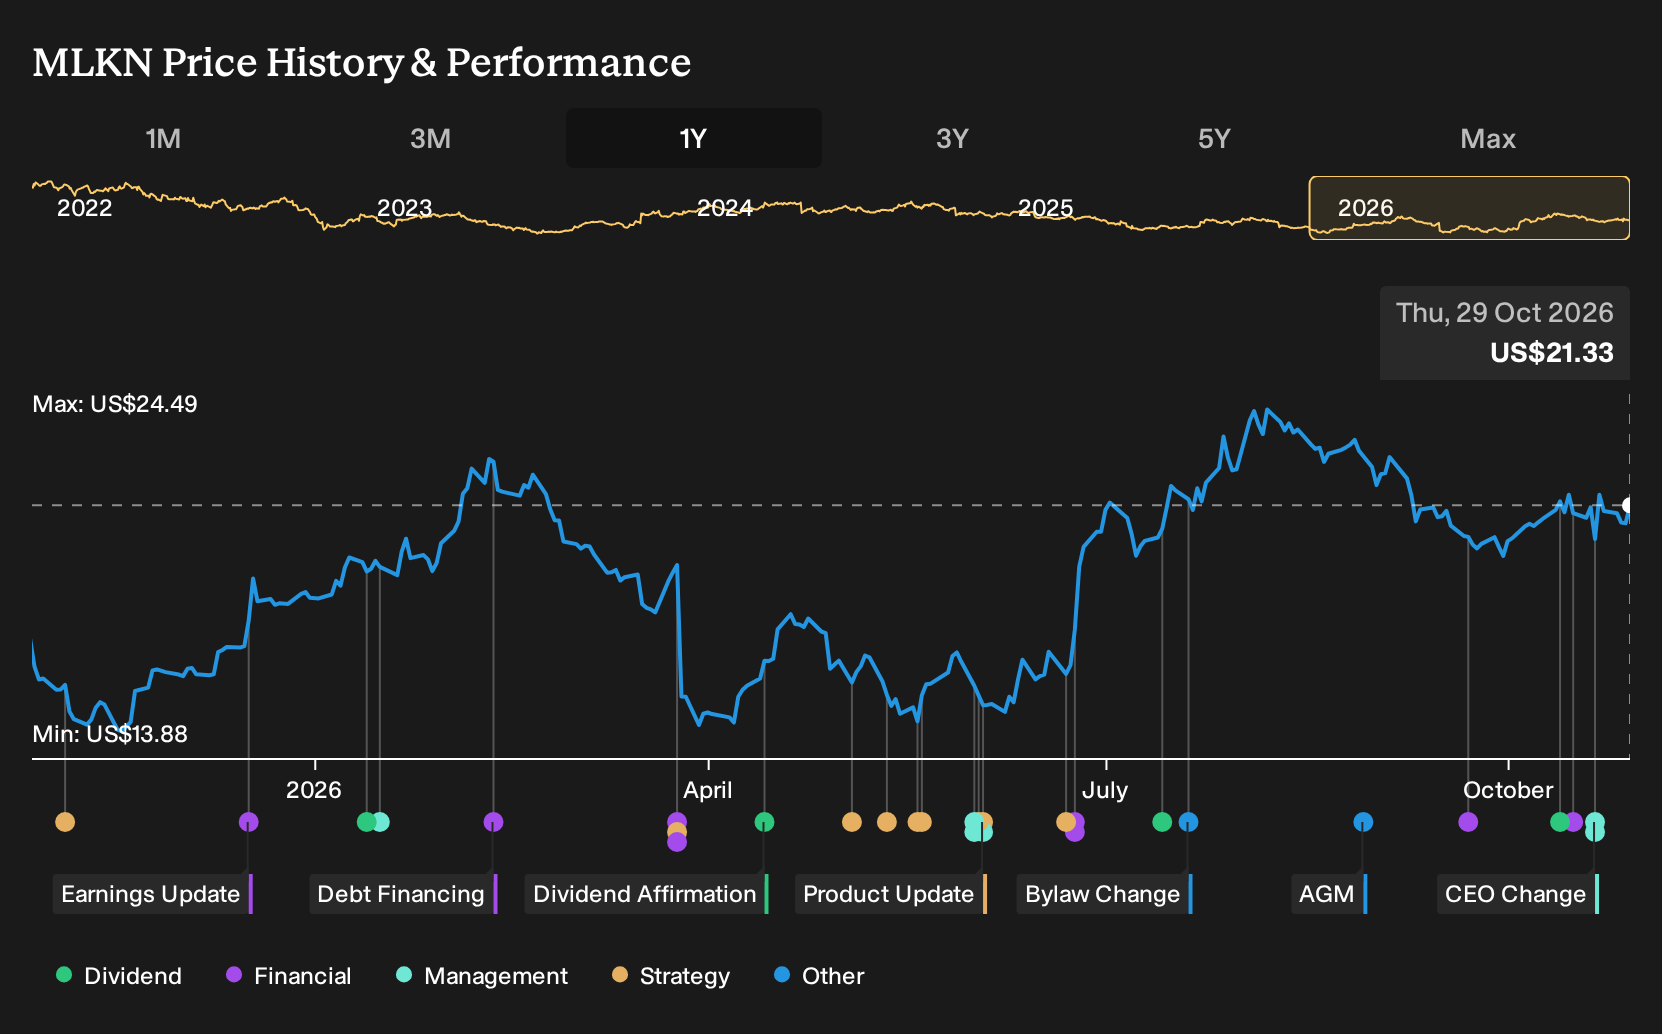
Exploring Other Perspectives
The Simply Wall St Community only includes two fair value views on MillerKnoll so far, with estimates clustered between $27.51 and $33. That tight band still masks real disagreement when you factor tariff risks, softer North American Contract orders, and the new CEO’s execution on cost actions into your own view.
Explore another MillerKnoll fair value estimate, including one that suggests as much as 55% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MillerKnoll research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MillerKnoll. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MillerKnoll's overall financial health at a glance.
Looking for more investment ideas beyond MillerKnoll?
Once you have a handle on MillerKnoll, it can help to widen the lens and compare it with other businesses that fit clear financial themes using the Simply Wall St Screener.
- If you want potential mispricing opportunities, scan through 30 high quality undervalued stocks that combine solid fundamentals with a discount to their estimated worth.
- If resilience matters more to you than excitement, filter for 30 resilient stocks with low risk scores that score well on financial stability and volatility measures.
- If balance sheet strength is your priority, focus on the list of solid balance sheet and fundamentals (23 results) to see companies with cleaner debt profiles and stronger liquidity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com