


EN
Verisk Analytics (VRSK) Expands AI Integrations As Investors Ask If The Stock Is Fully Valued
Verisk Analytics (VRSK) has rolled out new links into Amazon Q, Microsoft Copilot and Claude by Anthropic, giving insurers more ways to pull on its proprietary insurance intelligence inside everyday AI tools.
For context, Verisk Analytics shares trade at US$190.71, with a 30-day share price return of 13.62% after a softer 7-day move that declined 2.64%, while the 1-year total shareholder return is down 11.95%. This points to short-term momentum contrasted with a weaker multiyear record as investors weigh these new AI integrations against existing expectations.
Scan how other AI focused insurers and data platforms are priced today by pulling up our curated list of 54 AI infrastructure stocks as a comparison point to Verisk Analytics.
Verisk Analytics has just delivered a sharp 30-day rebound, while the 1-year and multiyear scorecard still show losses. Is the recent AI-driven enthusiasm a fresh starting line, or mostly a late arrival to the story as valuation comes into focus next?
Most Popular Narrative: 148% Overvalued
Verisk Analytics last closed at $190.71, while the most followed narrative on the stock, according to Esteban, pegs fair value at $76.85. That gap frames the entire debate around whether the recent AI integrations justify the current price or simply add a fresh twist to an already stretched story.
Verisk Analytics is a regulatory-grade data toll on the US property & casualty insurance industry, monetized through ~83% subscription revenue with ~92% client retention. VRSK's narrow-moat franchise produces FCF with an unusually high degree of predictability, durable enough to justify a 15× exit multiple at a 35% margin of safety. The 2022–2025 portfolio simplification (Energy, Argus, 3E, Marketing Solutions all divested) has produced a cleaner pure-play with structurally higher margins (Adj EBITDA 56.2% in 2025 vs. 53.5% in 2023) and a shrinking share count (~19% reduction since 2019). What the investor is paying for here is a regulatory annuity with an embedded MSD price-and-volume escalator, and walking away from any thesis premised on this becoming a HSD-to-DD revenue compounder.
See why 7 investors see Verisk Analytics as 148% overvalued.
Result: Fair Value of $76.85 (OVERVALUED)
Still, Verisk Analytics faces two clear pressure points: any reset in insurance data regulation or slower subscription uptake for new AI links could puncture this overvaluation case.
Find out about the key risks to this Verisk Analytics narrative.
Another View On Verisk Analytics Valuation
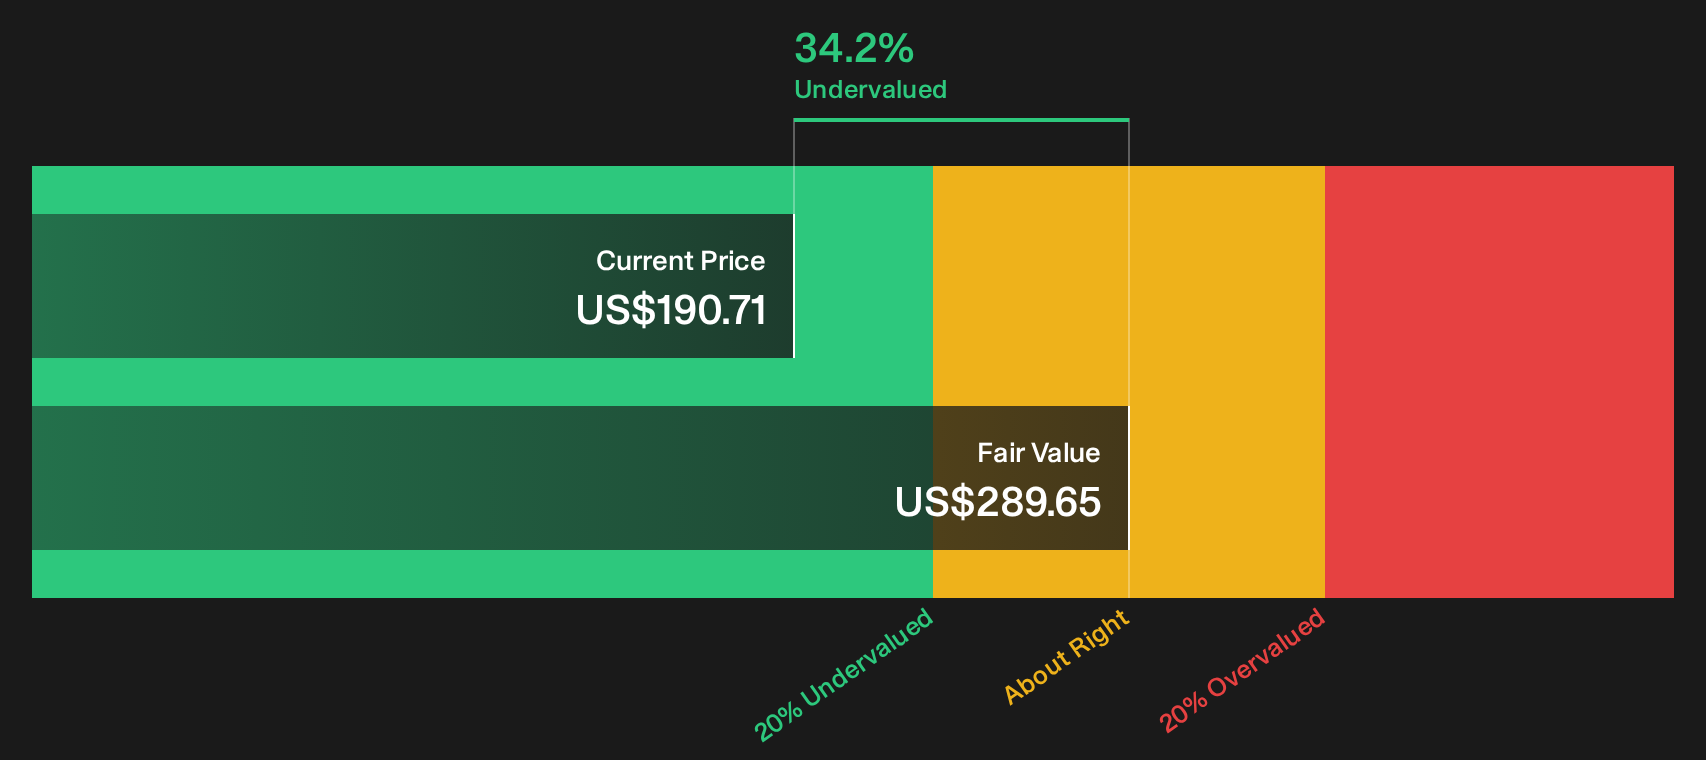
Esteban sees Verisk Analytics as sharply overvalued against a $76.85 fair value, yet our DCF model points in the opposite direction. At $190.71, Verisk Analytics is trading about 34% below an estimated future cash flow value of $289.65, which frames the stock as undervalued instead. Which lens should matter more to you: the cash flows or the narrative premium?
For a closer look at how this cash flow view is built and where the assumptions might feel too cautious or too generous, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Verisk Analytics valuation and AI momentum can feel messy, so move quickly and stress test the story yourself by weighing both upside and downside. To see how that balance looks right now, review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Verisk Analytics?
If Verisk Analytics has you thinking about opportunity and risk, do not stop here. Broaden your watchlist now, before the next move happens without you.
- Target quality at a discount and scan a curated set of 30 high quality undervalued stocks that pair stronger fundamentals with prices that may not fully reflect them yet.
- Strengthen the foundation of your portfolio by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you focus on sturdier financial profiles when conditions turn rough.
- Channel your hunt for underfollowed ideas into a 18 high quality undiscovered gems that spotlights quieter opportunities before they sit on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com