


EN
Carrier Global (CARR) Takes $3.1 Billion Goodwill Hit In Climate Solutions Europe
- Carrier Global (NYSE:CARR) recorded a non cash goodwill impairment charge of US$3.1b tied to its Climate Solutions Europe unit in Q3 2026.
- The impairment is linked to the carrying value of acquired goodwill for the European climate segment on Carrier Global’s balance sheet.
- The non cash charge affects reported earnings for the quarter while not changing the cash position generated by Carrier’s operations.
- The US$3.1b goodwill write down within Climate Solutions Europe alters the way Carrier Global’s risk profile and capital priorities are viewed going forward. Take a look at 3 other big wins we have identified for Carrier Global.
For a broader view on how grid-focused infrastructure plays may respond to the same forces shaping Carrier Global’s outlook, see 43 power grid technology and infrastructure stocks.
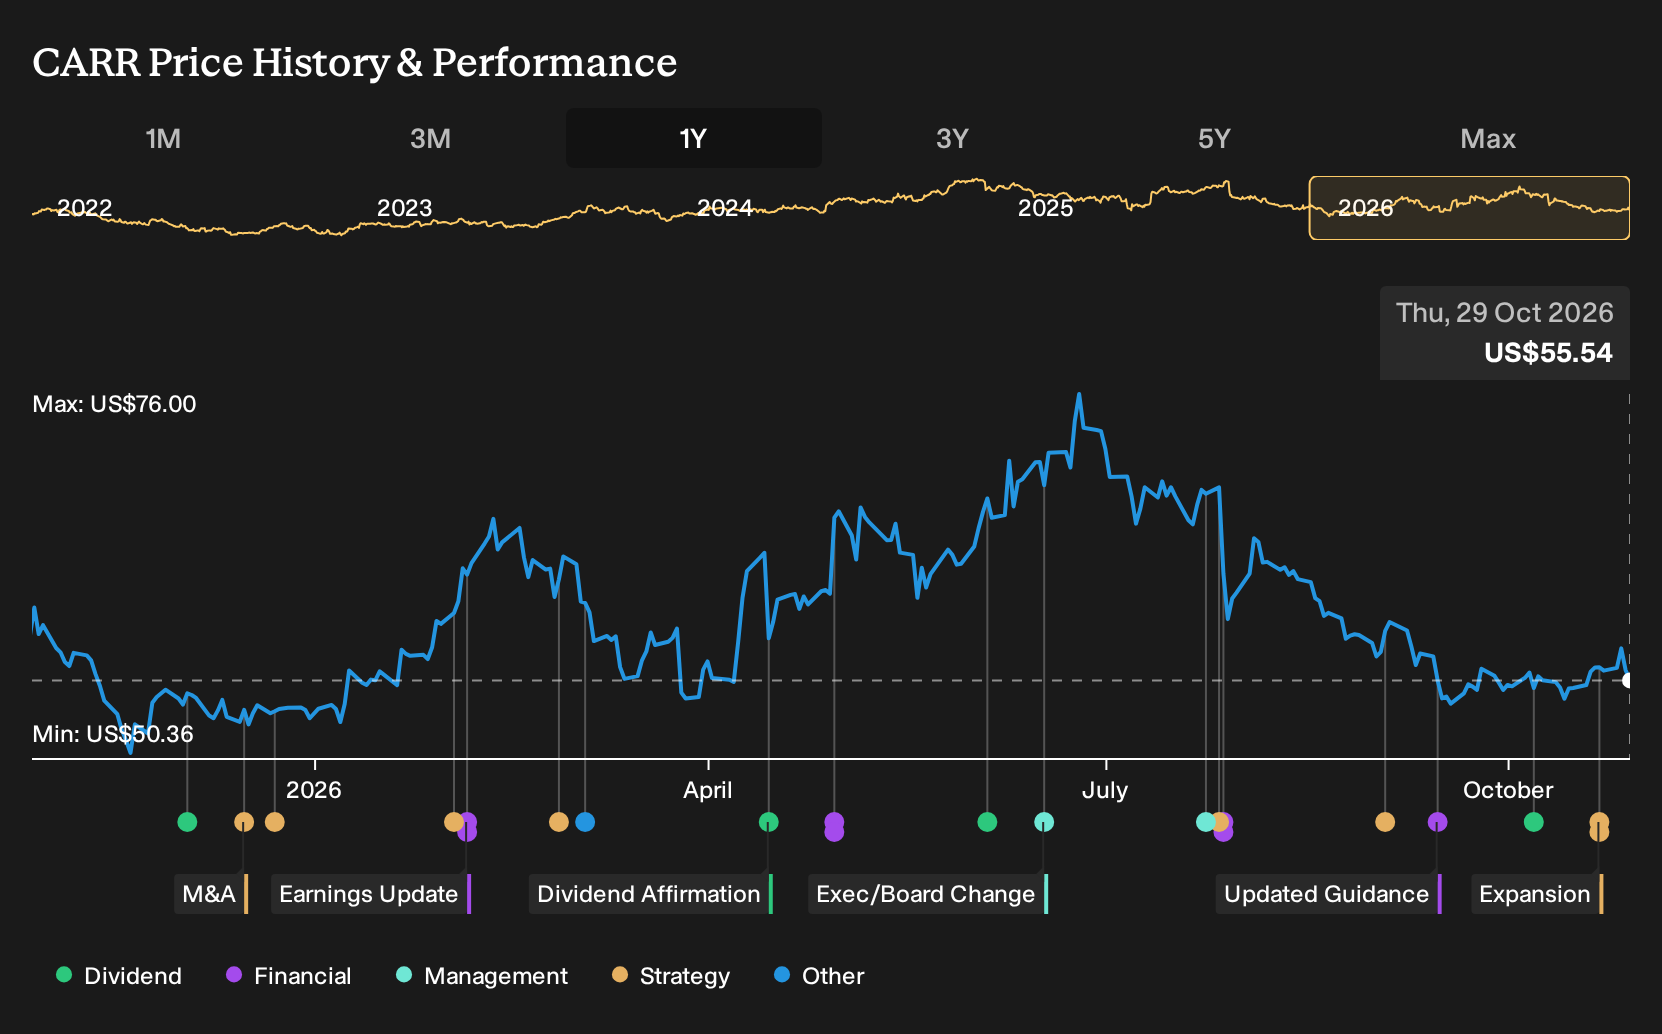
Carrier Global runs heating, cooling, refrigeration and energy management systems across the US, Europe, Asia Pacific and other regions, so an impairment tied to Climate Solutions Europe speaks directly to how investors assess the long term prospects of one of its key geographic pillars.
See which insiders are buying and selling Carrier Global following this latest news.
Impairment puts Carrier Global’s margin story under the microscope
The goodwill write down reinforces that Carrier Global’s European climate operations have not matched earlier expectations, which ties directly to the Narrative focus on lifting margins in that region. At the same time, management raised full year 2026 sales guidance to US$23.8b to US$24.0b and reported higher Q3 revenue than a year earlier, which speaks to the demand and backlog catalysts that underpin the data center and HVAC story. The Q3 net loss of US$2.6b is heavily shaped by the non cash charge, so many investors are likely to focus less on the headline loss and more on whether the margin improvement thesis is simply delayed or structurally weaker.
See how these catalysts shape Carrier Global's path to a $73.44 fair value.
The next real proof point is how adjusted profitability and European climate margins look in the Q4 2026 results and 2027 guidance. If Carrier Global can pair its stronger sales outlook with clearer progress on cost actions in Europe and cash generation, this impairment will matter less as an accounting reset and more as a signal that capital and expectations are being recalibrated to the current reality.
Add Carrier Global to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com