


EN
How Trial Progress At Compass Pathways Stock Has Changed Its Investment Story
- Compass Pathways recently used the 2026 NEI Fall Congress to spotlight its Change the Tune in TRD education campaign and present fresh safety, efficacy and patient demographic data from the COMP360 psilocybin program in treatment resistant depression.
- The focus on large scale classic psychedelic trials and the discussion of regulatory designations for COMP360 gives investors more concrete detail on how Compass Pathways is positioning its lead asset within current clinical practice and future interventional psychiatry infrastructure.
- We will now look at how Compass Pathways' new COMP360 clinical and regulatory visibility could influence its broader investment narrative.
Scan beyond COMPASS Pathways and explore other mental health and biotech stories that could be setting up their next move with our curated 18 high quality undiscovered gems.
COMPASS Pathways Investment Narrative Recap
To own COMPASS Pathways, you need to believe that COMP360 can move from late stage trials into an approved, widely used treatment for tough psychiatric conditions while the firm funds that journey without overwhelming dilution. The NEI Congress update adds helpful color around safety, efficacy and real world deployment in treatment resistant depression, but it does not change that central bet.
The key near term catalyst still sits with successful completion and readout of the Phase III program and progress on a rolling NDA. The biggest risk remains clear. Any trial delay, regulatory pushback or cash burn that runs ahead of funding options could force fresh capital raises and keep the path to profitability distant.
The NEI Fall Congress appearance and the Change the Tune in TRD education push look most relevant for that regulatory and launch pathway. By putting COMP360 data in front of U.S. psychiatrists and framing treatment resistant depression more tightly, COMPASS Pathways is working on the demand side of the story while the trials continue in the background.
For catalysts, the value sits in how this educational work might support physician readiness once Phase III milestones and a possible rolling NDA submission come into view. Stronger clinician familiarity could help COMPASS Pathways convert any future approval into earlier prescription volume. The trade off is that these early commercial efforts lift near term operating expenses while the business still reports no revenue.
COMPASS Pathways' current outlook is based on analyst models that project revenue of $284.9 million and earnings of $53.9 million by 2029. This represents a shift from no revenue and a loss of $192.4 million today to a much smaller profit, implying an earnings swing of about $246.3 million.
Uncover why COMPASS Pathways' fair value indicates a 101% potential upside to its current price, which could narrow quickly.
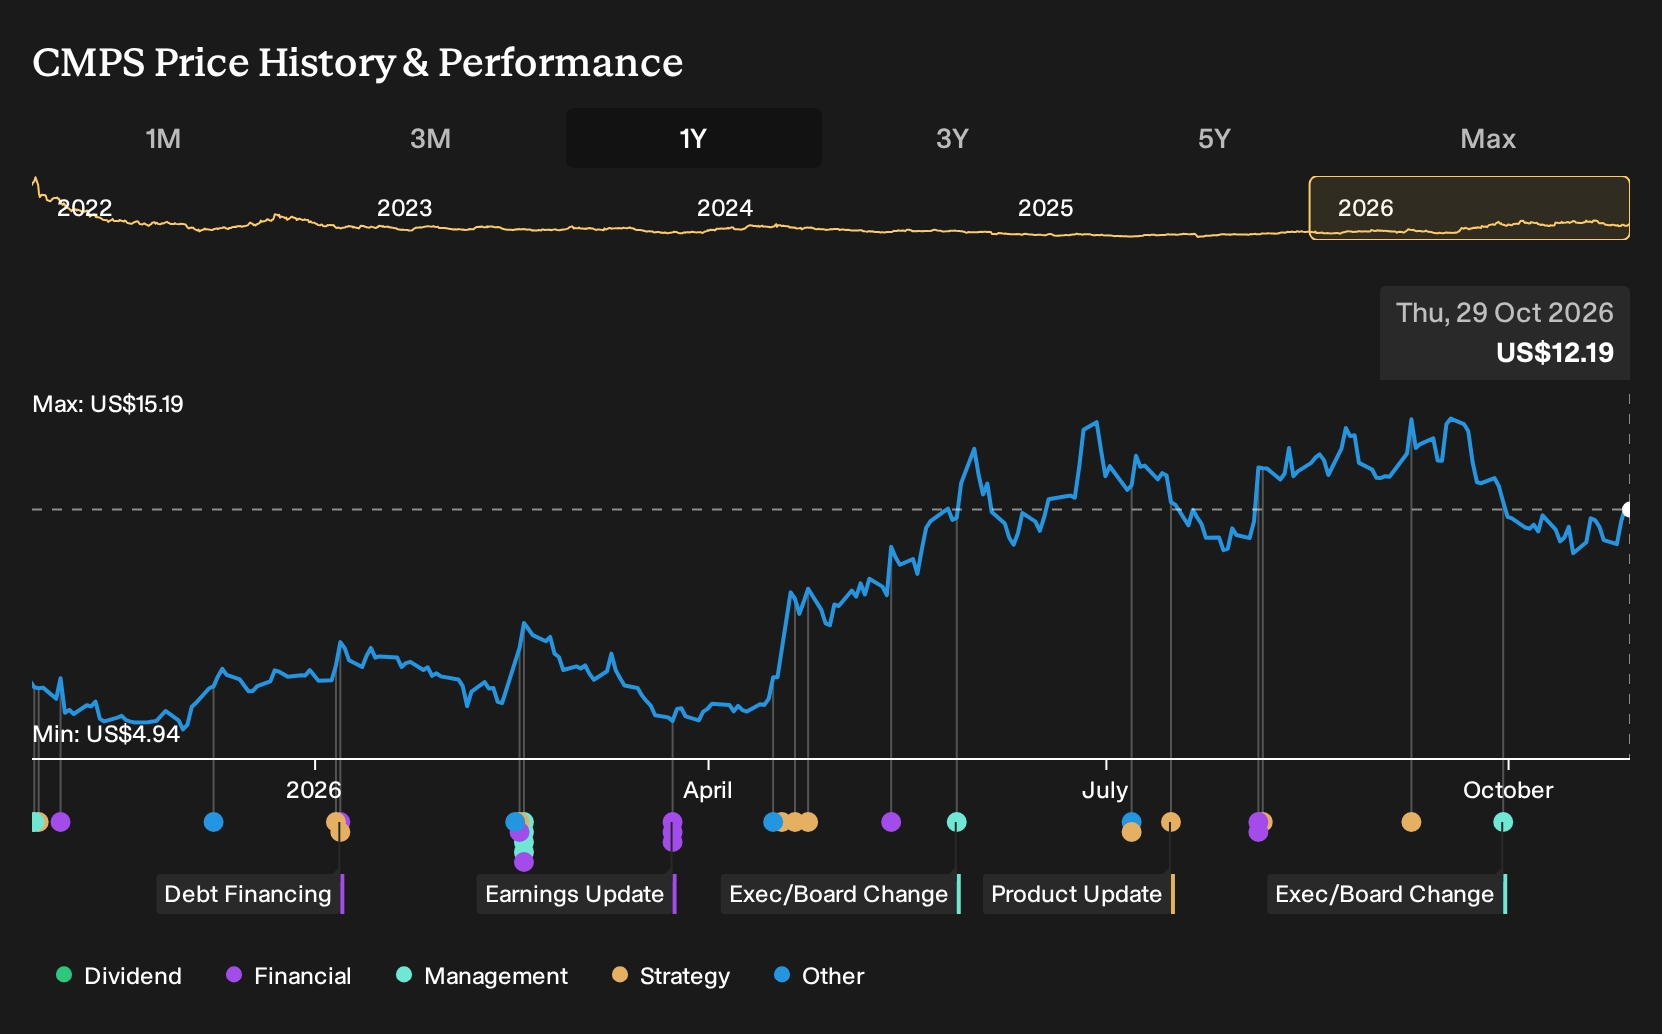
Exploring Other Perspectives
One alternate take on Compass Pathways leans heavily into the commercialization catalyst. The most optimistic analysts, before this NEI Congress news, were already penciling in about US$667.4 million of revenue and US$29.6 million of earnings by 2029. That is a very different story. Use this range of views as a prompt to compare several scenarios for yourself.
Explore 3 other COMPASS Pathways fair value estimates, including one that suggests as much as 754% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your COMPASS Pathways research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for COMPASS Pathways. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate COMPASS Pathways' overall financial health at a glance.
Looking For More Investment Ideas Beyond COMPASS Pathways?
Once you have a view on COMPASS Pathways, it can help to compare that thesis with other opportunities on the Simply Wall St Screener so you can see how different balance sheets, cash profiles and potential return drivers stack up side by side.
- If you want potential growth without giving up financial resilience, start with a group of companies that screen as relatively steady by reviewing 30 resilient stocks with low risk scores.
- For investors who care most about getting paid along the way, focus on cash return potential by checking out a selection of income plays through 7 dividend fortresses.
- If capital preservation comes first and business quality is non negotiable, concentrate your search on sturdier financial foundations with a curated list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com