


EN
Did Merchandising Missteps Just Shift TJX’s (TJX) Investment Narrative?
- TJX Companies disclosed that Senior Executive Vice President and Group President Kenneth Canestrari will step down from his executive officer role in January 2027 and fully retire in April 2027, with his contract extended to support a managed handover and ongoing transition work.
- The planned retirement keeps Canestrari in a senior capacity through April 2027, which may help TJX Companies address merchandising execution issues while preserving continuity in leadership and operational oversight.
- The focus now is on how TJX Companies' investment narrative adapts as the leadership transition coincides with pressure around merchandising execution quality.
TJX Companies Investment Narrative Recap
To own TJX Companies today, you need to be comfortable with a simple idea. The off price model still depends on getting the merchandise mix right, keeping traffic coming through the doors and protecting margins even when freight or diesel costs bite. The biggest near term swing factor is whether Marmaxx assortment issues are contained so they do not keep dragging on comparable sales.
The retirement timeline for Kenneth Canestrari looks measured rather than abrupt, so it does not materially change those near term catalysts or risks. The key variables for you remain execution on merchandising, competitive pressure from other value retailers and the impact of higher fuel and trucking costs on gross margin.
The most relevant piece of context is the Bell Global Equities Fund commentary after TJX Companies’ share price dropped more than 25%. That letter framed the move as a chance to gain exposure to what it views as a high quality operator that had run into merchandising execution problems at an awkward moment for consumer spending.
For you, the useful takeaway is not the fund’s view, but the framing of catalysts and risks. The letter highlights management’s record, the off price value proposition and access to inventory as potential supports, set against self inflicted mix issues and macro sensitive demand. That mix of operational repair work and external pressure is what should anchor your own thesis testing.
TJX Companies' current analyst narrative points to US$75.6b in revenue and US$7.3b in earnings by 2029. This outlook is built on 6.6% yearly top line growth and an earnings increase of about US$1.2b from US$6.1b today.
Uncover how TJX Companies' fair value indicates a 20% potential upside to its current price before the discount closes.
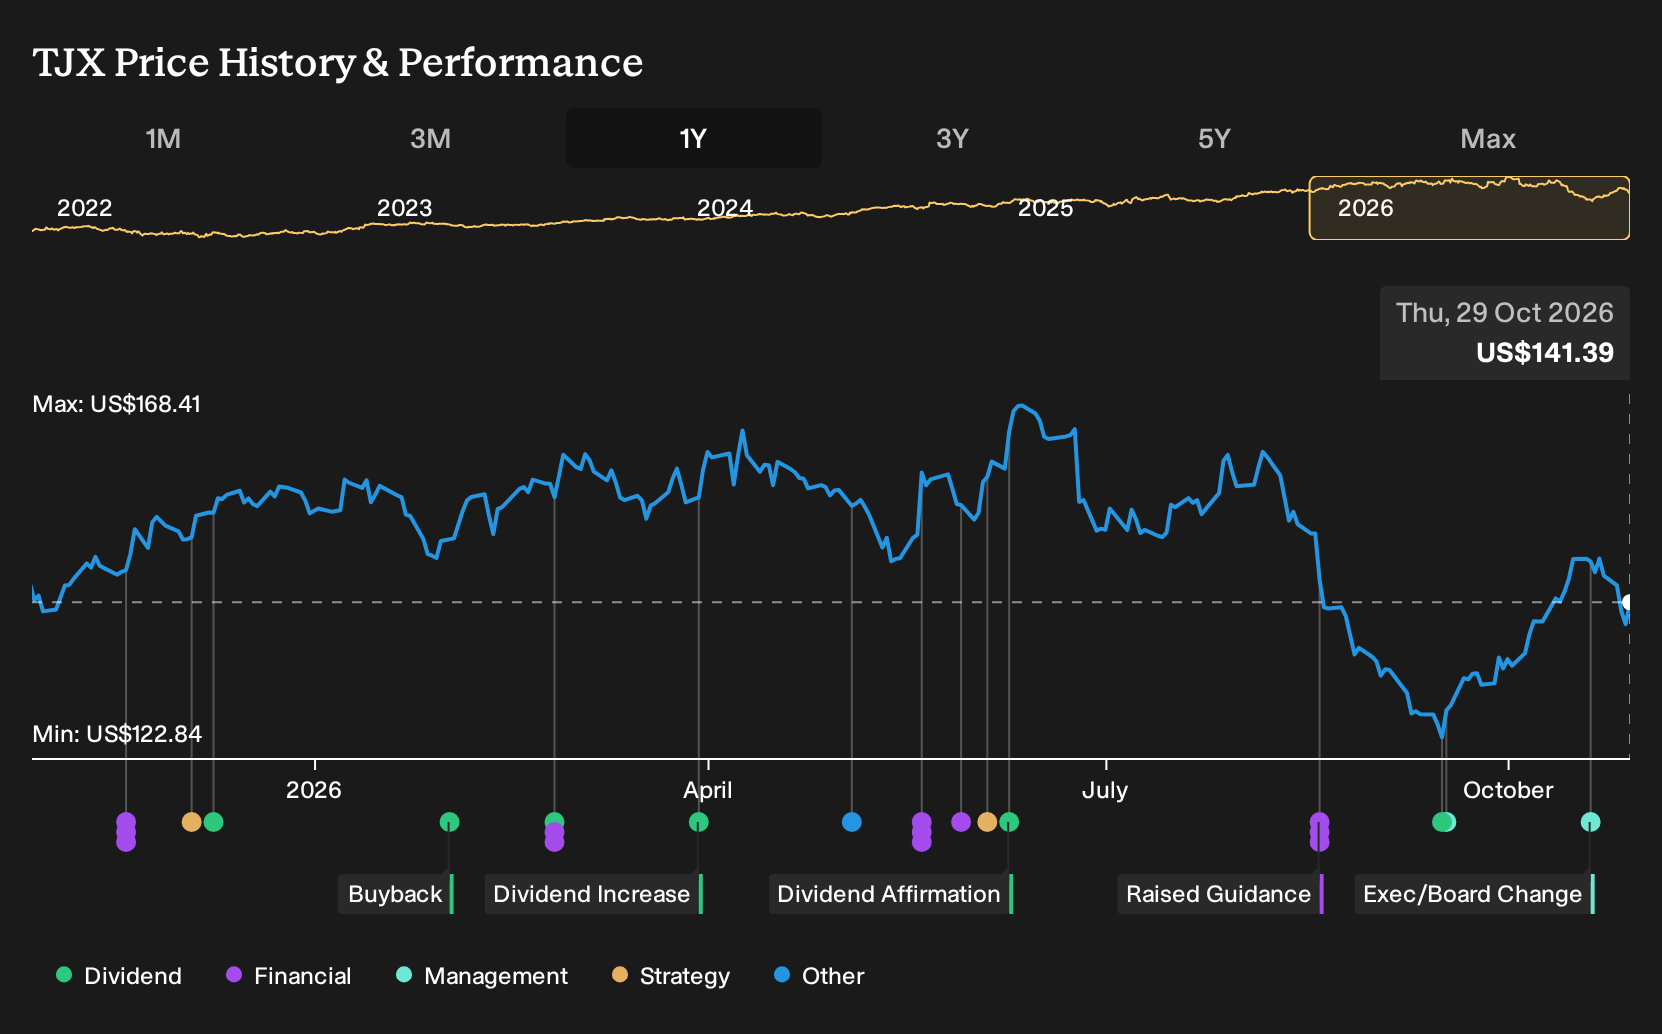
Exploring Other Perspectives
The lowest analysts focus on rising freight and wage costs at TJX Companies as the key risk, not just Marmaxx mix issues. They were pencilling in about US$74.1b of revenue and US$7.0b of earnings by 2029, which is more cautious than consensus. With the Canestrari transition now announced, those expectations may shift. Treat this as a moving target and compare several viewpoints before deciding what fits your own thesis.
Explore 7 other TJX Companies fair value estimates, including one that suggests as much as 23% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TJX Companies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TJX Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TJX Companies' overall financial health at a glance.
Looking for more investment ideas beyond TJX Companies?
Once you have a handle on TJX Companies and its leadership transition, it can help to line it up against a wider watchlist built around the kind of opportunities you care about most.
- If capital protection comes first for you, start by scanning a basket of 30 resilient stocks with low risk scores that score well on resilience and business quality.
- For those who want to focus on future potential at a sensible entry point, work through a curated group of 18 high quality undiscovered gems with strong underlying fundamentals.
- If balance sheet strength matters as much as the story, filter for a list of solid balance sheet and fundamentals (23 results) and compare how each business stacks up on debt and liquidity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com