


EN
Euro Zone Growth Puts Metso Stock And Industrial Shares In Focus
Euro zone growth just surprised to the upside, with Q3 GDP beating forecasts and hinting that consumers and businesses across the bloc are more active than many expected. That mix of stronger demand, rising investment in areas like AI and infrastructure, and looming ECB rate decisions is already reshaping where risk is rewarded. This article walks through 3 euro zone stocks exposed to this news and how investors might think about them.
The three stocks in focus below are just a starter pack, and the full screen surfaced 7 more euro zone cyclical consumer and industrial companies with equally compelling stories that are not covered in this article. To identify, compare, and analyze the highest conviction ideas from this universe, head straight into the Euro Zone Cyclical Consumer & Industrial Equities screener.
ID Logistics Group (ENXTPA:IDL)
Overview: ID Logistics Group runs contract logistics operations, handling warehousing, transport, and e-commerce fulfillment for large consumer, retail, and industrial clients.
Operations: The group generates about €4.1b in trucking transportation revenue, with roughly €1.0b reported in France and the remainder from other regions.
Market Cap: €2.4b
ID Logistics Group is closely linked to euro zone consumer and industrial activity, providing logistics capacity that is positioned to serve retail, e-commerce, and goods flows. The stock combines this demand exposure with a sizeable trucking business and scale in France, while one unresolved pressure could affect how much of that volume turns into durable profit.
That pressure is already in focus for investors weighing ID Logistics Group against other euro zone cyclicals, and the analysis report for ID Logistics Group highlights where volume could be masking risk or upside.

Fincantieri (BIT:FCT)
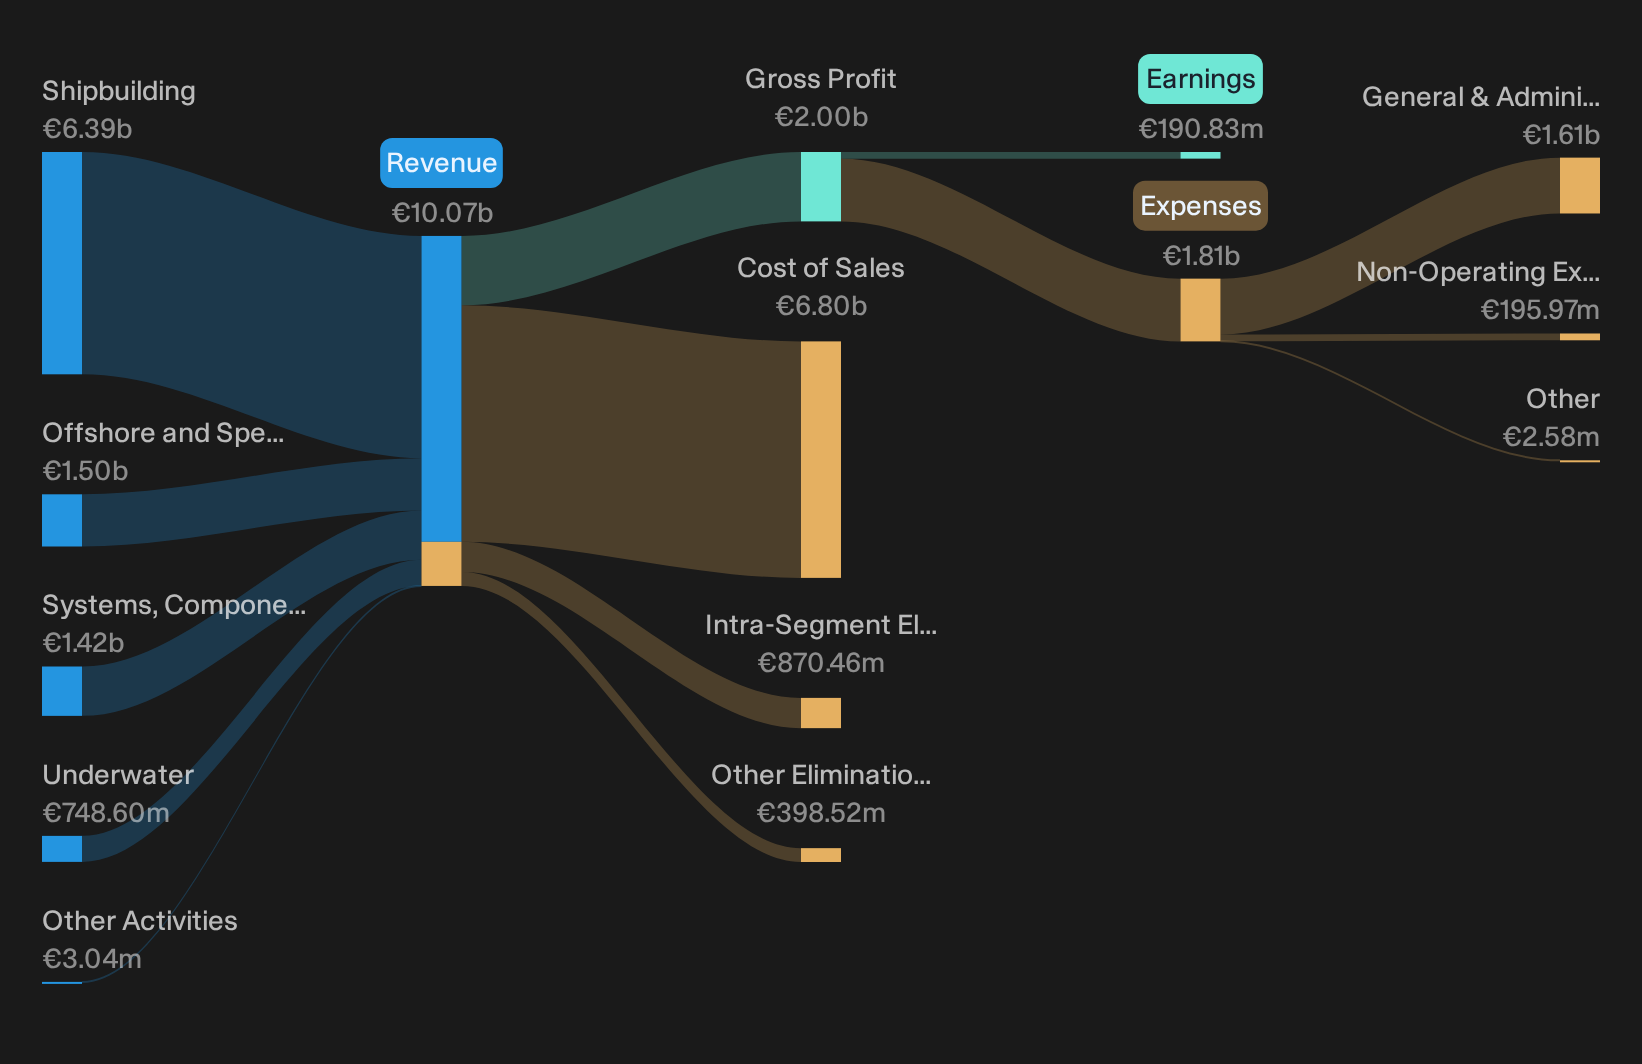
Overview: Fincantieri S.p.A. is a euro zone shipbuilder that designs and constructs cruise, naval, underwater and offshore vessels plus related systems and services.
Operations: Fincantieri generates about €6.4b from Shipbuilding, €1.5b from Offshore and Specialized Vessels, €1.4b from Systems, Components and Infrastructure, and €749 million from Underwater, with most revenue earned abroad.
Market Cap: €4.6b
Fincantieri fits this cyclical euro zone industrial screen as a pure play on capital spending for ships, underwater systems and maritime infrastructure. The recent macro surprise simply sharpens investor attention on how that order book and balance sheet interact.
"Accelerazione della spesa per la difesa navale in Europa, espansione della divisione Subacquea (WASS, NextGeo) e rapido deleveraging di bilancio (leva scesa a 1,0x), a fronte del rischio gestito dei contratti a prezzo fisso."
What happens to future margins and cash flow resilience if a single unseen pressure shifts how that mix of projects is priced?
If that pressure point is what you care about, read the full narrative for Fincantieri to see how pricing risk, order quality and balance sheet trends could be interacting.
Metso Oyj (HLSE:METSO)
Overview: Metso Oyj supplies equipment, technology and life cycle services for aggregates, minerals processing and metals refining customers worldwide.
Operations: Metso Oyj generates about €4.1b from Minerals and €1.3b from Aggregates, with meaningful exposure to APAC, South America and EMEA.
Market Cap: €14.3b
Metso Oyj plugs into this euro zone cyclical screen as a geared play on construction and minerals investment. Equipment demand and long-term service contracts tend to move with capex cycles rather than short-lived sentiment swings.
"Strong and rising order intake in Minerals services, with aftermarket now representing 68% of segment sales and contributing to higher gross and adjusted EBITA margins in Q2 2026, indicates faster growth and margin expansion potential for recurring service revenues versus capital equipment and supports earnings quality."
What happens to earnings power if a single unseen pressure alters how quickly that higher margin mix takes hold across the portfolio?
That unseen pressure is exactly where the story gets interesting, and the full narrative for Metso Oyj shows how Metso Oyj’s mix could be quietly accelerating or masking risk.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout trends, shifting momentum and under the radar stories often get caught late once prices start flying. Scan what others miss and act now.
- Spot potential trend leaders early by running the 200 high quality undervalued stocks while these opportunities are still under the radar for now and pricing has not fully caught up.
- Chase real revenue engines, not hype, by scanning the 38 profitable AI stocks that aren't just burning cash before the crowd bids up the next wave of AI momentum trades.
- Target resilience when markets wobble by checking the 221 resilient stocks with low risk scores so you are not caught holding fragile stories when sentiment drops.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com