


EN
Does Earnings Beat Change The Bull Case For Federated Hermes Stock (FHI)?
- Federated Hermes reported third quarter 2026 earnings per diluted share of $1.50 on revenue ahead of expectations, alongside record equity assets of $110.5 billion and a declared quarterly dividend of $0.38 per share payable on November 13, 2026.
- The combination of an earnings and revenue beat, record equity and alternatives demand, and ongoing dividend payments highlights how Federated Hermes is leaning on higher fee asset categories while still returning cash to shareholders.
- We will look at how Federated Hermes' investment narrative evolves in light of the earnings beat and record equity assets.
See how Federated Hermes’ earnings beat and steady dividend compare with peers by exploring a curated set of 7 dividend fortresses in the current market backdrop.
Federated Hermes Investment Narrative Recap
To own Federated Hermes, you need to believe its mix of fee based equity, alternatives, and a very large liquidity franchise can keep generating steady earnings even as pricing pressure and competition remain intense. The latest quarter supports that thesis on operations. Earnings per diluted share of $1.50 and record US$110.5b of equity assets show that higher fee segments are still doing work.
The near term swing factor is whether equity and alternative inflows can consistently offset any softness in money market fees and higher operating costs from expansion. That catalyst looks intact after the earnings beat. The biggest risk remains prolonged fee compression and money fund share or flow pressure, which this update does not remove.
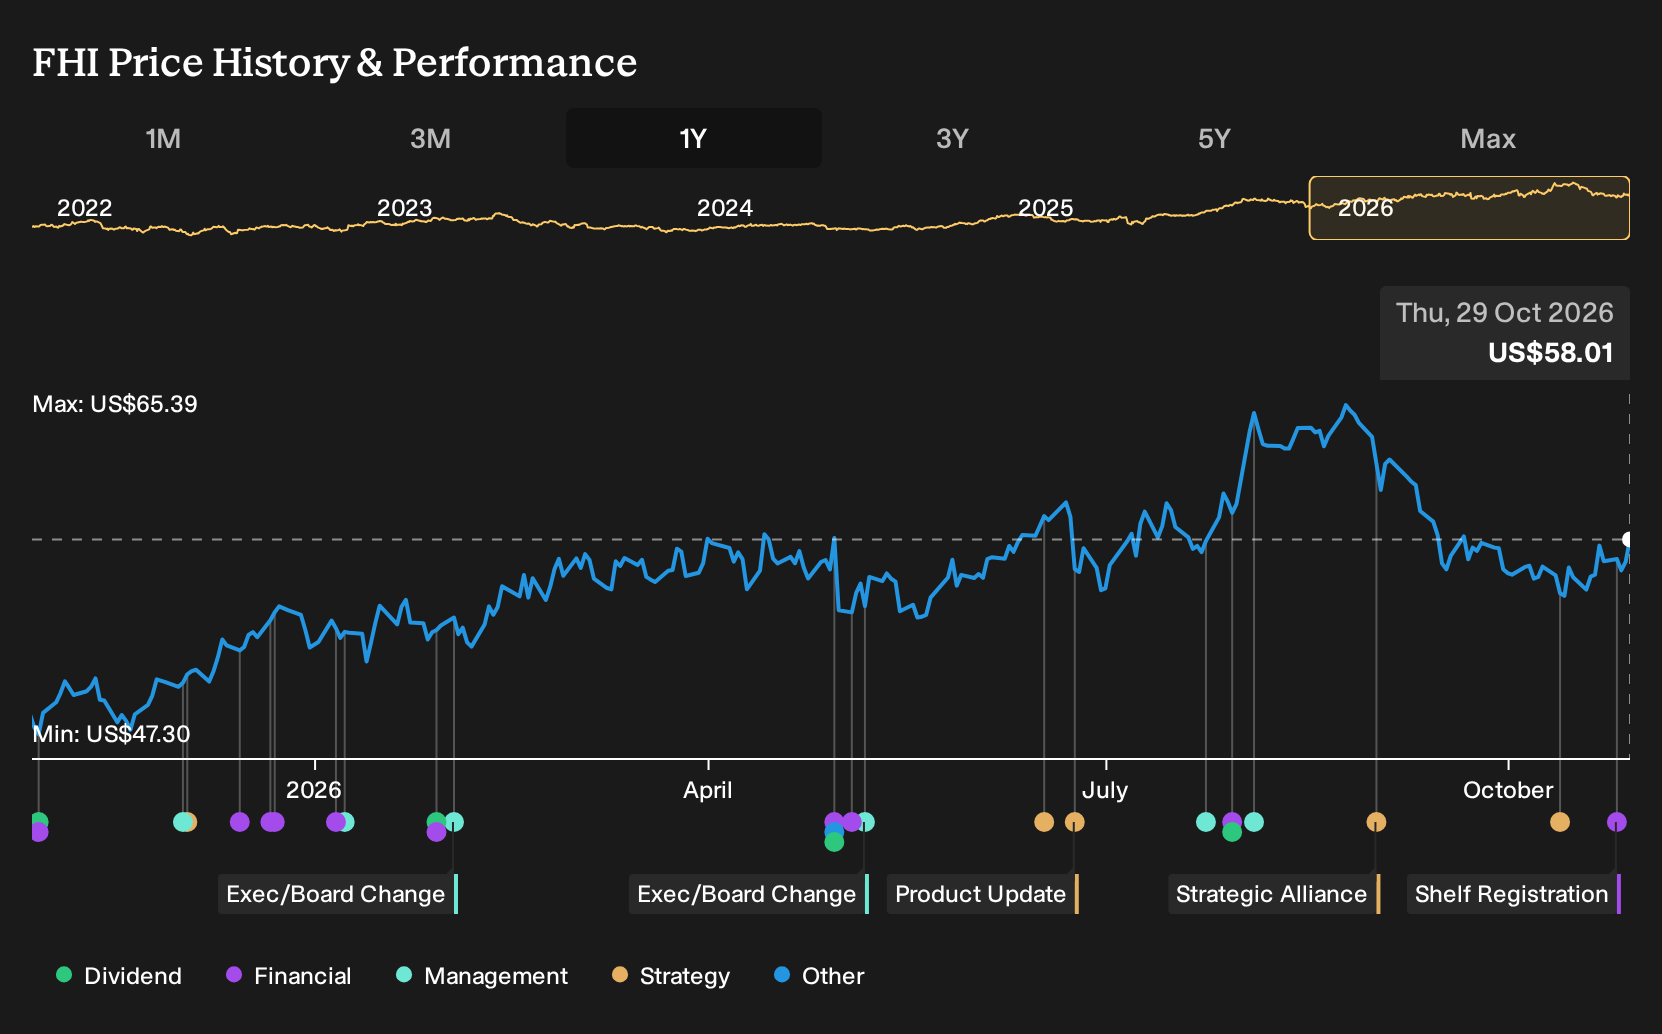
The fresh US$0.38 per share dividend declaration is the announcement that ties closest to this earnings print. It extends a pattern of regular cash returns while the business carries a market cap of about US$4.0b and has grown earnings by 8.4% per year over the past 5 years. For income focused holders, that reliability matters as much as the quarterly headline numbers.
That payout also tests the core investment case. If Federated Hermes can keep funding a 2.62% yield, invest in areas like quantitative equity and alternatives, and manage higher expense lines without eroding its 20.3% net margin too far, the stock’s appeal rests on execution rather than on changes in its valuation multiple. Any stumble on costs or asset gathering would quickly turn that same dividend into a pressure point.
Federated Hermes' analyst narrative points to revenue of US$2.1b and earnings of US$424.0m by 2029, based on an assumed 3.4% yearly revenue growth rate and an earnings increase of about US$30.8m from current earnings of US$393.2m.
Uncover why Federated Hermes' fair value indicates a 5% potential upside to its current price before the discount narrows.
Exploring Other Perspectives
Fair value estimates for Federated Hermes from 2 members of the Simply Wall St Community cluster between US$61 and about US$70.9 per share, so you are seeing a tight but not uniform band of views. Set that against fee compression risk, rising costs and liquidity concentration, then weigh how differently other investors might frame the same facts.
Explore another Federated Hermes fair value estimate, including one that suggests it could be worth just $61.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Federated Hermes research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Federated Hermes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Federated Hermes' overall financial health at a glance.
Looking For More Investment Ideas Beyond Federated Hermes?
If you want to pressure test your view on Federated Hermes and broaden your watchlist, the Simply Wall St Screener is a useful way to scan the market using the same kind of fundamentals discussed here.
- Focus on quality at a reasonable price by scanning a curated 30 high quality undervalued stocks that combine stronger balance sheets and cash flows with more modest expectations baked into their prices.
- If income is a priority, compare Federated Hermes' yield and payout profile against a broader pool of 7 dividend fortresses that aim to pair higher distributions with business resilience.
- For a fresh set of ideas off the beaten path, filter for 18 high quality undiscovered gems that show solid fundamentals yet receive relatively little attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com