


EN
Earnings Beat Might Change The Case For Investing In Entegris Stock (ENTG)
- Entegris reported record third quarter 2026 results, with revenue and earnings surpassing analyst expectations and segment sales growth of 15.9% in Materials Solutions and 31.3% in Advanced Purity Solutions.
- The firm paired this strong quarter with fourth quarter guidance that targets US$1,025 million to US$1,055 million in sales and GAAP diluted EPS of US$1.09 to US$1.17. This highlights how semiconductor materials demand is feeding through to both growth and margin expansion.
- The focus now shifts to how Entegris' strong quarter and upbeat fourth quarter guidance might reshape the investment narrative investors rely on.
Entegris Investment Narrative Recap
To own Entegris, you need to believe that semiconductor complexity and AI related materials demand keep pulling more chemicals, filtration and purity solutions into each wafer. The latest record quarter and fourth quarter guidance in the US$1,025 million to US$1,055 million range point to that thesis still playing out in operations.
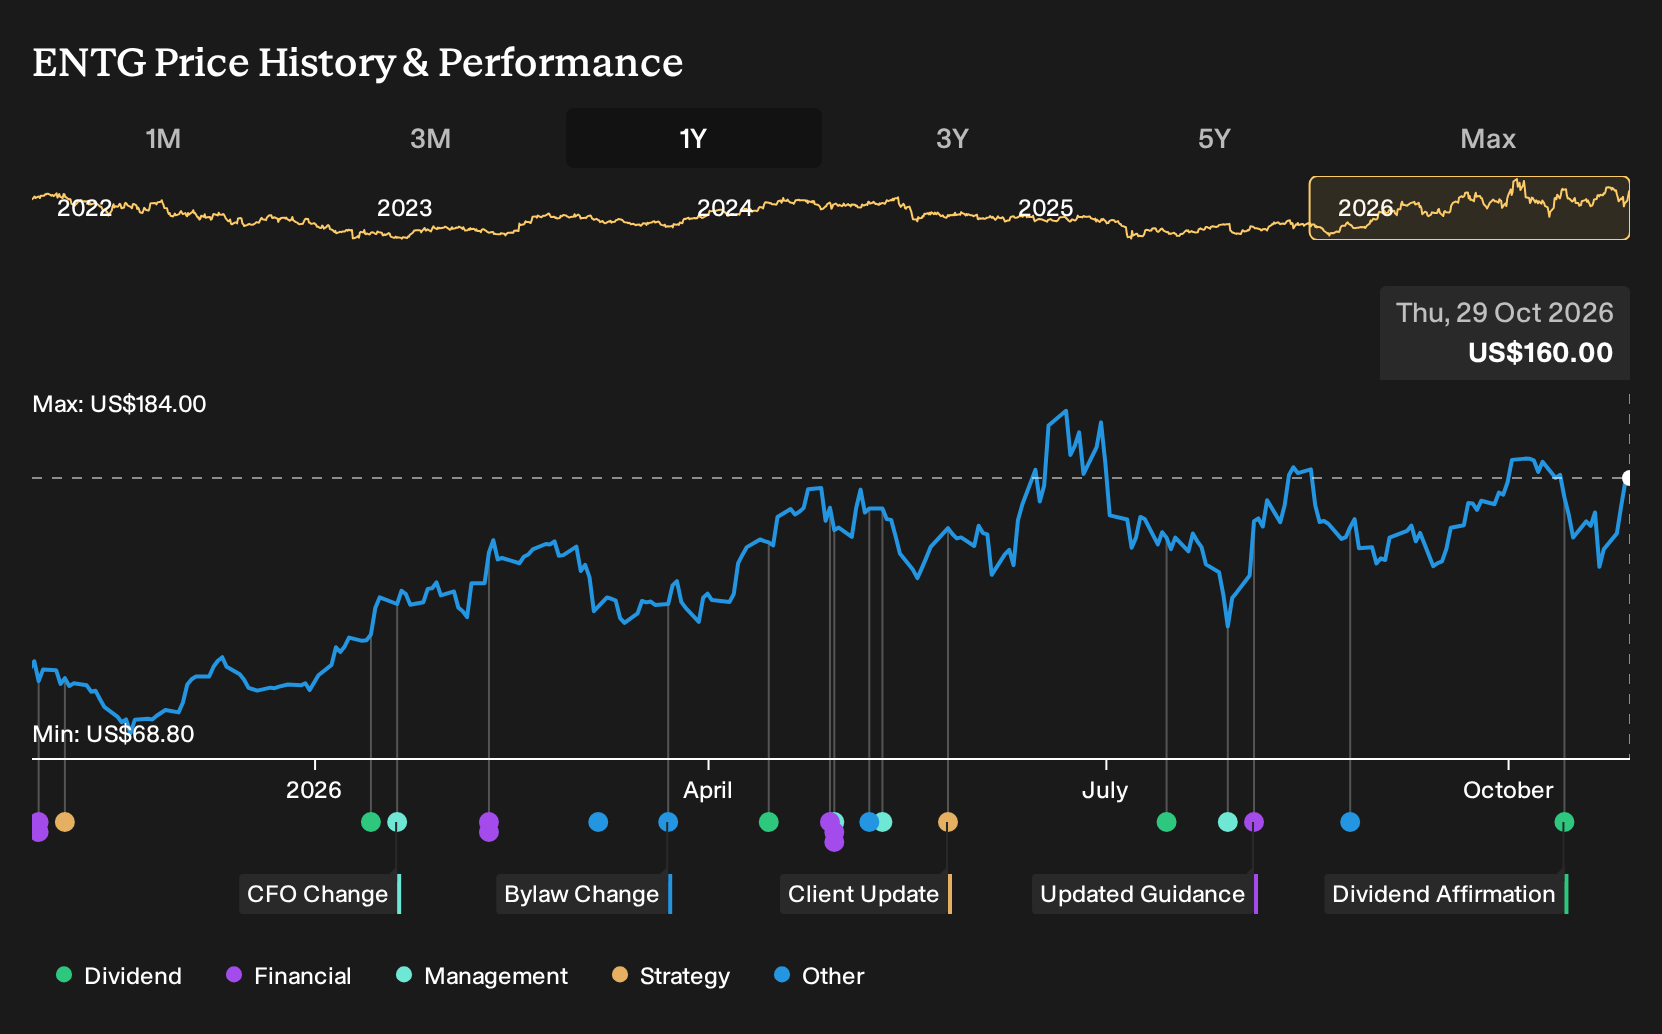
In the short term, the key catalyst is continued execution in Materials Solutions and Advanced Purity Solutions while margins hold up as new facilities ramp. The biggest immediate risk appears to be more in sentiment than in fundamentals. The stock carries a rich P/E and has shown sharp swings when AI expectations across the sector reset.
The fourth quarter outlook is the announcement that matters most here. Management is calling for GAAP net income of US$168 million to US$181 million and GAAP operating income of US$235 million to US$250 million. That keeps attention squarely on whether Entegris can sustain margin progress while supporting rising AI heavy chip demand.
This guidance also interacts with the earlier decision to maintain a US$0.10 quarterly dividend. Investors now have a clearer near term view on earnings coverage for that payout, while still needing to weigh debt levels, a high valuation and sector volatility. Execution against this outlook will likely shape how patient shareholders choose to be with the story.
Entegris' current earnings of $305.5 million are set against analyst forecasts that call for revenue of $4.5b and earnings of $726.8 million by 2029. These forecasts are based on an assumed 10.7% yearly revenue growth rate over the next three years and an earnings increase of about 2.4x from today.
Uncover why Entegris' fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view leans hard into AI materials demand for Entegris as the real catalyst. The most optimistic analysts were already modeling revenue of about US$5.2b and earnings near US$799.0 million by 2029, compared with US$4.5b and US$726.8 million in the baseline case. That gap shows how widely opinions can differ, so it can help to explore several viewpoints and decide which assumptions feel realistic to you, then see how fresh guidance might shift those narratives from here.
Explore 4 other Entegris fair value estimates, including one that suggests as much as 34% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Entegris research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Entegris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Entegris' overall financial health at a glance.
Looking for more investment ideas beyond Entegris?
If the Entegris story has sharpened your thinking about risk, return and balance sheet strength, it can help to line it up against a wider watchlist using the Simply Wall St Screener. Pick a few focused filters, compare fundamentals side by side and let the data point you toward opportunities that fit your own comfort zone.
- If capital preservation is high on your list, you could start with companies that pair resilience with measured risk by scanning 30 resilient stocks with low risk scores.
- For investors who focus primarily on financial strength, consider businesses with cleaner balance sheets and steadier fundamentals through a curated list of solid balance sheet and fundamentals (23 results).
- To look for less crowded stories supported by solid numbers, review a targeted 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com