


EN
Stryker (SYK) Stock Could Still Be Undervalued On Recent Pullback
Stryker has rewarded long term holders with solid gains over the past few years, yet the share price has recently pulled back even as the business continues to focus on cash generation. With fresh corporate moves and shifting expectations now in play, the key issue is whether the current valuation lines up with the cash flows the company can produce over time.
- Over 5 years, Stryker has delivered a total return of 21.7%, which raises the question of how much future cash flow is already reflected in the price.
- Recent profit growth alongside higher organic sales and a larger share repurchase program can influence how much free cash the business retains for shareholders versus reinvests for future expansion.
- What if you looked at Stryker through its earnings instead? See what Stryker's 32.1x P/E says about the price.
The stock's next move may depend on whether today's US$311.75 share price is justified by the cash flows implied by Stryker's current business performance and outlook.
If you want to stress test this same cash flow question across a wider set of opportunities, scan through 30 high quality undervalued stocks.
Is Stryker a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Stryker can generate for shareholders over time. Latest twelve month free cash flow sits at about $4.7b, and the projections behind this DCF assume that cash generation continues growing from that base rather than shrinking.
Across the two stage Free Cash Flow to Equity model, those expanding cash flows imply an intrinsic worth that sits meaningfully above the current US$311.75 share price. Because the Q3 2026 result combined solid organic sales with an earnings miss and fresh buyback authorization, the current market price may still be giving more weight to near term profit noise than to the cash flow profile implied in this DCF. Find out what Stryker could be worth using our Discounted Cash Flow (DCF) estimate.
The Stryker Narrative: What Would Justify Today's Price?
Narratives for Stryker pick up where the valuation puzzle leaves off, explaining which paths for growth, profitability and earnings would need to occur for the stock to be worth meaningfully more or less than today's price on Simply Wall St's Community page. Each scenario connects its figures to a clear stance on how Stryker's growth, margins and risk profile might change, which you can track against future announcements and financial updates.
On Simply Wall St, the bullish Stryker camp sees more upside in the existing business plan than the more measured, quality-at-a-fair-price view.
Bull case: 16% undervalued
"The current valuation implies the share price already reflects near-term peripheral vascular and legal risks but does not fully credit the potential benefit from sustained margin expansion and broader procedure penetration..."
Discover why this Narrative puts Stryker at 16% undervalued.
Bear case: roughly fairly valued
"Risks: hospital capex cycles, pricing pressure, integration risk from acquisitions, and a premium valuation that leaves little room for execution slips..."
Explore why this Narrative puts Stryker at roughly fairly valued.
One more angle on Stryker that could change your view
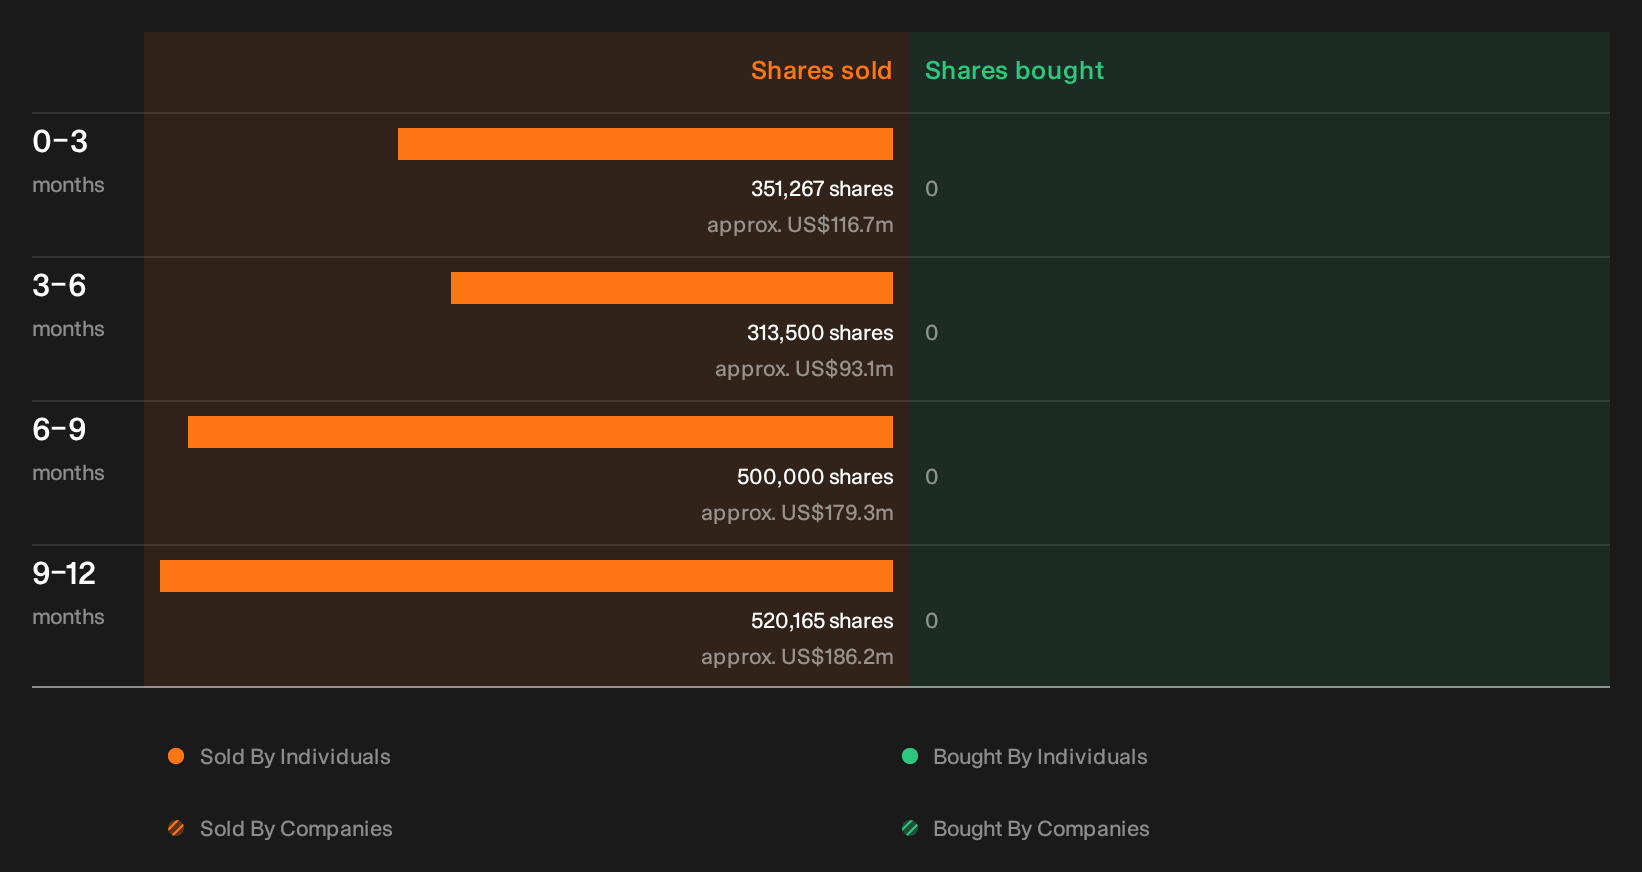
Valuation tells only part of the story for Stryker, because recent activity by people inside the business may reveal a different set of signals that deserve a closer look. See the recent insider selling flagged for Stryker.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com