


EN
Earnings Preview: What to Expect From Everpure's Report
Everpure, Inc. (P), headquartered in Santa Clara, California, provides data storage and management technologies, products, and services. Valued at $45.7 billion by market cap, the company offers flash enterprise arrays for workloads including server consolidation, desktop virtualization, database, and cloud computing. The leading storage and data management platform is expected to announce its fiscal third-quarter earnings for 2027 in the near term.
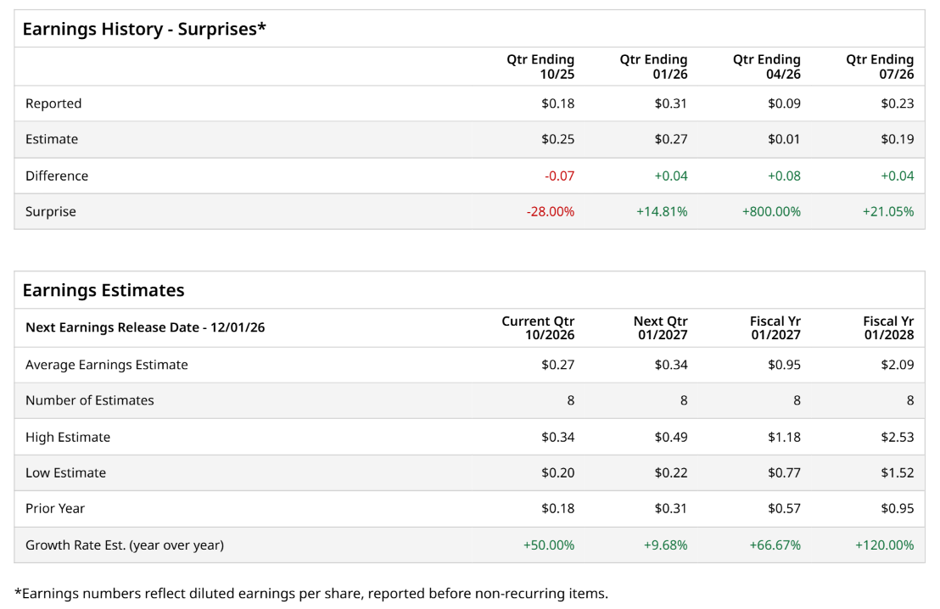
Ahead of the event, analysts expect Everpure to report a profit of $0.27 per share on a diluted basis, up 50% from $0.18 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
For the full year, analysts expect Everpure to report EPS of $0.95, up 66.7% from $0.57 in fiscal 2026. Its EPS is expected to rise 120% year over year to $2.09 in fiscal 2028.
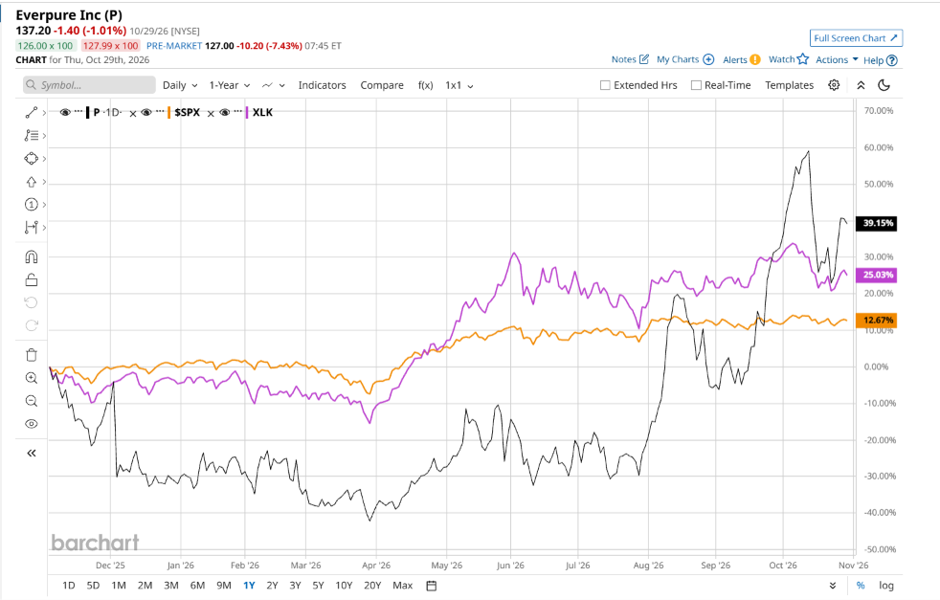
P stock has notably outperformed the S&P 500 Index’s ($SPX) 12% gains over the past 52 weeks, with shares up 40.6% during this period. Similarly, it outperformed the State Street Technology Select Sector SPDR ETF’s (XLK) 24.1% gains over the same time frame.
Everpure’s outperformance is driven by robust enterprise demand, pricing power, and surging adoption of its Evergreen//One Storage-as-a-Service model, which has surpassed a $1 billion annualized run rate. Despite declining system unit volumes, revenue grew due to higher pricing, a mix shift toward high-performance configurations, and massive growth in large-scale enterprise deals, including a 385% surge in over $20 million contracts. Furthermore, the company secured a major hyperscale design win for its DirectFlash technology and expanded its international revenue greatly, positioning it strongly for sustained long-term growth.
Analysts’ consensus opinion on P stock is bullish, with a “Strong Buy” rating overall. Out of 20 analysts covering the stock, 15 advise a “Strong Buy” rating, three suggest a “Moderate Buy,” one gives a “Hold,” and one recommends a “Strong Sell.” P’s average analyst price target is $153.78, indicating a potential upside of 12.1% from the current levels.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.