


EN
Cavco Industries (CVCO) Beat Earnings Expectations, Is It Still 18% Below Fair Value?
Cavco Industries (CVCO) just put fresh numbers on the table for its fiscal second quarter, reporting higher sales, slightly stronger quarterly profit, and earnings per share that topped Wall Street expectations.
The share price reaction has been relatively muted so far, with Cavco Industries up 2.8% on the day to US$547.25 while the year-to-date share price return is down 7.5%. However, long-term total shareholder returns of 8.6% over one year and more than doubling over three and five years signal that momentum for the broader story has been built over time rather than in recent weeks.
Spot fresh earnings momentum at Cavco Industries, then size up other factory-built housing and consumer durables players using our hand picked 18 high quality undiscovered gems as a comparison set.Cavco Industries now trades at a double digit discount to analyst targets after a small post earnings bump. Is the market sensibly cautious on factory built housing, or mispricing a solid operator?
Most Popular Narrative: 17.7% Undervalued
Cavco Industries is framed as undervalued in the most followed thesis, with a fair value of $665 against the current $547.25 share price. The gap hinges on how well the business can turn demand and acquisitions into stronger profitability.
The main thing that has to go right is Cavco Industries converting strong order momentum, capacity additions, and cost synergies into healthier margins despite ongoing tariff and input cost headwinds.
The current valuation implies the market is not fully pricing in Cavco Industries' combination of record volumes, growing Financial Services profitability, and substantial share repurchases, which this narrative views as a positive and undervalued setup for the share price.
See why 7 investors see Cavco Industries as 18% undervalued.
Result: Fair Value of $665 (UNDERVALUED)
Still, the bullish Cavco Industries case depends on margins improving, while tariffs and input costs remain a swing factor that could keep earnings under pressure.
Find out about the key risks to this Cavco Industries narrative.
Another View: Cavco Industries On Earnings Multiples
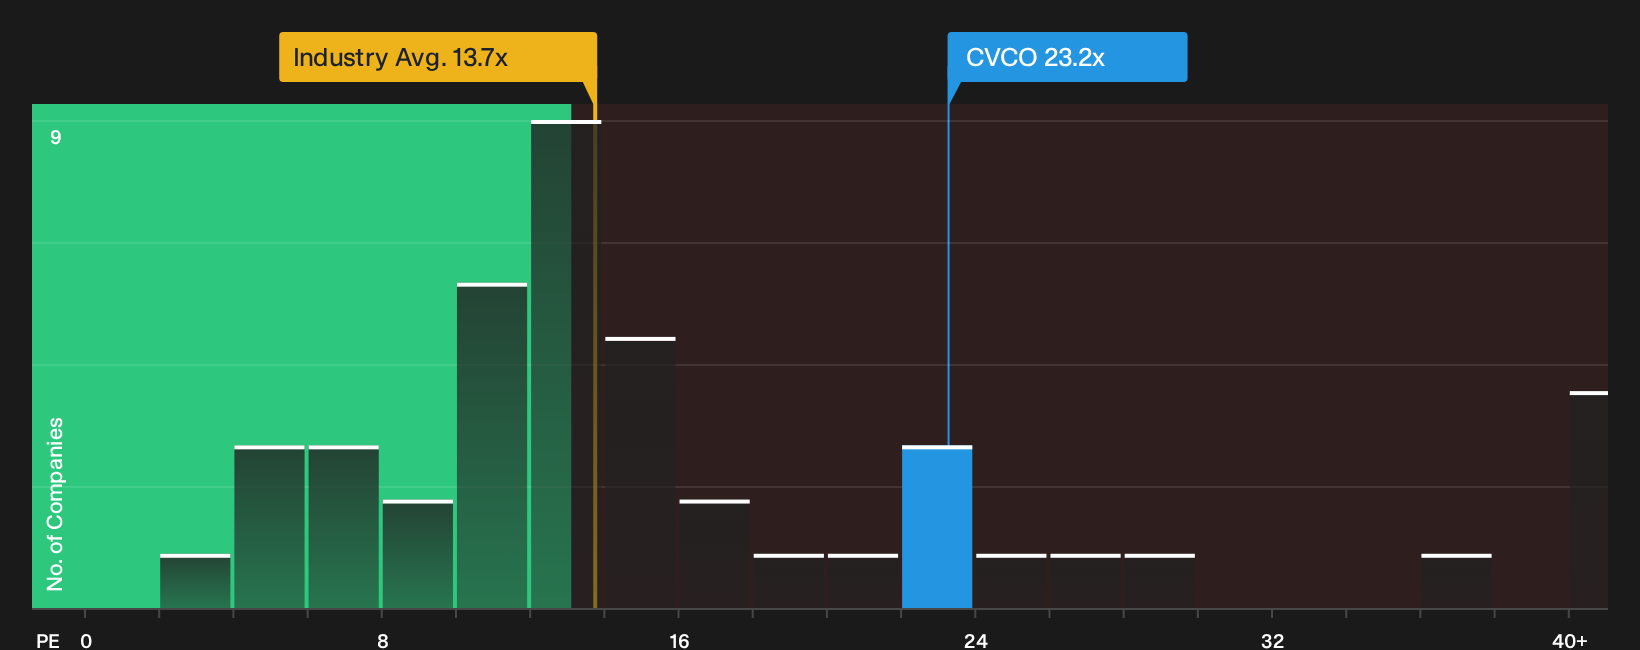
The first narrative leans on a fair value of $665 for Cavco Industries, yet the P/E picture points the other way. CVCO trades at 23.2x earnings, while direct peers average 17.7x and the wider US Consumer Durables group sits at 12.7x. A fair ratio of 17.3x suggests the valuation could just as easily compress. Which signal do you trust more: the story or the multiple?
To see what the numbers say if the market drifts toward that fair ratio, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
This all reads either quietly confident or slightly stretched. Either way, now is the moment to test the numbers yourself and stress test your own thesis using the 2 key rewards.
Looking for more Cavco Industries style investment ideas?
Curious what else might deserve a place on your watchlist beyond Cavco Industries? Use the Simply Wall Street screener to quickly surface fresh opportunities that match your approach.
- Target quality at a discount by scanning a curated 30 high quality undervalued stocks that combine solid fundamentals with prices that lag their underlying business strength.
- Prioritise resilience and sleep easier at night by filtering for 30 resilient stocks with low risk scores that score well on financial health and earnings stability.
- Hunt for tomorrow's potential leaders before they attract attention by focusing on a 9 elite penny stocks with strong financials backed by stronger balance sheets and fundamentals than the crowd expects.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com