


EN
Earnings Guidance Reset Could Be A Game Changer For F.N.B (FNB)
- F.N.B. Corporation reported third quarter 2026 net interest income of US$376.52 million and net income of US$152.86 million, while unaudited net loan charge offs for the period were US$11.0 million, lower than the US$19.7 million reported a year earlier.
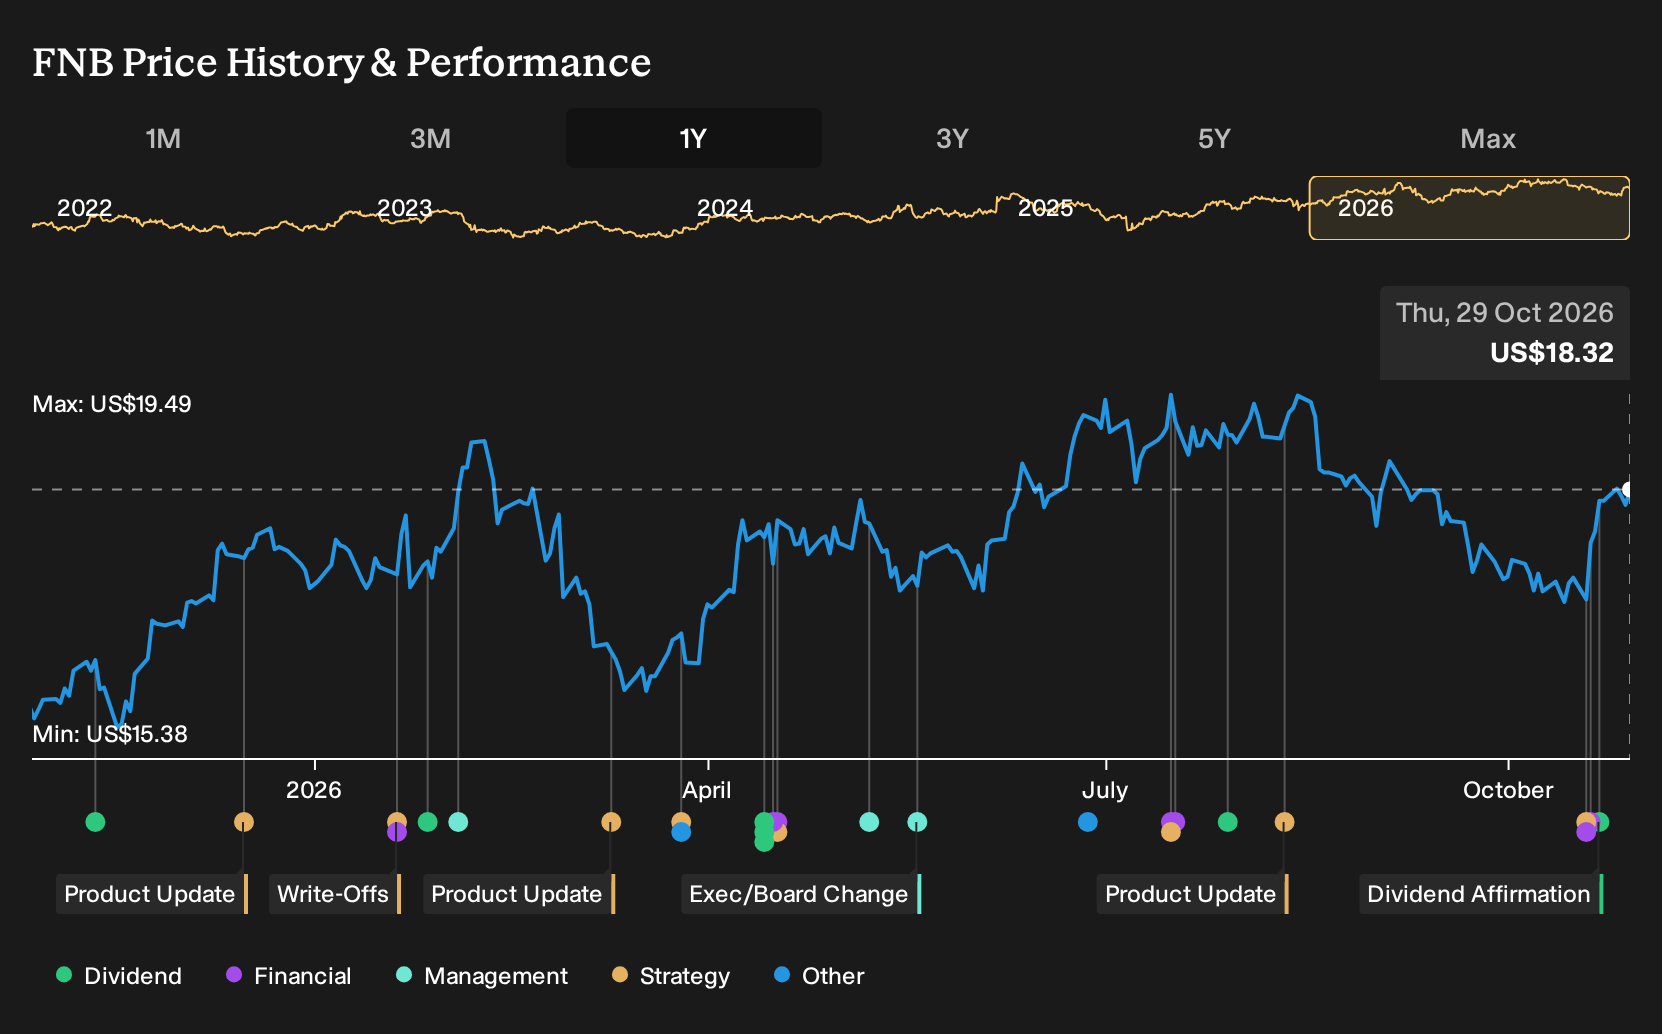
- The board also declared a US$0.13 quarterly cash dividend per common share, payable on December 15, 2026 to holders of record on December 1, alongside revised full year 2026 net interest income guidance of US$1.485 billion to US$1.5 billion that reflects ongoing deposit competition.
- Investors may now consider how F.N.B. Corporation's updated 2026 net interest income guidance could relate to the existing investment narrative focused on fee growth.
F.N.B Investment Narrative Recap
To own F.N.B, you need to be comfortable with a bank that still leans heavily on net interest income while trying to build out fee businesses and digital tools. The revised 2026 net interest income range of US$1.485b to US$1.5b keeps attention on funding costs and loan pricing as the key near term swing factor.
The main short term catalyst remains execution on fee growth and technology projects that are expected to support efficiency and earnings quality. The biggest risk sits in deposit competition and any regional cooling in the Mid Atlantic and Southeast, which could pressure spreads and loan demand if it worsens.
The updated full year 2026 net interest income guidance is the announcement that ties most directly to this setup. Management is explicitly incorporating higher deposit competition into its outlook, which provides a clearer framework for how much room F.N.B has to absorb funding cost pressure while still supporting earnings.
For you as a shareholder, that revised range helps when weighing catalysts such as digital and AI rollouts, fee franchise expansion and capital flexibility against risks such as a potential commercial real estate setback or a regional slowdown. It sharpens the focus on execution rather than changing the overall thesis.
F.N.B's current narrative anchors on analyst expectations that revenues reach US$2.2b and earnings come in at US$691.8 million by 2029, based on a forecast 7.5% yearly revenue growth rate and an earnings increase of about US$87.8 million from US$604.0 million today.
Uncover how F.N.B's fair value indicates a 13% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket F.N.B. Corporation between about US$20.72 and US$30.07 per share, which already shows how far opinions can stretch. Those views were set before the latest dividend affirmation, updated net interest income guidance and charge off figures, so you may want to test your own stance against a wider spread of community viewpoints.
Explore another F.N.B fair value estimate, including one that suggests it could be worth just $20.72.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your F.N.B research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for F.N.B. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate F.N.B's overall financial health at a glance.
Looking for more F.N.B style ideas?
Once you have formed a view on F.N.B, it can help to line it up against other banks and financials with different income mixes, balance sheet strengths and dividend profiles. The Simply Wall St Screener lets you do that quickly without losing sight of the risk and income trade offs that matter most to you.
- For investors who want a wider opportunity set but still care about financial resilience, scan a 30 resilient stocks with low risk scores that may help you focus on businesses with more measured risk profiles.
- If you are hunting for companies that the market may be pricing cautiously relative to their fundamentals, sort through a 30 high quality undervalued stocks that can surface ideas worth a closer look.
- Income focused readers who like the regular cash flow of payouts can review a 7 dividend fortresses that highlights businesses offering higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com