


EN
Why Everyone Is Watching Thermo Fisher Scientific (TMO) Today
Thermo Fisher Scientific (TMO) just posted third quarter 2026 results, reporting sales of US$12.1b and net income of US$1.7b. These figures give investors fresh numbers to reassess the stock.
Thermo Fisher Scientific’s recent earnings update landed alongside a strong run in the share price, with a 90 day share price return of 23.5% and a 1 year total shareholder return of 28.0%. This suggests momentum has been building rather than fading as investors react to its position in sequencing and diagnostics markets.
Capitalize on Thermo Fisher Scientific’s momentum in high-demand lab technologies by scanning a curated shortlist of 36 healthcare AI stocks that are also building around AI-powered diagnostics and genomics.After a near 30% total return over the past year and fresh earnings on the table, Thermo Fisher Scientific now forces a simple choice: lean into the current price strength or wait for a calmer entry as valuation gets unpacked next.
Most Popular Narrative: 15% Undervalued
Against a last close of $709.18, the most followed narrative puts Thermo Fisher Scientific’s fair value at $830. This frames today’s strength as only a partial reflection of its long term earnings story under an 8.37% discount rate.
The main thing that has to go right is that Thermo Fisher Scientific continues to convert its recent acquisitions, AI and digital initiatives, and reshoring driven CDMO contracts into durable organic growth while keeping margins resilient.
The current valuation implies that Thermo Fisher Scientific shares do not fully reflect the company’s raised 2026 revenue and EPS guidance, its multi year equipment and services backlog, or the earnings contribution expected from recent acquisitions.
See why 6 investors see Thermo Fisher Scientific as 15% undervalued.
Result: Fair Value of $830 (UNDERVALUED)
Still, that bullish Thermo Fisher Scientific story depends on smooth execution around the microbiology divestiture and assumes margin gains are not knocked back by lost scale.
Find out about the key risks to this Thermo Fisher Scientific narrative.
Another Take On Thermo Fisher Scientific’s Valuation
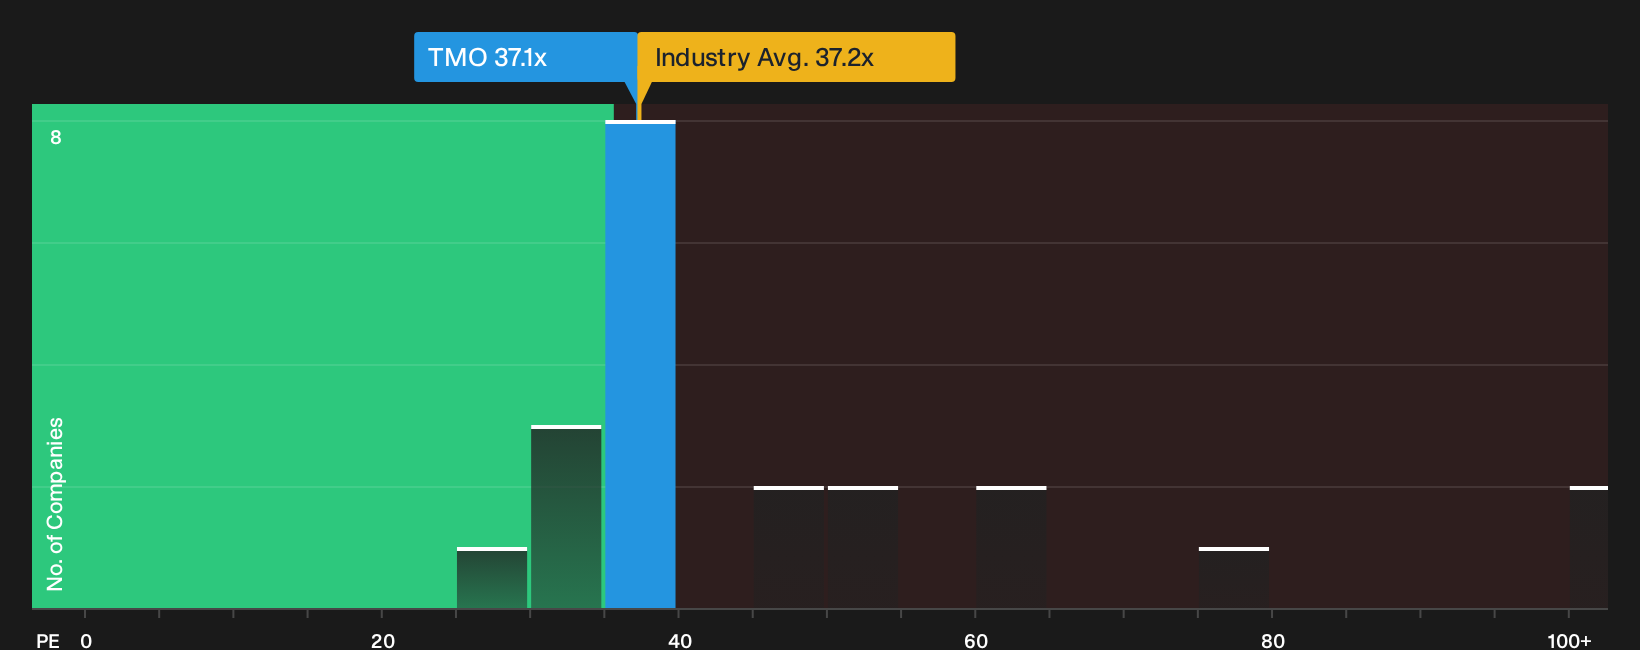
The bullish fair value of $830 leans heavily on analyst forecasts. A simple P/E cross check tells a different story. Thermo Fisher Scientific trades on 37.1x earnings, which is above its own fair ratio of 34.7x, yet roughly in line with the Global Life Sciences average of 37.2x and below the 40x peer group level. That mix hints at a stock already priced for quality, with only a slim margin for forecast disappointment. Which signal do you put more weight on: the upside narrative or the thin valuation cushion?
For a closer look at how those earnings multiples stack up against what the numbers imply, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Thermo Fisher Scientific’s value story so far. Act quickly, review the full data set, and weigh both the upside and the warning flags in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Thermo Fisher Scientific?
Do not stop with Thermo Fisher Scientific. Apply the same disciplined lens across other opportunities so you continue making thoughtful decisions instead of relying on a single stock.
- Prioritize resilience and fill your research list with 30 resilient stocks with low risk scores that have stronger balance sheets and steadier risk profiles.
- Look for mispriced potential and review a focused group of 18 high quality undiscovered gems where fundamentals and market attention may not fully align.
- Seek a steadier income stream by reviewing a curated set of 7 dividend fortresses that offer higher yields supported by underlying cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com