


EN
Is Range Resources (RRC) Fully Valued On Its EQT Deal Or Still Undervalued?
Range Resources (RRC) moved into the spotlight after EQT agreed to acquire the producer in a stock deal valued at about US$13.1b. This has raised fresh questions about what RRC now represents for shareholders.
For context, Range Resources has been on a strong run, with a 30 day share price return of 46.12% and a year to date share price gain of 52.66% building up to the EQT deal. That momentum sits alongside a 1 year total shareholder return of 57.29% and a 5 year total shareholder return of 145.92%. However, the stock did pull back 3.56% on the day of the announcement as investors weighed the takeover terms and recent earnings surprise against future integration and deal risk.
Spot fresh energy ideas trading on similar deal and earnings momentum by scanning our hand picked 30 high quality undervalued stocks now.Range Resources now trades above the average analyst target yet screens at a sizeable discount to one estimate of fair value. Is that a mispricing, or is the market simply pricing in deal and integration risk?
Most Popular Narrative: 15% Overvalued
Range Resources is trading at $53.89 against a widely followed fair value view of about $47.04, so the merger story is being weighed against a valuation that already reflects a premium according to that framework.
Continued capital discipline, combined with a balance sheet at roughly 0.5x leverage and year to date returns of about US$489 million to equity holders through dividends, buybacks and debt reduction, gives Range Resources scope to keep prioritizing free cash flow per share. This can support earnings per share and total shareholder yield if current reinvestment rates are sustained.
See why 13 investors see Range Resources as 15% overvalued.
Result: Fair Value of $47.04 (OVERVALUED)
Still, weaker gas strip pricing and higher storage levels, along with increased insider selling, could pressure the Range Resources story and challenge today’s premium.
Find out about the key risks to this Range Resources narrative.
Another View: Range Resources Through A Different Lens
The first narrative presents Range Resources as 15% overvalued relative to a $47.04 fair value. A second lens tells a different story. Our DCF model, focused on future cash flows, points to a value of $86.65, which would place RRC trading well below that estimate. Which signal do you rely on more: market price or modeled cash flows?
Investors who want to see how those cash flow assumptions are incorporated into the valuation can walk through the SWS DCF model step by step via Look into how the SWS DCF model arrives at its fair value..
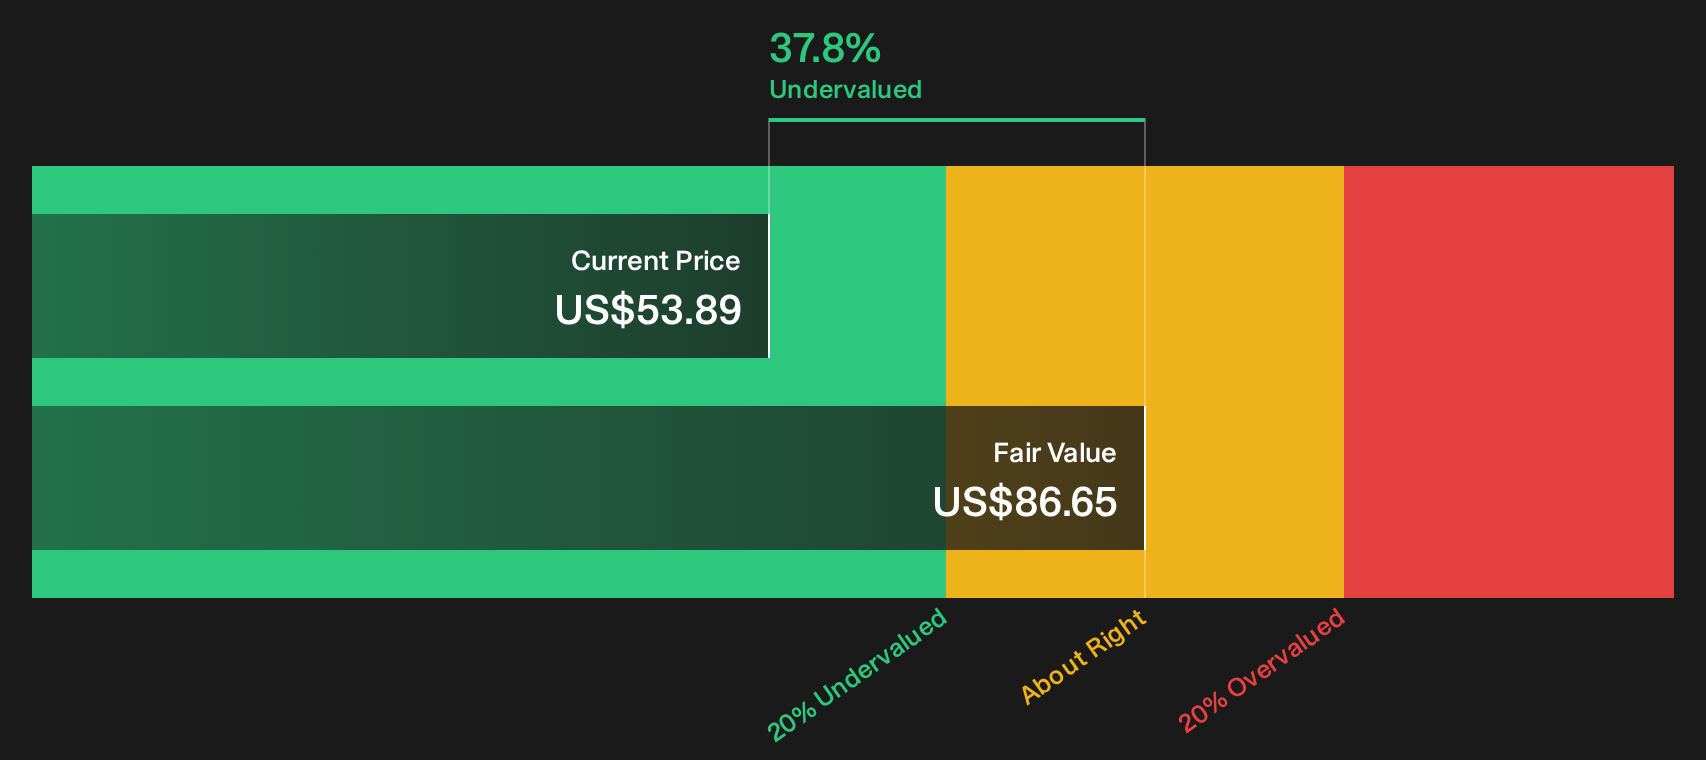
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Range Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment this split on Range Resources, it may be worth testing the numbers yourself and deciding whether the risk reward still works for you. To weigh up the potential upside that has investors optimistic right now, start by reviewing the 2 key rewards.
Looking for more investment ideas beyond Range Resources?
RRC is only one opportunity on your radar. Put the odds in your favor by scanning more companies that match the kind of edge you are hunting for today.
- Expand your opportunity set with a curated pool of potential bargains using the 18 high quality undiscovered gems.
- Strengthen your downside protection by focusing on businesses with healthier finances through the list of solid balance sheet and fundamentals (23 results).
- Target steady cash returns by zeroing in on companies highlighted in the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com