


EN
Terreno Realty (TRNO) Buys Queens Industrial Site, Is The Stock Fully Priced?
Terreno Realty (TRNO) just picked up a vacant industrial distribution building in Maspeth, Queens for about $13.9 million, and agreed to end a 121,000 square foot lease in Tukwila, Washington early.
Recent moves like the Queens purchase fit into a year in which Terreno Realty’s share price has risen 11.35% year to date. Its 1-year total shareholder return of 16.12% and 3-year total shareholder return of 31.65% point to momentum that investors are still willing to back.
Scan beyond Terreno Realty and see how other industrial-focused real estate plays are setting up right now with our hand picked list of solid balance sheet and fundamentals (23 results)
The Queens deal and recent lease moves suggest that Terreno Realty is still reshaping its portfolio. The key question is whether the stock already reflects that progress, or whether the valuation still leaves meaningful upside on the table.
Preferred P/E of 18.5x: Is it justified for Terreno Realty?
On traditional valuation math, Terreno Realty trades on a P/E of 18.5x, which puts a premium on its last close at $65.72 compared with much of the Industrial REIT space.
The P/E ratio compares the current share price to earnings per share. For a real estate owner such as Terreno Realty, it signals how much investors are willing to pay for each dollar of profit, which ties directly to expectations around rental income resilience, portfolio quality and future cash generation.
TRNO is described as expensive versus the global Industrial REITs average P/E of 14.6x, so the market is paying materially more for each dollar of its earnings than it does for the sector overall. At the same time, that 18.5x is framed as good value relative to a peer average of 28.2x and an estimated fair P/E of 25.4x. This points to a valuation that could move higher if sentiment shifts closer to those benchmarks.
Explore the SWS fair ratio for Terreno Realty.
Result: Price-to-earnings of 18.5x (ABOUT RIGHT)
Still, the narrative can crack if Terreno Realty’s early lease terminations reduce near term earnings or if industrial property values soften and compress that P/E premium.
Find out about the key risks to this Terreno Realty narrative.
Another view on Terreno Realty’s value
A different lens gives a slightly cooler reading. The SWS DCF model puts Terreno Realty’s future cash flow value at about $67 a share, only around 2% above the current $65.72 price. That suggests less of a clear bargain and more of a tight margin for error. How comfortable are you paying up when the cushion is this thin?
Look into how the SWS DCF model arrives at its fair value.
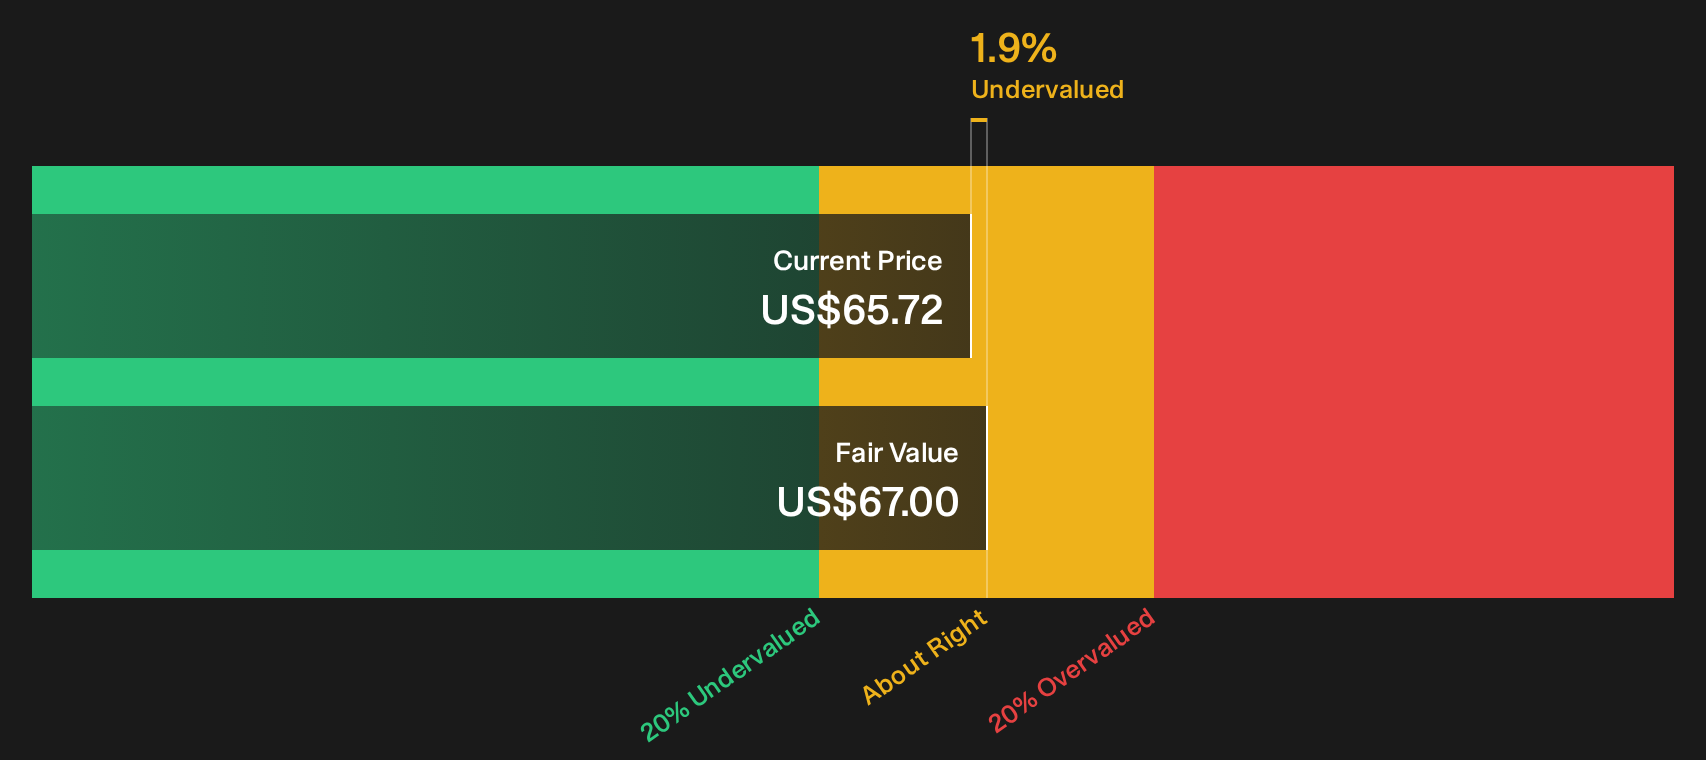
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Terreno Realty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a balanced setup for Terreno Realty? If you care about both potential upside and what could go wrong, go straight to the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Terreno Realty?
If Terreno Realty has your attention, do not stop here. Broaden your watchlist, test new angles and let fresh ideas compete for your capital.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive entry points through the 30 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on higher yielding payers screened as 7 dividend fortresses.
- Dial down portfolio risk by focusing on businesses highlighted in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com