


EN
3 Stocks That Might Be Trading Below Their Estimated Value
The United States market has remained flat over the past week but has seen a 10% increase over the past year, with earnings forecasted to grow by 17% annually. In this environment, identifying stocks that are potentially trading below their estimated value can offer opportunities for investors seeking to capitalize on future growth potential.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $66.23 | $121.39 | 45.4% |
| Provident Financial Services (PFS) | $23.17 | $42.55 | 45.5% |
| OP Bancorp (OPBK) | $15.44 | $29.95 | 48.4% |
| Noah Holdings (NOAH) | $6.89 | $13.25 | 48% |
| Meta Platforms (META) | $624.52 | $1161.95 | 46.3% |
| Halliburton (HAL) | $35.90 | $66.38 | 45.9% |
| Civista Bancshares (CIVB) | $28.47 | $56.56 | 49.7% |
| Atlantic Union Bankshares (AUB) | $39.73 | $78.92 | 49.7% |
| Associated Banc-Corp (ASB) | $30.53 | $57.52 | 46.9% |
| Alphabet (GOOGL) | $283.82 | $522.00 | 45.6% |
Let's take a closer look at a couple of our picks from the screened companies.
Broadcom (AVGO)
Overview: Broadcom Inc. designs, develops, and supplies a range of semiconductor devices and infrastructure software solutions internationally, with a market cap of approximately $1.68 trillion.
Operations: The company's revenue is primarily derived from its Semiconductor Solutions segment, which generated $59.44 billion, and its Infrastructure Software segment, which contributed $29.67 billion.
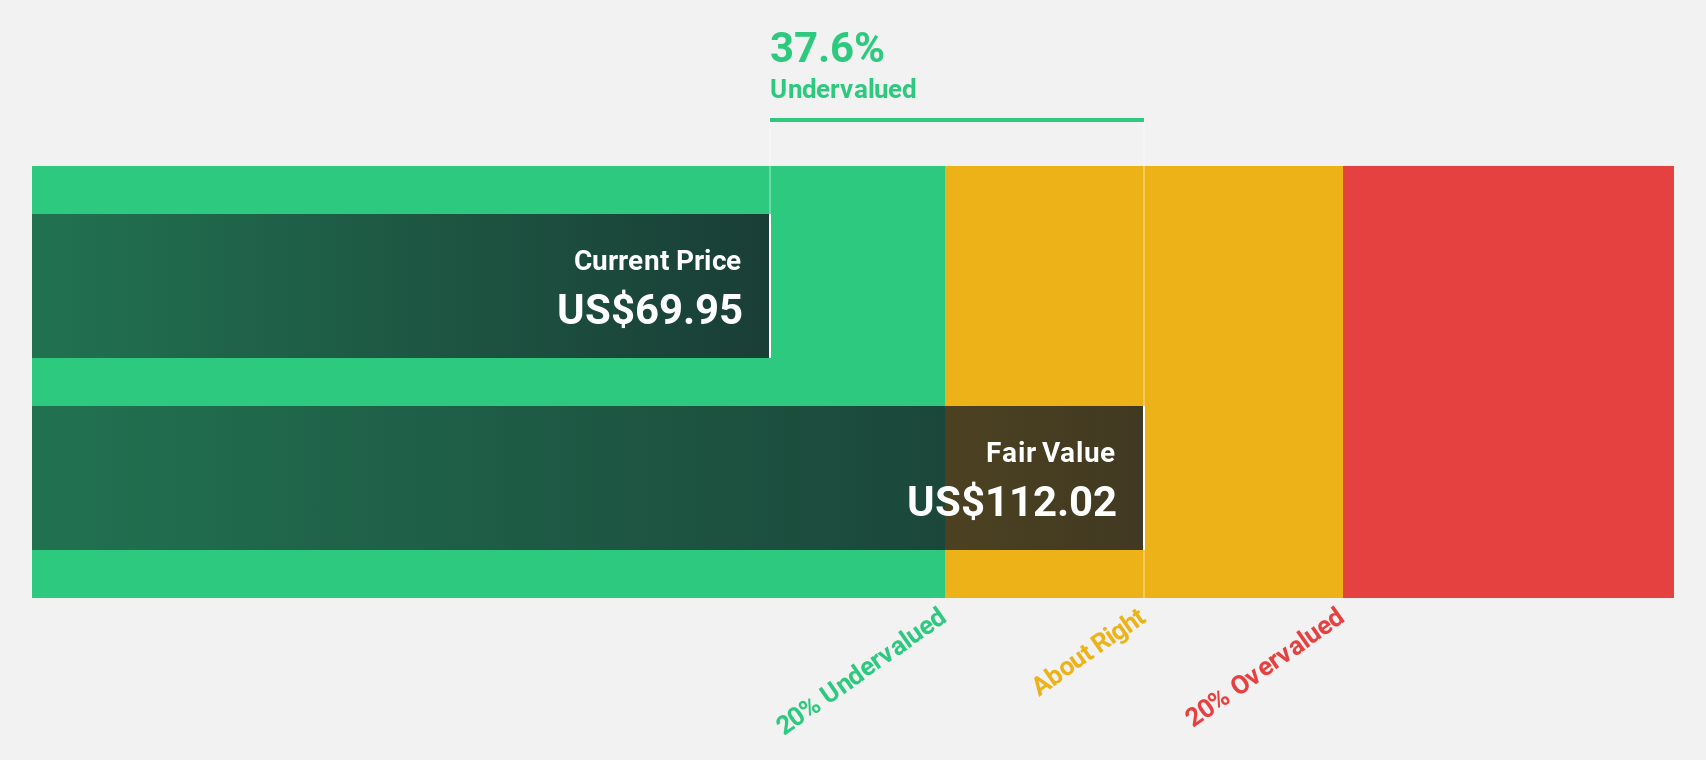
Estimated Discount To Fair Value: 26.5%
Broadcom Inc. appears undervalued based on cash flows, trading at $345, below the estimated future cash flow value of $469.1. The company has demonstrated substantial earnings growth, with a recent 104.1% increase in net income year-over-year and is expected to maintain significant annual profit growth over the next three years. Recent client announcements and product innovations further bolster its position in digital infrastructure optimization and AI readiness, potentially enhancing its long-term financial performance.
- Our expertly prepared growth report on Broadcom implies its future financial outlook may be stronger than recent results.
- Dive into the specifics of Broadcom here with our thorough financial health report.
L3Harris Technologies (LHX)
Overview: L3Harris Technologies, Inc. delivers mission-critical solutions to government and commercial clients globally, with a market cap of approximately $51.85 billion.
Operations: The company's revenue segments include Integrated Mission Systems at $7.18 billion, Space and Airborne Systems at $6.40 billion, Communication Systems at $4.29 billion, and Aviation Systems at $3.39 billion.
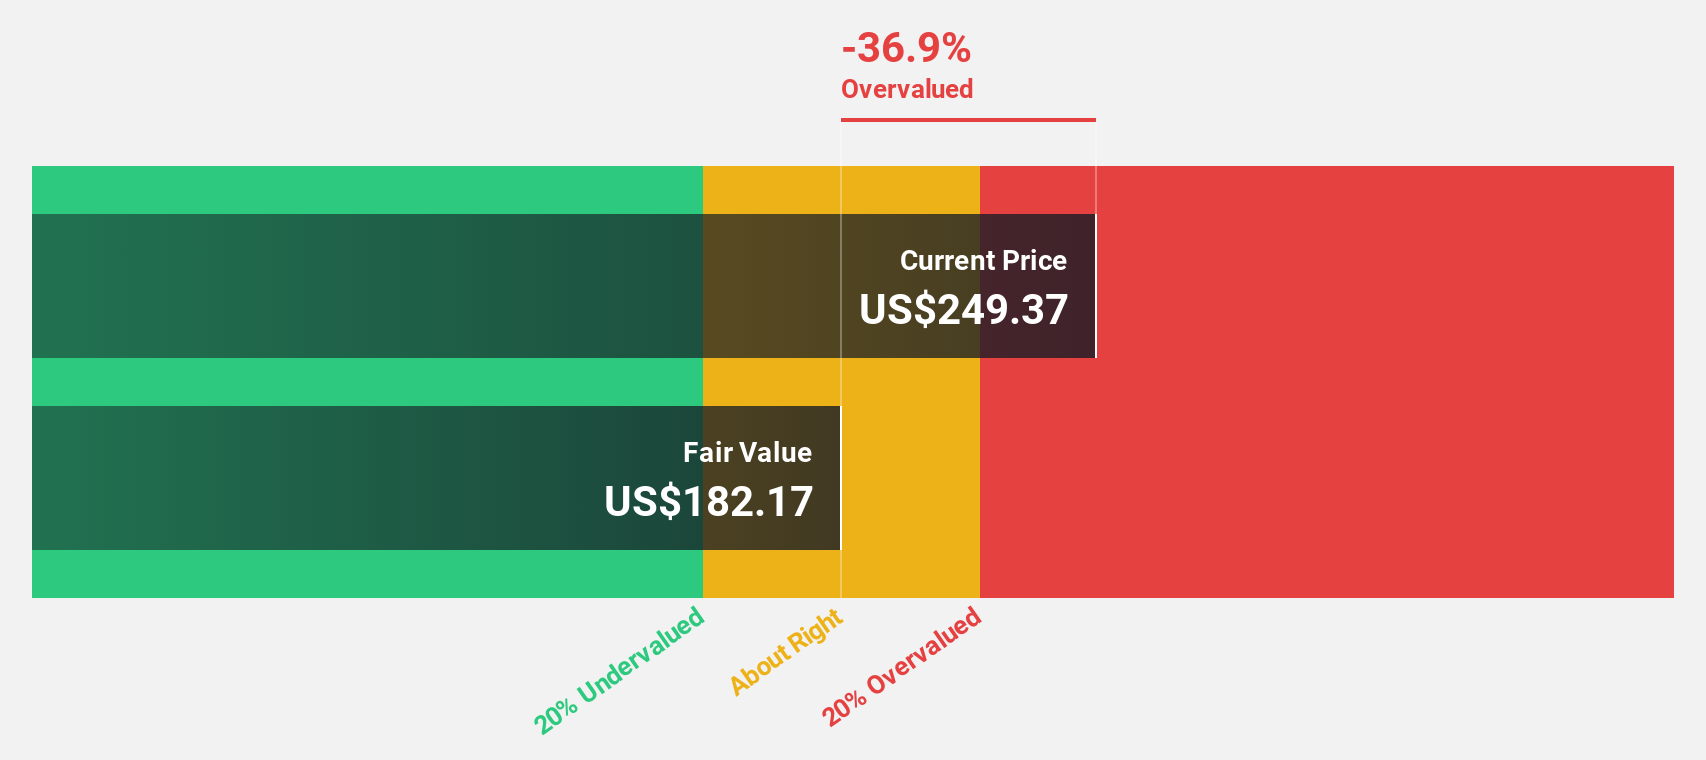
Estimated Discount To Fair Value: 34.3%
L3Harris Technologies is trading at $278.43, significantly below its estimated future cash flow value of $423.65, suggesting it may be undervalued based on cash flows. The company reported strong financial results for Q3 2026, with sales reaching US$6.06 billion and net income of US$632 million, reflecting substantial year-over-year growth. Despite a forecasted earnings growth rate slower than the market average, L3Harris' strategic expansions and raised earnings guidance for 2026 support its potential for long-term value appreciation.
- Insights from our recent growth report point to a promising forecast for L3Harris Technologies' business outlook.
- Click to explore a detailed breakdown of our findings in L3Harris Technologies' balance sheet health report.
Metropolitan Bank Holding (MCB)
Overview: Metropolitan Bank Holding Corp. is the bank holding company for Metropolitan Commercial Bank, offering a variety of business, commercial, and retail banking products and services with a market cap of $1.19 billion.
Operations: Metropolitan Commercial Bank generates its revenue primarily from its banking segment, which amounted to $351.51 million.
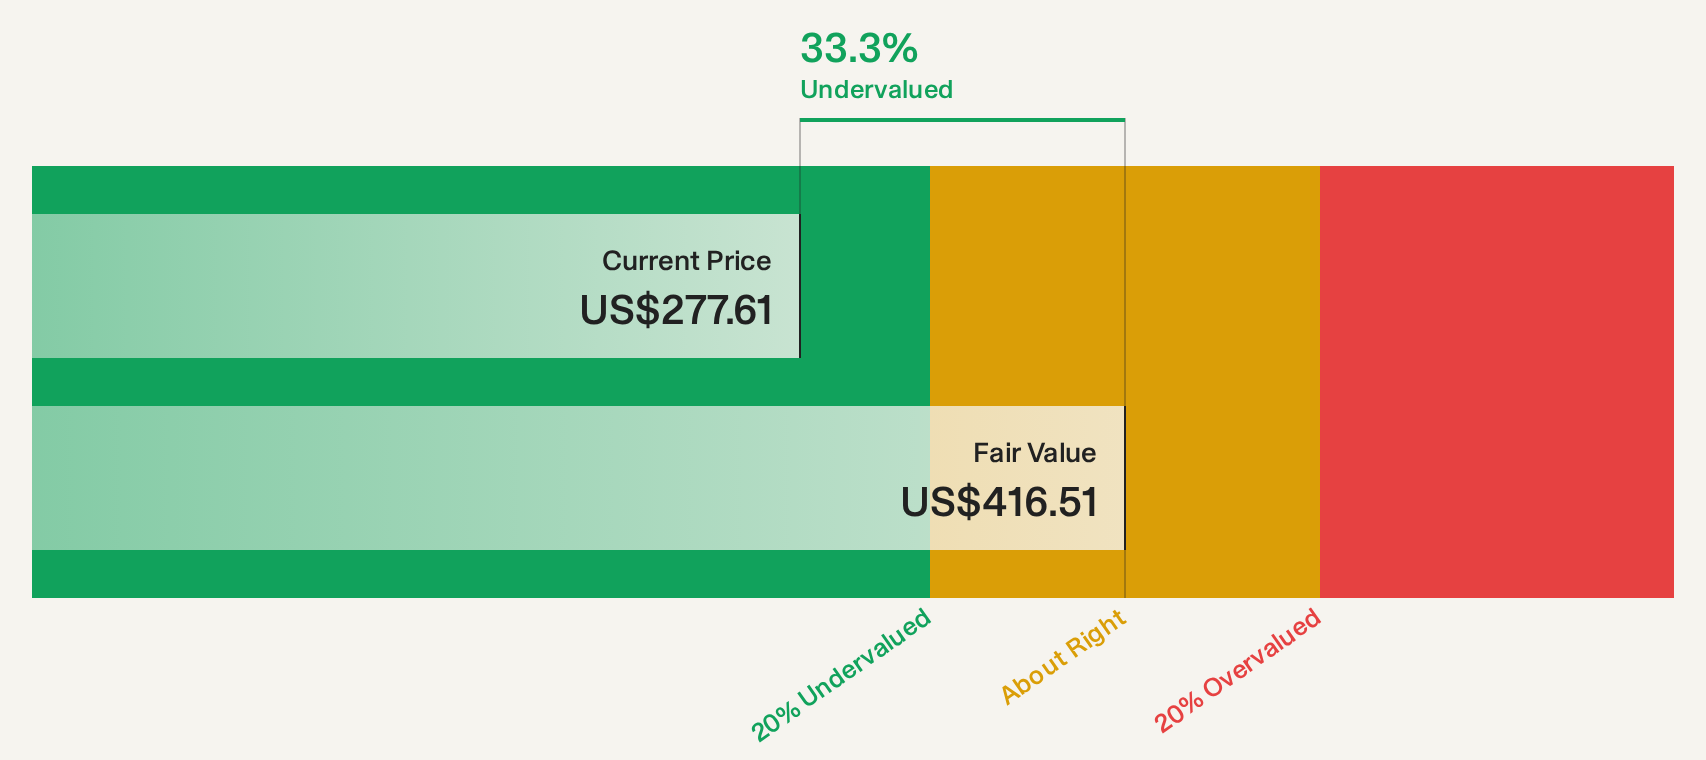
Estimated Discount To Fair Value: 35.4%
Metropolitan Bank Holding is trading at $96.43, significantly below its estimated future cash flow value of $149.33, highlighting potential undervaluation based on cash flows. Recent financial performance shows robust growth, with Q3 2026 net income reaching $32.44 million from $7.12 million a year ago and earnings per share improving substantially. However, insider selling and past shareholder dilution may concern some investors despite the company's solid earnings trajectory and strategic buyback completion of 107,553 shares for $10 million.
- In light of our recent growth report, it seems possible that Metropolitan Bank Holding's financial performance will exceed current levels.
- Unlock comprehensive insights into our analysis of Metropolitan Bank Holding stock in this financial health report.
Taking Advantage
- Unlock more gems! Our Undervalued US Stocks Based On Cash Flows screener has unearthed 79 more companies for you to explore.Click here to unveil our expertly curated list of 82 Undervalued US Stocks Based On Cash Flows.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com