


EN
AerCap (AER) Stock Still Looks Undervalued Following Record Q3 Results
AerCap Holdings has delivered a powerful run in recent years, and the latest records on the earnings front keep attention firmly on what investors are paying for those profits. With the stock now around the US$159.71 mark, the key issue is whether that valuation is still grounded in the strength of its earnings profile.
- Over the past 3 years the share price has produced a very large 156.5% return, which puts real pressure on the question of how much of AerCap's earnings power is already reflected in today's valuation.
- Recent record earnings and higher profit expectations give the business more room to fund fleet growth and share buybacks, which can support the case for a richer earnings stream to underpin the current price.
- Your read on AerCap Holdings is one view; the desks covering it have another. See what analysts think AerCap Holdings's shares could be worth.
The issue now is whether AerCap's current share price is justified by its earnings when lined up against a Fair Ratio benchmark.
If record Q3 earnings and AerCap Holdings' 156.5% three year return have you thinking about valuation grounded in profits, compare that theme across 30 high quality undervalued stocks.
Is AerCap Holdings a Bargain on Earnings?
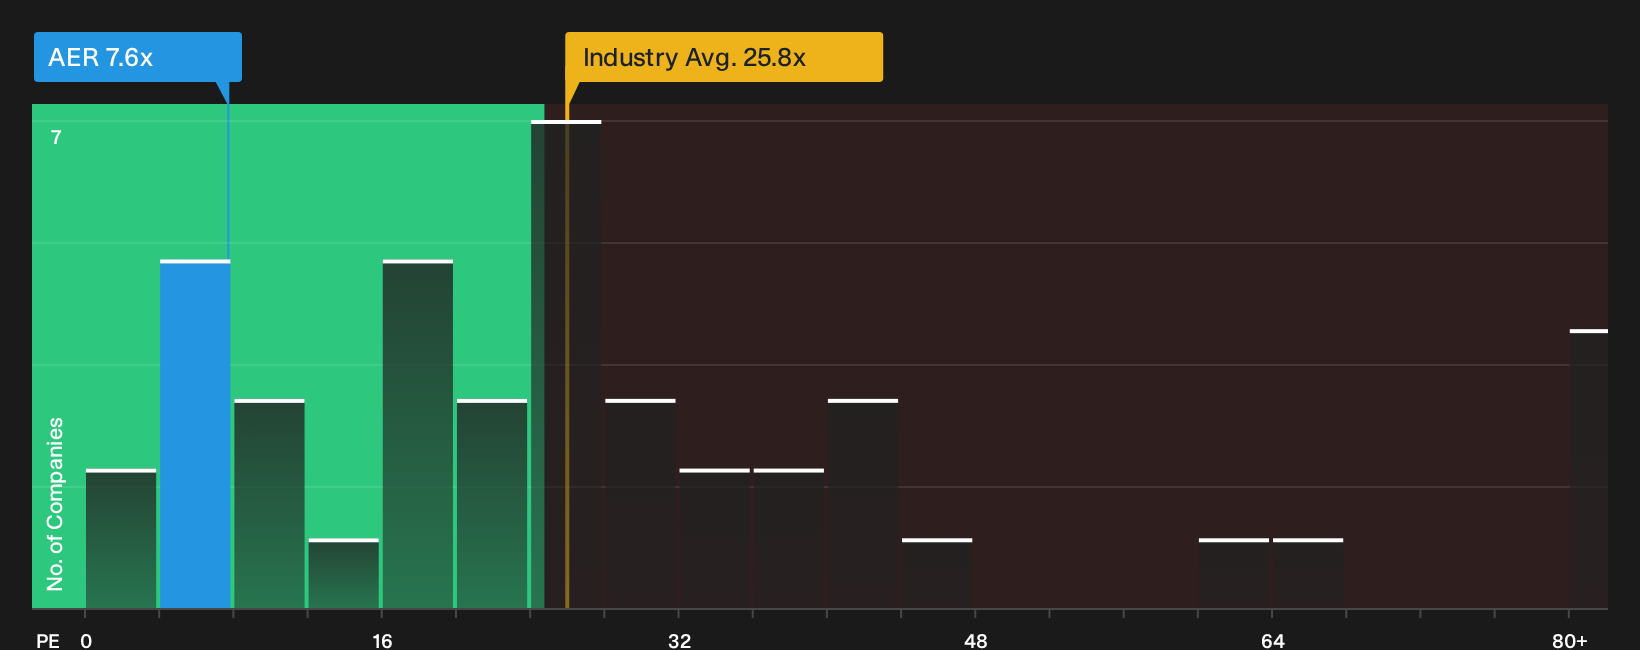
The P/E lens suits AerCap Holdings because earnings per share sit at the center of how investors frame this aircraft lessor. On this measure, the shares trade on a P/E of 7.6x, compared with about 25.8x for the wider Trade Distributors group and roughly 25.7x across direct peers. That is a wide gap for a business that uses profit as its main yardstick, and it places a lot of emphasis on how durable investors judge those earnings to be over time.
The Fair Ratio model, which looks at AerCap Holdings through its own mix of growth profile, margins, size and risk, points to a higher P/E than the market is currently paying, so the stock screens as undervalued on this framework. Because record Q3 2026 results and a higher full year earnings outlook have already reset expectations upward, that discount suggests investors are still applying a cautious filter to the current profit run rather than pricing it on the same terms as sector peers. Explore the numbers behind AerCap Holdings's P/E valuation.
The AerCap Holdings Narrative: What Would Justify Today's Price?
Narratives pick up where AerCap Holdings' valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to hold for the shares to be worth meaningfully more or less than today. Each scenario anchors a fair value to a specific mix of potential catalysts and risks so you can watch over time which version of the story seems closest to reality on Simply Wall St's Community page.
A fresh, number driven Narrative on AerCap Holdings' valuation gives you a clear record of what you expect its earnings power, capital returns and fleet decisions to deliver from here. With record recent profitability, higher guidance, ongoing buybacks and new lease commitments all in play, writing that view down now makes it easier to test those assumptions against future results and any shifts in aviation demand or risk.
Share your own Narrative for AerCap Holdings and set out the assumptions behind your valuation.
AerCap Holdings’ valuation still leaves one crucial piece of the puzzle
The figures only tell part of the story, because the people steering AerCap Holdings and the way their pay is structured can heavily influence how that earnings engine is run over time. See who runs AerCap Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com