


EN
Ultra Clean Holdings (UCTT) Stock Looks Overvalued Despite Its 119% Run
Ultra Clean Holdings has delivered a sharp swing in returns over the past few years, which raises a simple question for you as a shareholder or potential buyer. Is the current share price at about US$54.70 adequately explained by the earnings power the business is producing today.
- Over the past 3 years, Ultra Clean Holdings has returned about 119.3%, which places considerable focus on whether recent earnings can support that kind of share price reset.
- Fresh headlines around record revenue, higher profit and management highlighting exposure to AI related demand can influence how durable investors expect Ultra Clean Holdings' margins and earnings to be.
- There is a second opinion on Ultra Clean Holdings worth weighing. See what analysts think Ultra Clean Holdings's shares could be worth.
The stock's next move may depend on whether Ultra Clean Holdings' current earnings are strong enough to justify where the shares trade today.
If you want more ideas beyond Ultra Clean Holdings while you assess this earnings story, a focused stock screen built around 54 AI infrastructure stocks may be useful.
Has Ultra Clean Holdings Run Too Far on Earnings?
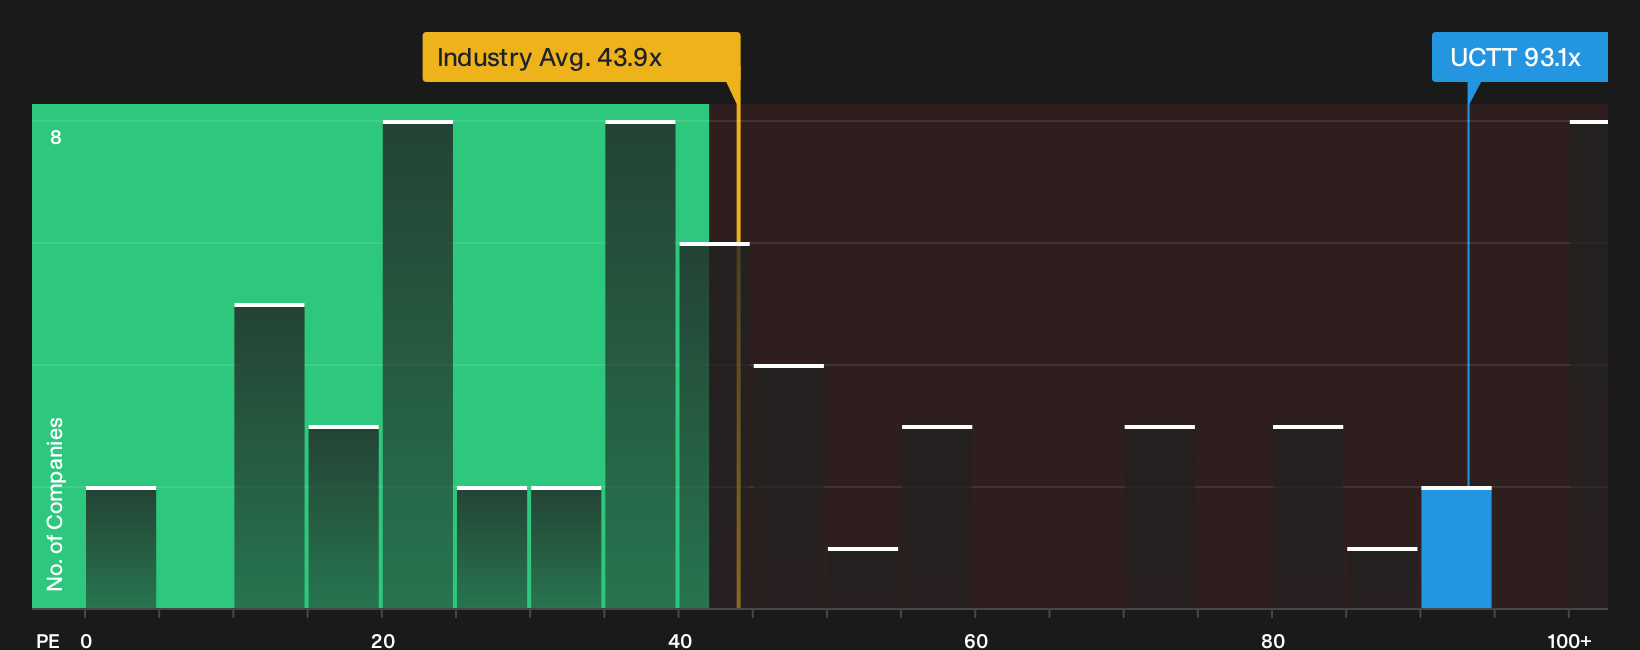
The P/E ratio fits Ultra Clean Holdings because recent headlines and guidance focus squarely on earnings power. On this lens, the stock trades on about 93.1x, which is higher than both the wider semiconductor industry on roughly 43.9x and the peer group average around 86.4x. That places a lot of weight on how durable you think current profitability is, rather than just near term AI enthusiasm.
Using a tailored fair multiple that blends the company’s growth profile, margins, sector context and risk, the current P/E screens as overvalued. Despite the record Q3 2026 results and upbeat Q4 outlook, the valuation already assigns a rich price for each dollar of earnings relative to what that framework would suggest. If you own or are considering Ultra Clean Holdings, the key judgement is whether future results can keep matching what this P/E is currently implying. Explore the numbers behind Ultra Clean Holdings's P/E valuation.
The Ultra Clean Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ultra Clean Holdings pick up where this valuation puzzle leaves off, by spelling out the specific growth, margin and earnings paths that would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. Instead of one blunt output from a ratio or model, Narratives describe the future that number assumes so you can watch real results and see whether that story is staying intact or starting to crack.
One of the top community narratives on Ultra Clean Holdings: 59% undervalued
"The main thing that has to go right is Ultra Clean Holdings successfully scaling its global manufacturing footprint and UCT 3.0 co-innovation model..."
Discover why this Narrative puts Ultra Clean Holdings at 59% undervalued.
Ultra Clean Holdings: why the share price is only half the story
Before you lean too heavily on Ultra Clean Holdings' current valuation, it is worth knowing that Simply Wall St's broader checks have flagged potential concerns that deserve a closer look. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com