


EN
Alliance Resource Partners (ARLP) Stock Still Looks Like A Bargain After Earnings
Alliance Resource Partners has delivered a powerful run in recent years, and the latest earnings news keeps attention firmly on its profit engine. With that backdrop, the live question for investors is whether the current price fairly reflects what the partnership is earning today.
- Over the past 5 years the stock has returned about 281.2%, which puts real pressure on the valuation case to be grounded in the partnership’s earnings power rather than just the share price chart.
- Recent reports highlighting higher revenue, stronger net income and ongoing cash distributions suggest the coal and oil and gas royalty operations can influence expectations for how durable Alliance Resource Partners' earnings base may be.
- The analysts covering Alliance Resource Partners have run their own numbers. See what analysts think Alliance Resource Partners's shares could be worth.
The issue now is whether Alliance Resource Partners' current market value is justified by the level and quality of the earnings that support it.
If you want to test the same earnings driven valuation question beyond Alliance Resource Partners, scan a wider field of energy names using 30 high quality undervalued stocks
Is Alliance Resource Partners a Bargain on Earnings?
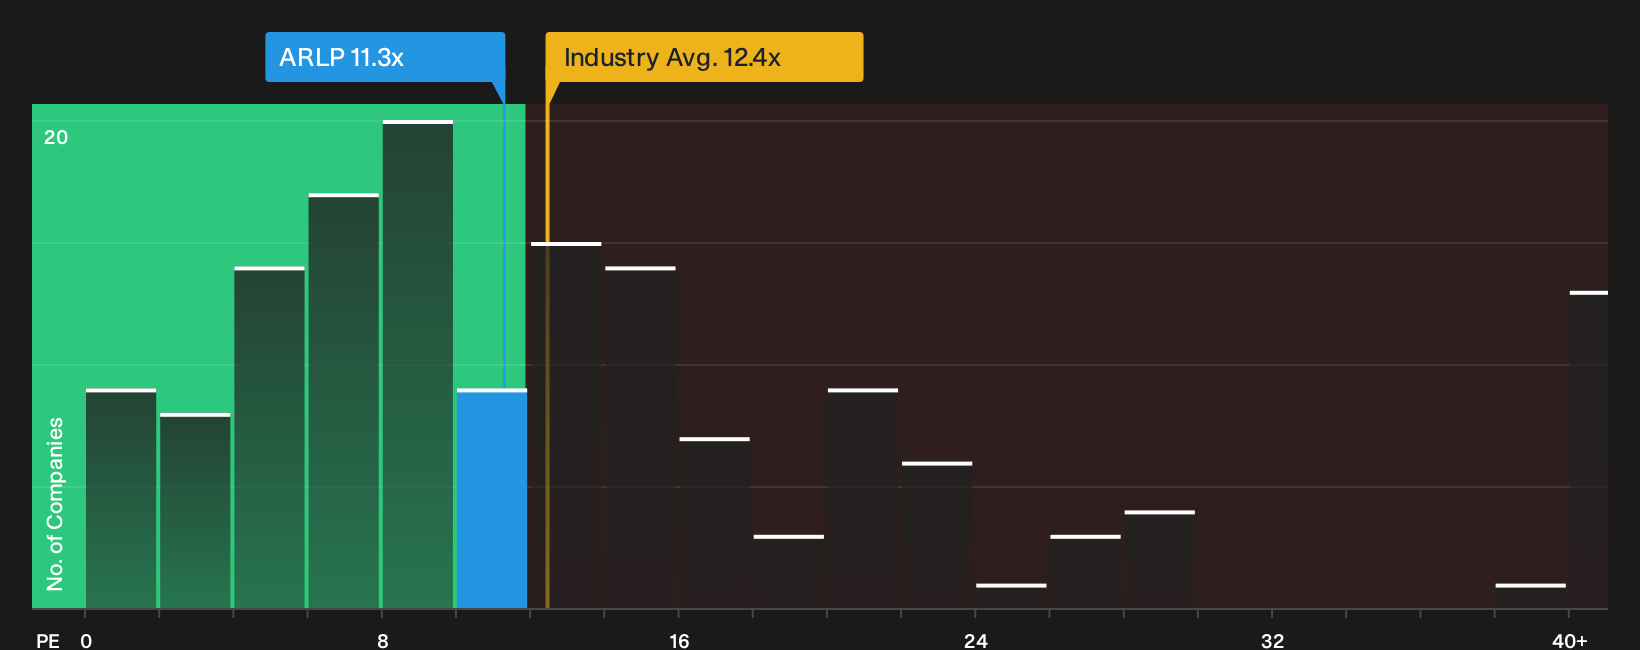
A P/E ratio works well for Alliance Resource Partners because investors anchor on the partnership’s cash generation and reported earnings power. On this measure, the stock trades at about 11.3x earnings, which is lower than the wider Oil and Gas group at roughly 12.4x and well below the broader peer set sitting near 30.0x. The model’s fair multiple, which blends in factors like profitability, scale and sector risk, sits above the current level, so the units screen as undervalued on this specific yardstick.
Because the latest quarterly release flagged strong revenue and net income alongside the updated guidance, the current discount suggests the market is still pricing Alliance Resource Partners more cautiously than those earnings might imply. That gap leaves investors weighing how sustainable the coal and oil and gas royalty cash flows look relative to sector peers, and whether the present earnings yield compensates for the risks tied to this type of asset base. Explore the numbers behind Alliance Resource Partners's P/E valuation.
The Alliance Resource Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Alliance Resource Partners leaves off, since they spell out what growth, margin and earnings paths would need to play out for the units to look meaningfully cheaper or more expensive than today’s price based on explicit assumptions. Each scenario ties its number to a concrete view of how Alliance Resource Partners' prospects and risks evolve over time, giving you something you can come back to as fresh information appears.
One of the top community narratives on Alliance Resource Partners: 14% undervalued
"Expanding oil and gas royalties, including over US$1b invested in minerals interests and the increased economic interest in AllDale III and IV to about 61%, positions Alliance Resource Partners for higher royalty volumes and a growing contribution to revenue and EBITDA from a business that has recently reported record quarterly royalty results…"
Discover why this Narrative puts Alliance Resource Partners at 14% undervalued.
One more piece of the Alliance Resource Partners story worth checking
Alliance Resource Partners has valuation talking points on its side, yet the research checks also flag specific areas of concern that deserve a closer look before you get too comfortable. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com