


EN
Ingersoll Rand (IR) Lifts 2026 Revenue Guidance, Is The Stock Fully Valued?
What Ingersoll Rand’s latest earnings tell you
Ingersoll Rand (IR) just posted fresh third quarter numbers that put both sales and profits in focus, and paired those figures with an updated full year revenue outlook that investors are now dissecting.
The headline is simple. New earnings data and revised guidance give you a clearer snapshot of how this industrial supplier is executing heading into the final stretch of 2026.
Ingersoll Rand’s earnings update landed alongside a sharp 6.04% 1 day share price return to US$80.01, capping a 7.96% 7 day share price gain that contrasts with a 4.04% decline over 90 days and a more measured 40.82% 5 year total shareholder return. Together, these figures point to renewed momentum building after a softer stretch.
Scan how Ingersoll Rand’s earnings reset compares with peers by running through our curated list of 30 high quality undervalued stocks, which pairs resilient cash flows with stronger balance sheets.
After a sharp move to US$80.01 on the back of stronger earnings, Ingersoll Rand now poses a simple question for you as an investor: Does the current price still leave enough upside to justify fresh risk?
Most Popular Narrative: 15% Undervalued
The most followed valuation view puts Ingersoll Rand’s fair value at about $94.10 a share, comfortably above the recent $80.01 close. This frames the current debate less around survival and more around how much quality you think you are paying for.
The current valuation implies the market is not fully crediting Ingersoll Rand for its mix of mid 40%+ gross margins, targeted 30% ITS and mid 30s PST EBITDA margins, expanding recurring revenue base, and balance sheet capacity for further bolt-on deals. This underpins the view that the stock is considered undervalued and that sentiment is positive.
See why 14 investors see Ingersoll Rand as 15% undervalued.
Result: Fair Value of $94.10 (UNDERVALUED)
Still, the Ingersoll Rand story can break if acquisition missteps trigger fresh write downs or if weaker China and EMEA conditions continue to keep margins under pressure.
Find out about the key risks to this Ingersoll Rand narrative.
Another View: What Ingersoll Rand’s P/E Is Telling You
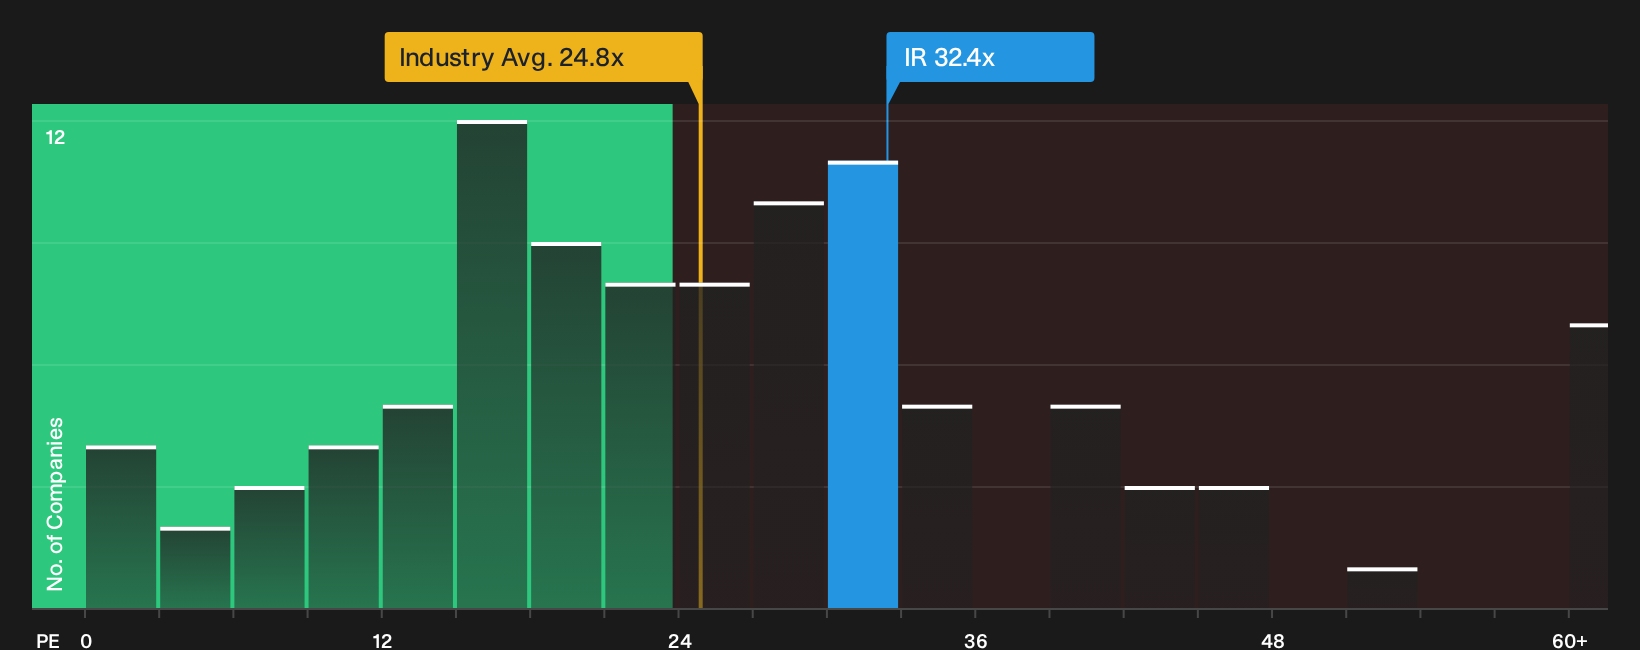
That US$94.10 fair value comes from forward earnings assumptions. Look at the simple P/E picture and the tone changes. Ingersoll Rand trades on 32.4x earnings, compared with 24.4x for the US Machinery industry, 23.6x for peers, and a fair ratio of 26.5x.
Those gaps point to investors already paying a clear premium today, which leaves less room if sentiment or forecasts cool from here. The question is whether you think Ingersoll Rand has the staying power to keep justifying that richer multiple or if you would rather wait for the price to do more of the work.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Ingersoll Rand in this piece leans optimistic, but the decision is still yours. Act while the details are fresh and pressure test the positive angles by reviewing the 3 key rewards.
Looking for more investment ideas beyond Ingersoll Rand?
If Ingersoll Rand has sharpened your focus, do not stop here. Broaden your watchlist with fresh opportunities that match the kind of risk and return profile you want.
- Target resilient performers by scanning a 30 resilient stocks with low risk scores that filters for stocks with more measured risk scores and sturdier fundamentals than the broader market.
- Hunt for potential value opportunities through a 30 high quality undervalued stocks that blends solid cash generation with balance sheets designed to handle tougher conditions.
- Spot early-stage potential by reviewing a 9 elite penny stocks with strong financials focused on smaller companies with stronger financial foundations than typical micro caps.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com