


EN
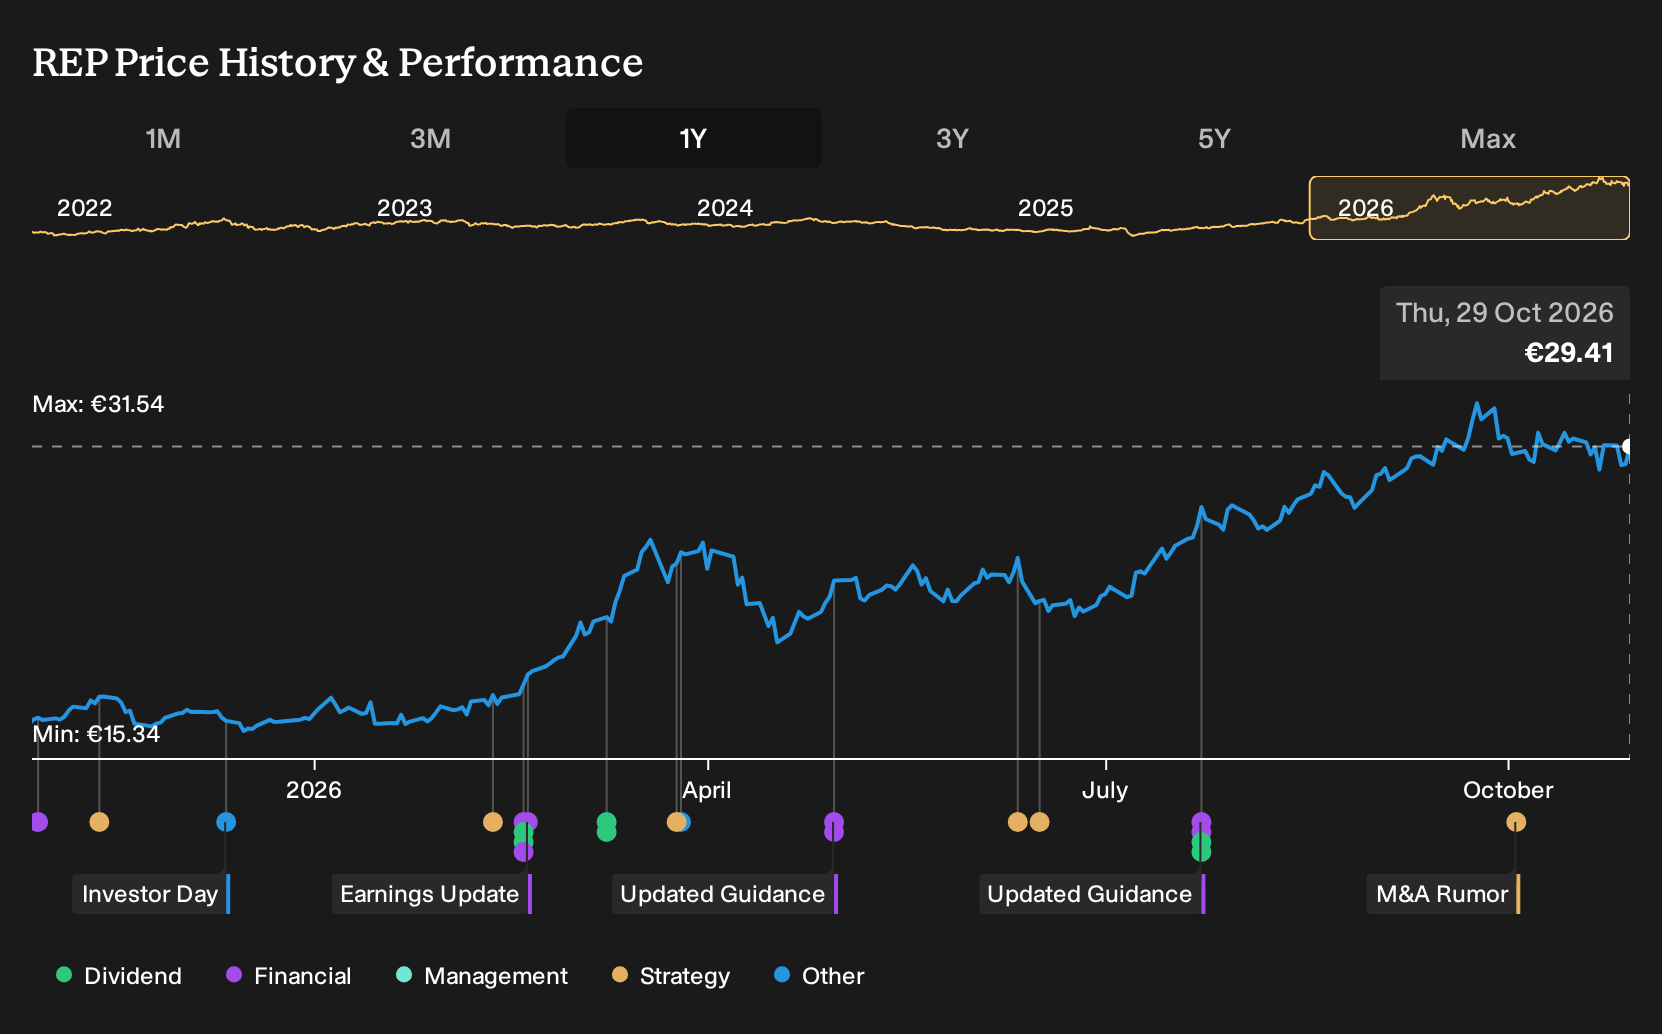
Does Earnings Beat Change The Bull Case For Repsol Stock (BME:REP)?
- Repsol reported third quarter 2026 sales of €19,923 million and net income of €2,805 million, with earnings per share of €2.56 from continuing operations.
- The company paired these results with a new €950 million buyback of up to 50,000,000 shares to be redeemed under a previously approved capital reduction.
- This article examines how Repsol's investment narrative is shaped by its third quarter earnings and the newly announced buyback program.
Scan how Repsol's buyback and earnings story compares to other potential opportunities by reviewing the hand picked 196 high quality undervalued stocks that may be priced below their underlying fundamentals.
Repsol Investment Narrative Recap
To own Repsol, investors need to be comfortable with a multi energy group that still leans heavily on hydrocarbons while funding a shift toward low carbon projects such as renewables, biofuels and hydrogen. The latest €19,923 million in quarterly sales and €2,805 million in net income keep that narrative focused on execution, not reinvention.
In the short term, the key catalyst remains how efficiently Repsol converts its large upstream and refining footprint into cash that can support investment and shareholder returns. The biggest risk stays the same: rising regulatory and tax pressure on fossil activities and high capital spending needs, so this earnings beat alone does not change the core risk profile.
The new €950 million buyback of up to 50,000,000 shares is the announcement that most directly ties into this earnings release. Repurchasing stock to redeem against an already approved capital reduction links recent profit delivery with capital management, and it is supported by the strong nine month numbers that show €53,620 million of sales and €5,006 million of net income.
For shareholders, this plan makes execution on cash generation and project delivery even more important, because buybacks add another claim on future cash alongside capex and dividends. The main operational swing factors remain Repsol's spending on upstream projects, the performance of refining and chemicals, and exposure to regulatory changes in key regions such as Spain, Libya and Venezuela.
Repsol's narrative projects €60.0b revenue and €3.4b earnings by 2029. This assumes 3.4% yearly revenue growth and flat earnings compared with current earnings of €3.4b.
Uncover why Repsol's fair value indicates that it is in line with its current price.
Exploring Other Perspectives
One alternate angle you may want to test against this buyback and Q3 beat is the more pessimistic view on future earnings. The lowest analysts were pencilling in revenue of about €42.6b and earnings of €2.0b by 2029, well below the €60.0b and €3.4b consensus path. This fresh information could eventually shift those expectations.
Explore 6 other Repsol fair value estimates, including one that suggests as much as 23% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Repsol research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Repsol. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Repsol's overall financial health at a glance.
Looking for more Repsol sized investment ideas?
If Repsol has sharpened your sense of what you want from an investment, use that momentum to scan a broader watchlist and pressure test your thesis against other businesses with different risk and reward profiles.
- For investors who care most about valuation support and business quality, compare this story with a curated group of financially resilient opportunities through the 196 high quality undervalued stocks.
- If capital preservation and a smoother ride matter to you, consider balancing Repsol exposure by reviewing a 225 resilient stocks with low risk scores that scores well on financial strength and lower volatility.
- When you want potential upside without stretching balance sheets, expand your search to a 607 high quality undiscovered gems that pairs solid fundamentals with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com