


EN
On Holding (ONON) Could Be 24% Undervalued Before Q3 And Mbappé China Risk
Mbappé fallout and Q3 results put On Holding under the spotlight
On Holding (ONON) heads into its early November third quarter update with two storylines colliding. Investors are weighing fresh financial details against brand risk from Kylian Mbappé’s lost Chinese sponsorships.
Recent trading reflects that tension. The share price is at US$32.80, with a 1-month share price return of 11% but a year to date share price return that is down 30.14%. The 1-year total shareholder return has declined 11.9% and the 3-year total shareholder return is up 18.93%, suggesting long term holders have seen gains even as shorter term momentum has faded ahead of Q3 and the Mbappé headlines.
Scan how other high-growth consumer brands are priced and positioned right now by reviewing our curated 30 high quality undervalued stocks alongside On Holding as this Mbappé story plays out.
Bulls see On Holding as a growth story on sale after the recent share price slide, while bears focus on brand risk and execution. Which narrative fits the valuation math that follows?
Most Popular Narrative: 24% Undervalued
On Holding's most followed valuation narrative points to a fair value of $43.27 compared with the last close at $32.80. The story turns on whether the business can earn into that gap using its premium pricing and direct to consumer model.
The ability to launch and scale new product franchises across running, tennis, trail, lifestyle and fast growing apparel now extends into golf and planned football products, supported by a large patent portfolio and R&D platforms such as LightSpray, which can widen average revenue per customer and support gross margin through differentiated product.
See why 124 investors see On Holding as 24% undervalued.
Based on that framework, the fair value estimate of $43.27 uses an 8.47% discount rate and assumes earnings growth and margins that justify a future P/E of roughly 24x. The implied 24.2% discount to this narrative fair value leaves the Q3 print and the Mbappé fallout as key tests of whether the premium brand thesis still holds.
Result: Fair Value of $43.27 (UNDERVALUED)
Still, the On Holding narrative can break if premium pricing starts to hit demand, or if heavy DTC and store investment drags on profitability.
Find out about the key risks to this On Holding narrative.
Another View: On Holding Looks Expensive On Simple Comparisons
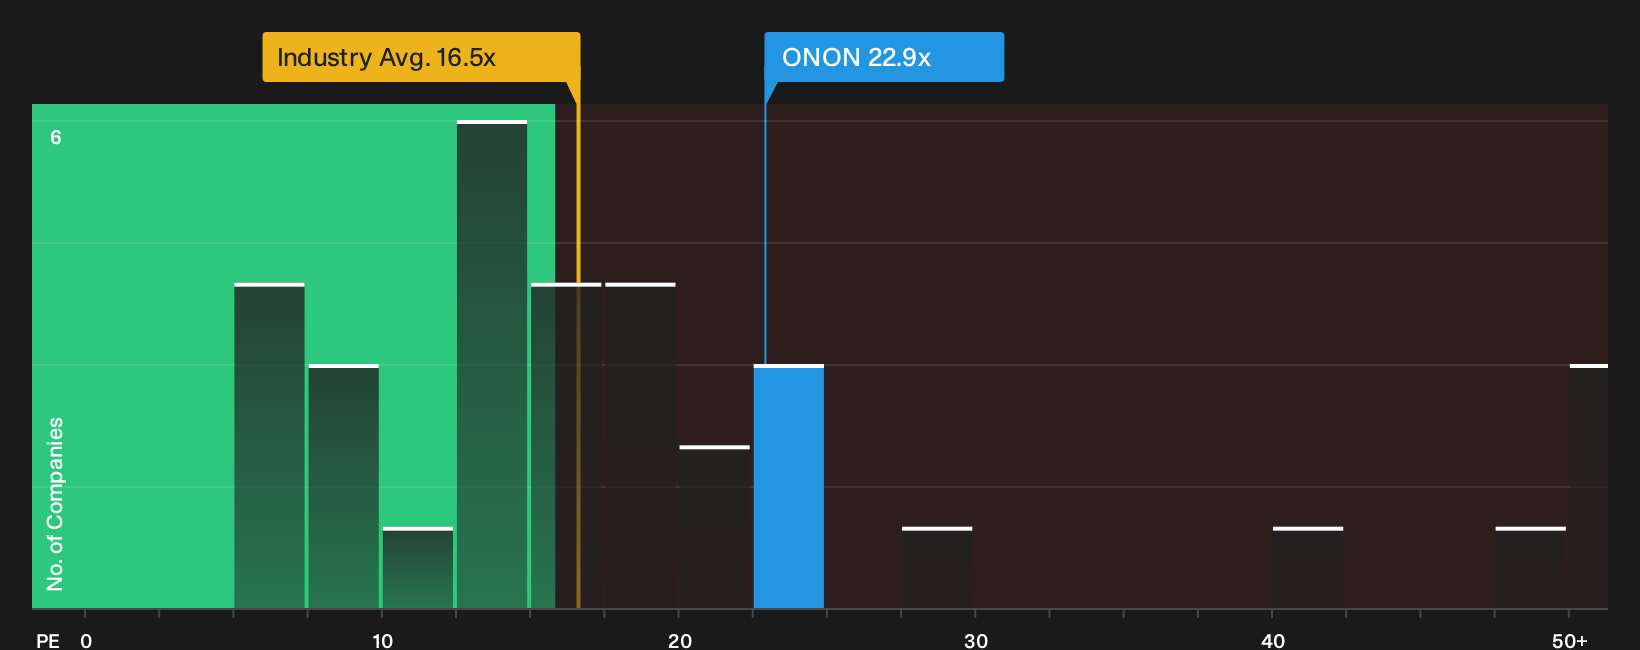
Look past the narrative fair value and a different picture appears. On Holding trades on a P/E of 22.9x, which is higher than both the US Luxury industry at 16.5x and the peer average at 15.4x, and even above its own 22.2x fair ratio. That gap points to less margin for error if sentiment sours.
See what the numbers say about this price in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment divided on whether On Holding appears attractively priced or already expensive, it may be useful to quickly examine the factors behind that debate for yourself. One place to start is by reviewing the 3 key rewards
Looking for more On Holding investment ideas beyond this stock?
Do not stop your research with On Holding. The next opportunity could sit in a different corner of the market, and you will only see it if you look.
- Target reliable compounders by scanning companies with resilient finances and prudent leverage using the list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality by reviewing the 18 high quality undiscovered gems that combine solid fundamentals with thinner analyst coverage.
- Dial down portfolio stress and focus on durability by screening for 30 resilient stocks with low risk scores before headlines move the crowd.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com