


EN
Revenue Guidance Raises The Bull Case For ASM International Stock (ENXTAM:ASM)
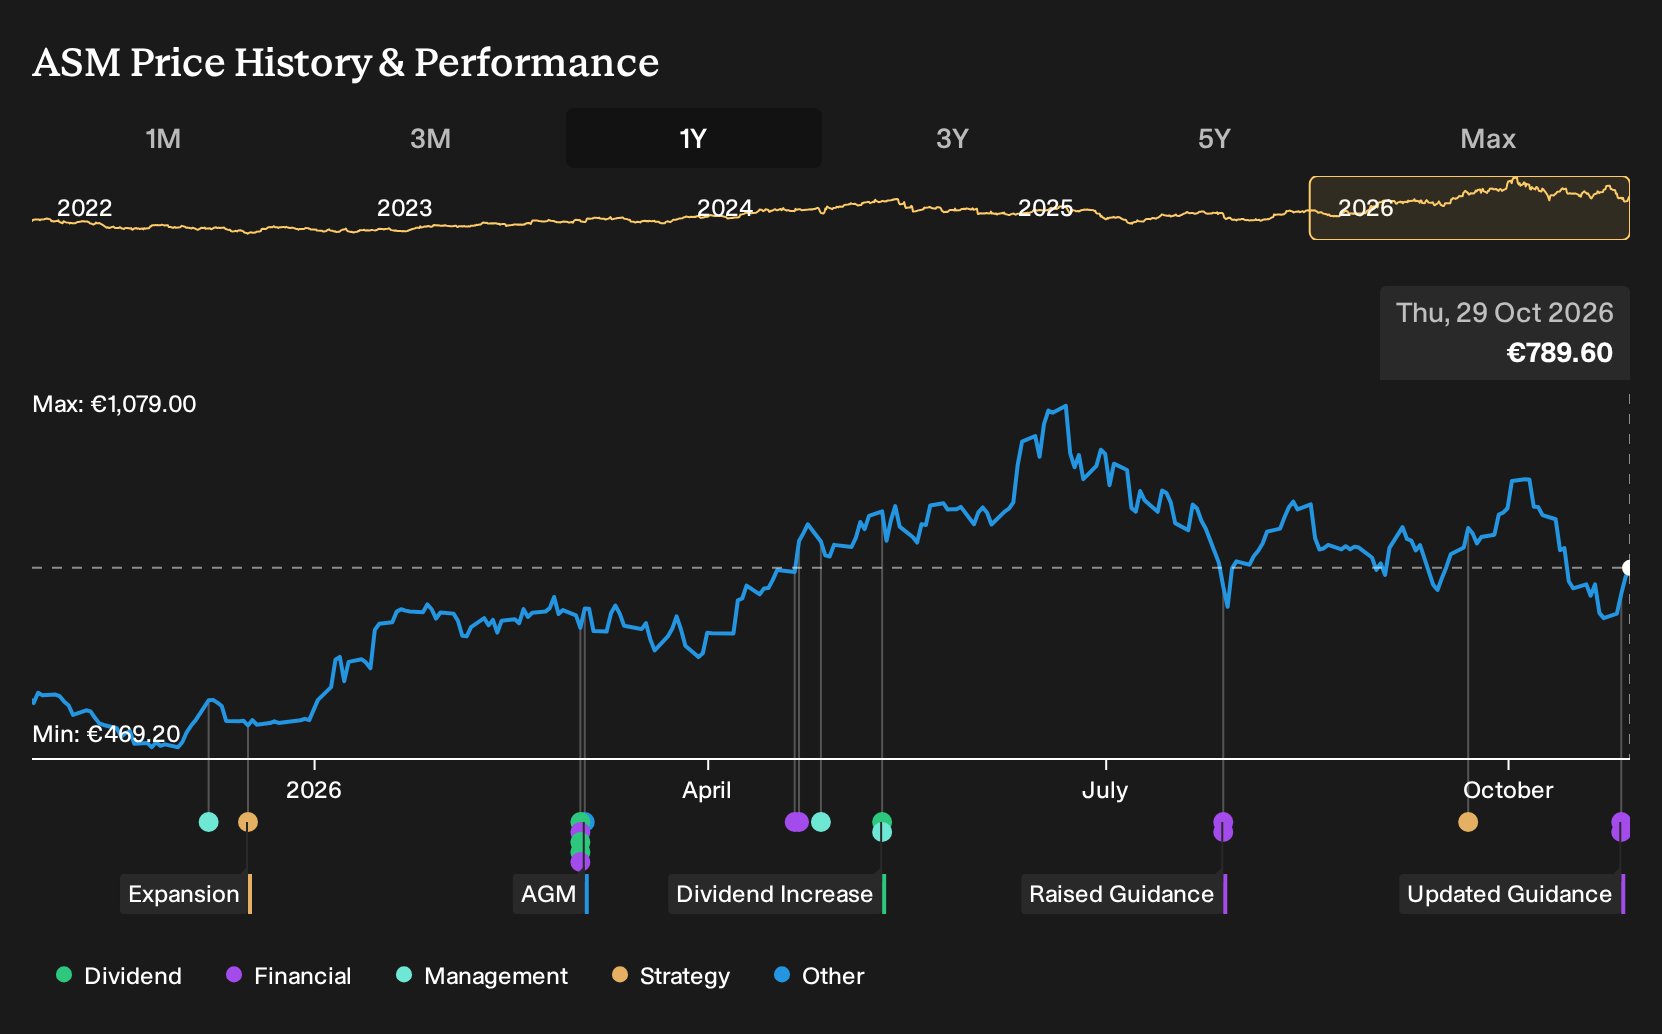
- ASM International reported third quarter 2026 sales of €1,159.4 million with net income of €308.1 million and issued revenue guidance pointing to €1,230 million +/-5% for the fourth quarter at constant currencies.
- The company paired softer quarterly earnings per share with projections for approximately 35% full year 2026 revenue growth and more than €5.7 billion in 2027 revenue, which highlights a tension between current profitability and its growth ambitions.
- We will now assess how ASM International's guidance for more than €5.7 billion in 2027 revenue could reshape the broader investment narrative.
Scan ASM International's guidance against a curated field of chip and automation beneficiaries by lining it up next to our hand picked 94 robotics and automation stocks.
ASM International Investment Narrative Recap
To own ASM International, you need to believe its tools keep winning slots in AI focused logic, memory and advanced packaging, even as near term profitability moves around. The fresh guide for about 35% 2026 revenue growth and more than €5.7b in 2027 presents a business that is still in investment and capacity ramp mode rather than peak margin mode.
The key near term swing factor is execution on this higher volume without supply chain bottlenecks or order pushouts at major customers. The biggest risk is that weaker China demand or tighter export controls could offset this momentum. Based on current information, the new guidance reinforces, rather than changes, that existing risk reward balance.
The most relevant update is the third quarter 2026 earnings report alongside the guidance reset. ASM International reported €1,159.4m of sales and €308.1m of net income, with diluted EPS from continuing operations of €6.27, down from €7.82 a year earlier. Profitability declined even as revenue was higher year on year.
That mix matters for potential catalysts. The firm is highlighting strong top line expansion through 2027, while investors are now seeing how sensitive earnings can be when product mix, China orders or costs move against it. If management delivers on the revenue path while stabilising margins, that would address the main operational question raised by the latest quarter.
What The New Long Term ASM International Targets Assume
ASM International's analyst model now lines up a long stretch of fast expansion with some pressure on profitability along the way. Consensus assumes revenue climbs at about 26.2% a year over the next three years, while profit margins step down from 31.9% today to 27.9% by year three. That mix points to a business that grows aggressively in absolute euro terms but earns a smaller slice of profit from each extra sale than it does right now.
On earnings, the current consensus pins profit at about €1.1b today and aims for roughly €1.9b by 2029, an increase of roughly €0.8b. That is a sizeable uplift, but it also sits well below the most optimistic analyst case that looks for as much as €2.6b in profit. For you as a shareholder, the gap between those two views highlights how much debate there is around the eventual earnings power if ASM International keeps leaning into AI logic, memory and advanced packaging.
Valuation assumptions carry their own moving parts. Analysts that set the current price targets are effectively using a 2029 earnings base of €1.9b, a P/E of 39.2x on those profits and a discount rate near 9.5%. They also assume the share count creeps higher at about 0.22% per year, which dilutes each existing share slightly, even as aggregate earnings rise. In other words, the story is not only about how big ASM International can become in euro terms, but also about how much of that future income each individual shareholder actually keeps.
ASM International's narrative projects €6.8b revenue and €1.9b earnings by 2029. This requires 26.2% yearly revenue growth and an earnings increase of roughly €0.8b from about €1.1b today.
Uncover why ASM International's fair value indicates a 45% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist you might explore is the idea that ASM International could turn its heavier spending into a future earnings engine. The most optimistic analysts were already pencilling in about €8.6b of 2029 revenue and €2.5b of earnings before this guidance. That is far above consensus and could be revised again as views adjust to the new targets.
Explore 4 other ASM International fair value estimates, including one that suggests as much as 85% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ASM International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ASM International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ASM International's overall financial health at a glance.
Looking For More Ideas Beyond ASM International?
Once you have a view on ASM International, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener. You can look for different risk profiles, income angles, or growth setups and see how they compare on the same consistent framework.
- If capital protection sits high on your list, scan for steadier businesses with a focus on resilience by starting with our 225 resilient stocks with low risk scores.
- For investors hunting for quality at a measured price, filter for companies that combine solid fundamentals with attractive pricing through the 607 high quality undiscovered gems.
- If balance sheet strength matters most to you, focus on cleaner finances and dependable metrics by checking the list of solid balance sheet and fundamentals (204 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com