


EN
Hermès (ENXTPA:RMS) Just Gave Investors A Bigger Question To Ask
Hermès guidance puts 2026 revenue ambitions in focus
Hermès International Société en commandite par actions (ENXTPA:RMS) set fresh 2026 earnings guidance on 22 October, outlining an ambitious goal for revenue growth at constant exchange rates. This immediately sharpened investor attention on the stock.
Hermès shares have had a rough stretch, with the 90 day share price return down 17.3% and the year to date share price return down 39.8%, while the 1 year total shareholder return has declined 41.3%. The fresh 2026 guidance arrives just as that momentum has been fading. This timing helps explain why investors are closely watching whether this new revenue ambition can reset expectations around the stock.
Compare Hermès International Société en commandite par actions' guidance-driven reset with other potential rebound stories by scanning our curated list of 607 high quality undiscovered gems that the market may be overlooking.
The recent slide in Hermès looks sharp on a chart, yet the business just outlined bold 2026 ambitions. Is this mainly about sentiment resetting, or does valuation now better reflect reality?
Most Popular Narrative: 22% Undervalued
The most followed narrative pegs Hermès fair value at about €1,632, compared with the last close at €1,266. This puts the 2026 revenue push against a valuation that already bakes in premium expectations but still flags upside according to that framework.
Ongoing expansion of global high-net-worth individuals, especially in Asia-Pacific (e.g., strong resilience in Japan and Korea, future revitalization anticipated in China), continues to broaden Hermès' core, loyal customer base, supporting a sustained uplift in long-term revenue growth.
Scarcity-driven supply model, underpinned by disciplined capacity investments (opening four new leather workshops in the next four years) and exclusive distribution expansion into key markets (e.g., U.S., China, India), enables Hermès to maximize pricing power and protect industry-leading gross/net margins.
See why 101 investors see Hermès International Société en commandite par actions as 22% undervalued.
Result: Fair Value of €1,632 (UNDERVALUED)
Still, that upbeat Hermès narrative could fray if Chinese demand stays muted for longer than analysts model, and if luxury resale activity keeps chipping away at perceived exclusivity.
Find out about the key risks to this Hermès International Société en commandite par actions narrative.
Another View: Multiples Paint A Tougher Picture For Hermès
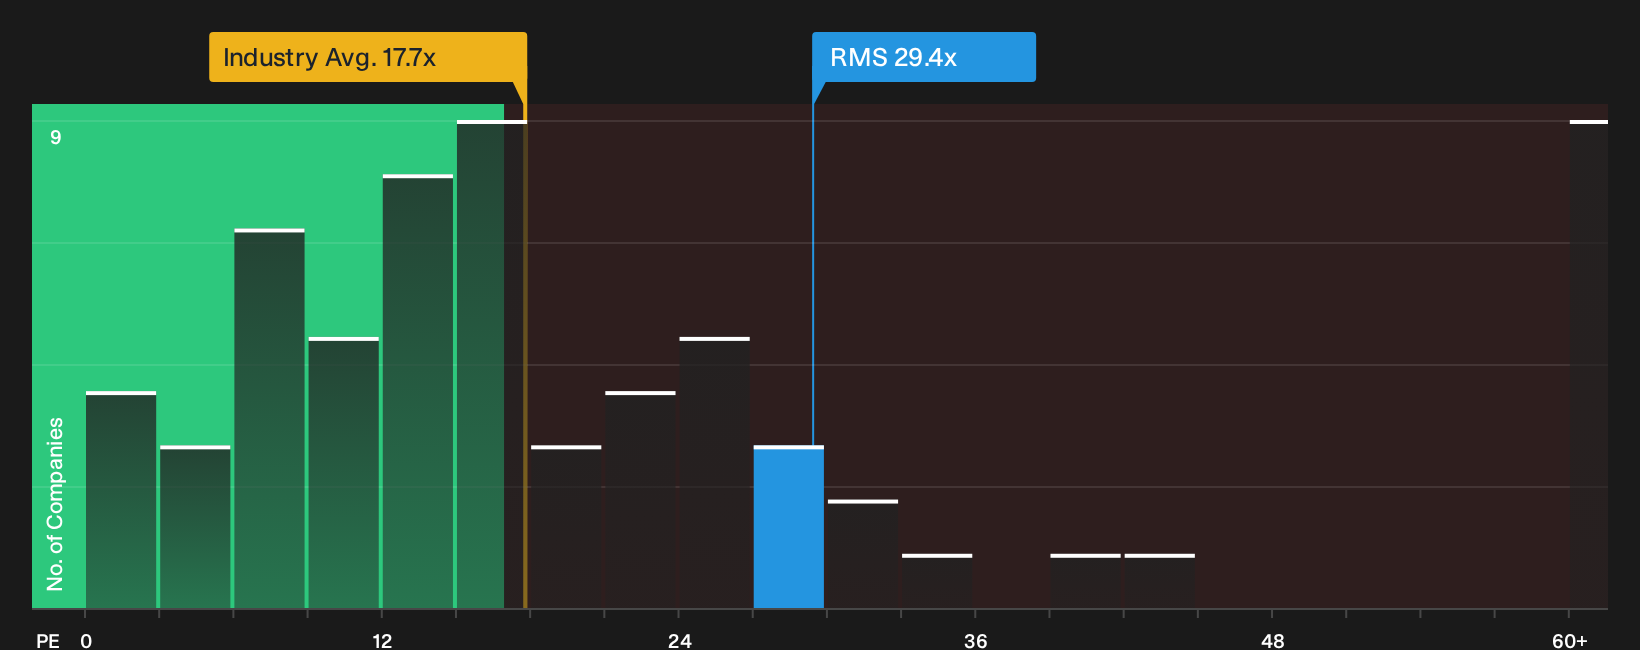
The DCF-style narrative sees Hermès as 22% undervalued at €1,632. Yet on simple earnings multiples, the picture looks very different. The stock trades on a P/E of 29.4x, versus 17.7x for the European luxury group and a fair ratio of 18.8x. That gap points to clear valuation risk if sentiment stays fragile.
For investors who lean on simple earnings ratios, that premium raises a practical question. Is Hermès worth paying such a steep multiple when both sector peers and its own fair ratio screen meaningfully lower, or does the brand justify staying at the expensive end of the range?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Think the tone here feels either too cautious or too generous on Hermès International Société en commandite par actions? Move quickly, test that instinct against the underlying data, and pressure test the upside cases through the 3 key rewards.
Looking for more investment ideas beyond Hermès?
If Hermès has you rethinking what premium really means, do not stop here. Put that curiosity to work and let a structured search surface fresh opportunities.
- Target resilient compounding potential by focusing on companies that look attractively priced relative to their quality through the 197 high quality undervalued stocks.
- Strengthen your income stream by filtering for payout-focused businesses with higher yields using the 224 dividend fortresses.
- Prioritise sleep-at-night holdings by zeroing in on companies that carry lower overall risk scores through the 227 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com