


EN
Did Job Cuts Just Shift National Australia Bank's (ASX:NAB) Investment Narrative?
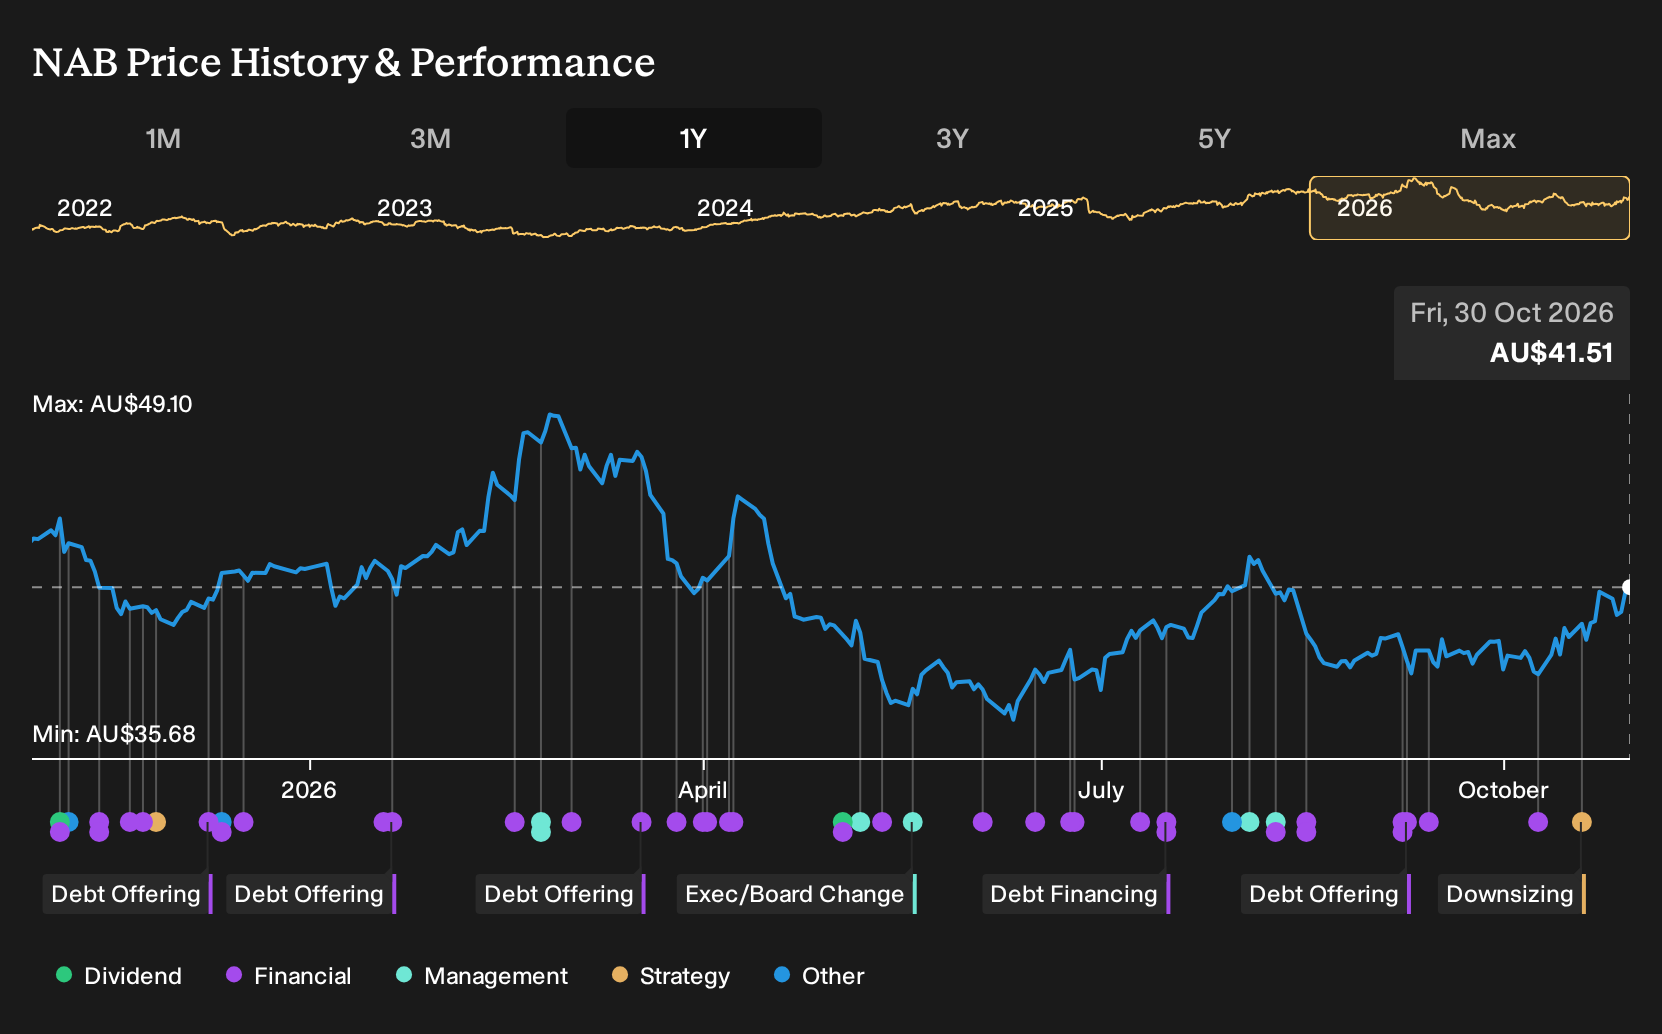
- National Australia Bank recently outlined a workforce overhaul, planning to cut up to 2,500 internal roles, or about 6% of staff, by FY 2027 and booking an expected A$300 million pre tax restructuring charge tied to redundancy, redeployment and redesign costs.
- The bank is using this restructuring to shift resources toward growth and technology projects, while also trimming consultant and contractor spending. The aim is to reweight its cost base toward core banking priorities such as business lending, deposits and proprietary home loans.
- We will now assess how National Australia Bank's planned 2,500 role reduction could reshape its investment narrative around costs and growth.
Scan how other banks and financials are reshaping their cost base and tech spend by reviewing our hand picked list of solid balance sheet and fundamentals (12 results) alongside National Australia Bank's latest overhaul.
National Australia Bank Investment Narrative Recap
To own National Australia Bank, you need to be comfortable that a large, regulated lender can keep expense growth in check while funding heavy technology projects and still protecting credit quality. The planned 2,500 role reduction and A$300 million restructuring charge bring that trade off into focus but do not change the basic thesis around business lending, deposits and proprietary home loans.
The clearest short term swing factor remains whether cost to income can improve as tech spending, wage pressure and restructuring costs all compete for room in the budget. The biggest risk sits on the other side of the balance sheet, where any broad deterioration in business credit or commercial real estate could force higher impairment charges and constrain capital flexibility.
The workforce overhaul directly intersects with National Australia Bank’s push into digital payments and cloud based infrastructure. Management is already migrating payments and card transactions to a real time engine and modern switch, with technology modernization and AI tools targeting more than A$450 million in productivity savings in FY 2026. The new operating model is designed to free capacity for these programs.
For you, the practical question is how cleanly the bank can execute that shift. If expense cuts from headcount, consultants and contractors do not offset higher cybersecurity, cloud and modernization outlays, cost to income could stay stubborn. This is particularly relevant if revenue growth trends at the 4% to 5% range analysts expect. Combined with any lift in bad debts, the restructuring could feel more like defence than opportunity.
National Australia Bank’s analyst narrative points to A$24.2 billion in revenue and A$8.1 billion in earnings by 2029, based on projected 5.0% yearly revenue growth and an earnings increase of A$2.0 billion from A$6.1 billion today.
Uncover how National Australia Bank's fair value indicates a 7% potential downside to its current price, a premium that may not be sustainable.
Exploring Other Perspectives
One alternate view focuses on technology expenses rather than headcount cuts. The most bearish analysts already assumed rising tech OpEx would bite into National Australia Bank’s margins, even while forecasting A$23.9b of revenue and A$8.0b of earnings by 2029. You can see how the new workforce plan might push those cautious forecasts even lower or prompt a rethink in either direction.
Explore 4 other National Australia Bank fair value estimates, including one that suggests as much as 7% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your National Australia Bank research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for National Australia Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Australia Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond National Australia Bank?
If the National Australia Bank overhaul has you rethinking your portfolio mix, it can help to scan other businesses with different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential upside without paying too much for quality, you can review 1 high quality undervalued stocks that pair stronger fundamentals with more appealing valuations.
- If resilience and capital preservation sit higher on your list, consider checking 6 resilient stocks with low risk scores that score well on balance sheet strength and risk metrics.
- Those hunting for lesser known stories with solid financial footing can sift through 15 high quality undiscovered gems that may not be widely followed yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com