


EN
3 US Financial Stocks That Could Benefit If Fed Rates Stay Higher Longer
Interest rates are no longer background noise. With markets bracing for more Fed tightening, cash-linked business models and floating-rate exposure sit in the spotlight, where higher policy rates can quickly reshape income streams and investor expectations. That creates both opportunity and risk. This article walks through three US financial stocks tied to that story and explores how the latest Fed signals may help or hurt their outlook.
The three stocks below are just a sample set. The full screen surfaced 43 more US-listed financial firms with cash-linked or floating-rate angles that are not covered here but carry similarly interesting stories for rate-sensitive income.
If you want to go straight to the source and work through the complete universe yourself, analyze and filter the US Floating-Rate and Cash-Linked Financials using the US Floating-Rate and Cash-Linked Financials screener.
FirstSun Capital Bancorp (FSUN)
FirstSun Capital Bancorp is built around relationship banking for small and mid-sized businesses, and its focus on variable-rate lending and cash management puts it squarely in the path of shorter term rate moves that the Fed is now signaling.
"FirstSun's robust deposit growth across both consumer and business segments, especially in high-growth Southwestern and newly entered California markets, positions the bank to capitalize on urban migration trends and expanding local economies, supporting future revenue and net interest income expansion."
What happens to its margins if one quiet pressure point on funding costs shifts faster than the loan book can reprice?
FirstSun Capital Bancorp is a Denver based bank holding company for Sunflower Bank, focused on commercial and consumer lending, cash management, and wealth services tied closely to variable-rate loans and customer deposits across the United States. It generates US$525 million of revenue, and it carries a market cap of about US$1.9b.
If that funding squeeze question is front of mind, read the full narrative for FirstSun Capital Bancorp to see how FirstSun Capital Bancorp’s rate sensitivity could be accelerating or quietly stalling.

Bank of N.T. Butterfield & Son (NTB)
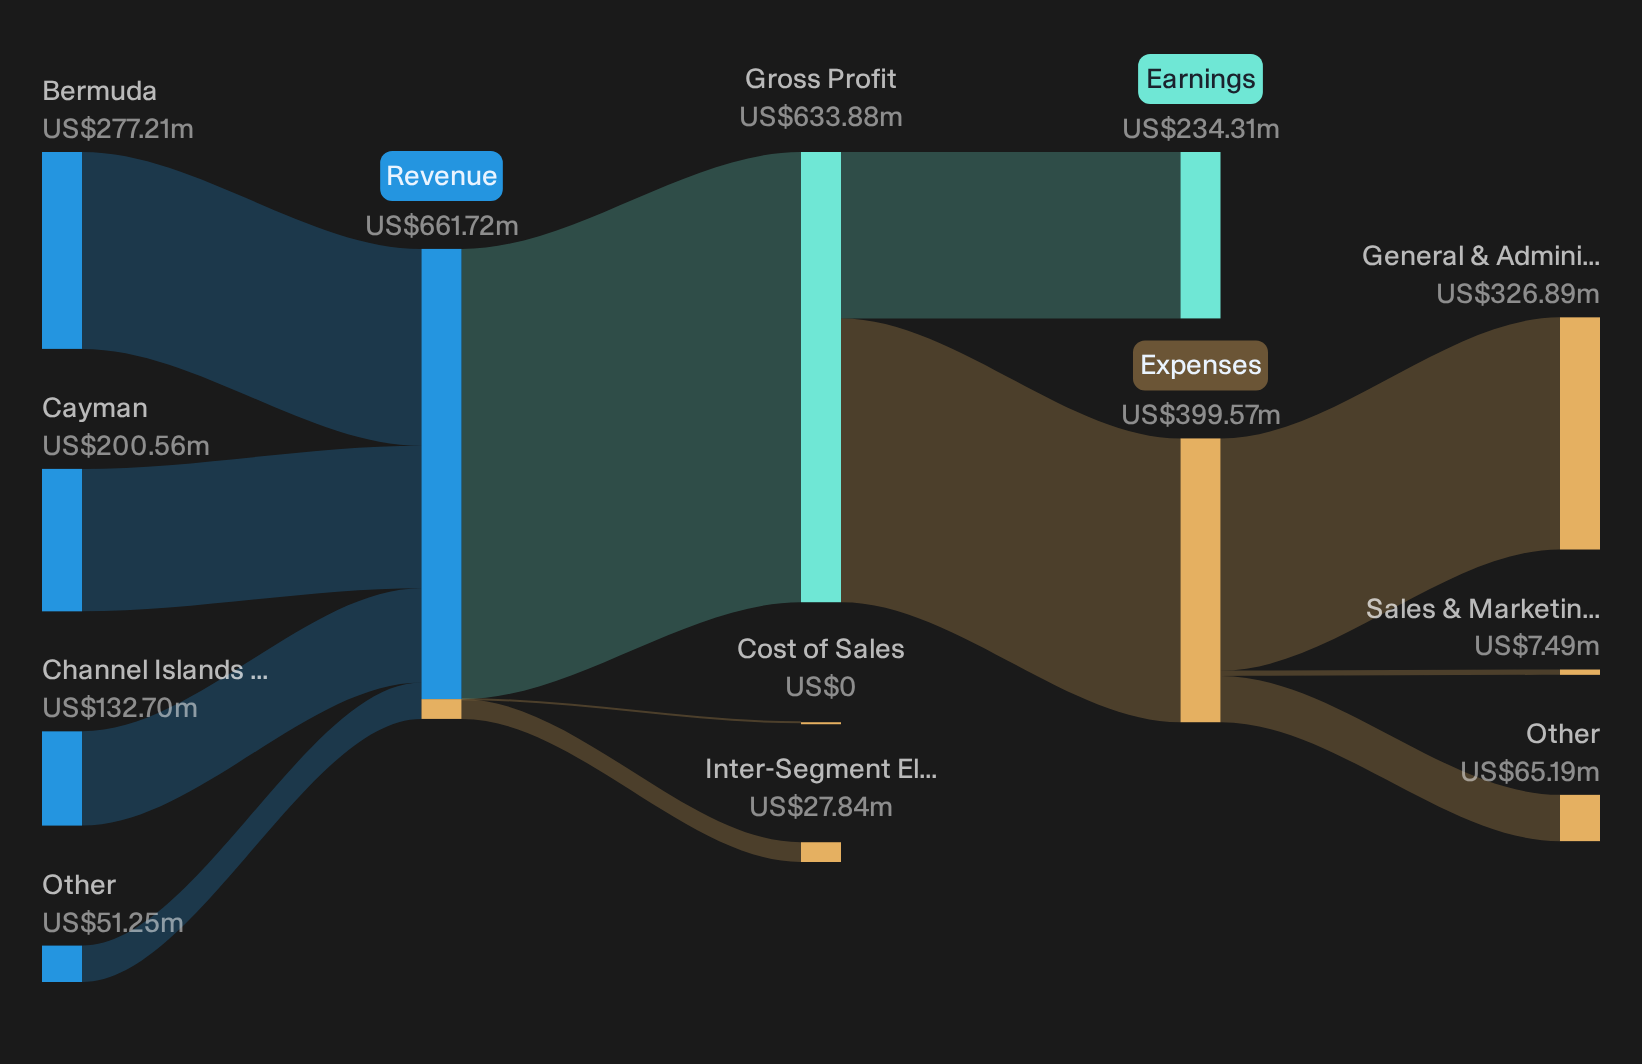
Bank of N.T. Butterfield & Son links everyday deposits, wealth management cash and floating-rate loans into one offshore-focused platform that fits the screener’s short-term yield theme. Its scale ambitions set up a bigger question about what higher-for-longer policy rates might mean for that model.
The Bank of N.T. Butterfield & Son generates about US$634 million from banking activities, combining lending, deposit taking and fee-based services across offshore financial hubs, and the stock carries a market cap near US$2.3b.
"The planned acquisition of CIBC Caribbean for just under US$1.8b, which is expected to roughly double group assets and deposits and add more than US$400m of run rate earnings, would give the bank a larger offshore footprint that management indicates could lift long term revenue and earnings once integration is complete."
What really shapes the outcome for Bank of N.T. Butterfield & Son is how one quiet swing factor alters the balance between richer yields and rising funding pressure.
If that funding swing factor has your attention, read the full narrative for Bank of N.T. Butterfield & Son to see whether higher yields are masking risks or accelerating Butterfield’s offshore earnings story.
Triumph Financial (TFIN)
Triumph Financial plugs directly into the screener’s short-term rate story through its mix of commercial banking, factoring and payments, with much of its activity linked to cash flowing quickly through the freight and trucking economy.
Triumph Financial runs a US-focused platform across banking, factoring, payments and freight intelligence, earning about US$223 million from banking, US$146 million from factoring, US$79 million from payments and US$9 million from intelligence, with a market value near US$1.5b.
The appeal for rate-focused investors is that Triumph Financial’s freight-centric, transaction-heavy model can feel closer to a cash-yield engine than a traditional regional bank. This is exactly what the next comment hints at.
"A structural shift toward tighter, compliance focused freight capacity is supporting higher average invoice values, and Triumph Financial’s sensitivity to invoice pricing changes means further moves in average ticket size can translate into higher transportation revenue and pretax income."
What really matters now is how one quiet shift in the mix of fee-heavy freight flows versus old-line lending shapes future margins and earnings power.
That shift in mix is exactly what sits at the heart of the full narrative for Triumph Financial, which maps how Triumph Financial’s freight engine could be accelerating or quietly stalling.

Seeking Alternatives Before Momentum Flies
Market momentum can flip fast. Fresh opportunities often move from quiet to crowded once the crowd catches on. Scan these under the radar ideas now and get in early.
- Target dependable income streams while the yields are still attractive by reviewing the curated 7 dividend fortresses that focus on durable payouts and balance sheet strength.
- Catch early waves in automation and logistics by scanning the hand picked 94 robotics and automation stocks positioned around real-world adoption of robots and industrial efficiency gains.
- Position ahead of potential capacity tightness in energy supply by assessing the focused 16 nuclear energy infrastructure stocks aligned with long term power infrastructure projects.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com