


EN
Is Canadian Natural Resources (TSX:CNQ) Cheap As Earnings And Dividend Focus Build?
Canadian Natural Resources (TSX:CNQ) is back in focus as investors look ahead to the November 5 earnings release, with attention fixed on expected year over year profit growth and the durability of its dividend.
Recent trading has been strong, with the share price at CA$77.05 after a 30 day share price return of 15.15% and a year to date share price return of 63.52%. The 1 year total shareholder return of 79.81% signals momentum that investors are weighing against earnings risks and dividend reliability.
Compare Canadian Natural Resources to other income focused energy plays by scanning our curated list of 3 dividend fortresses.
Canadian Natural Resources now trades slightly above the average analyst target, yet screens at a sizeable intrinsic value discount. After this sharp run, is the skepticism in that gap still reasonable or already overdone?
Most Popular Narrative: 3% Overvalued
Canadian Natural Resources last closed at CA$77.05, modestly above the CA$75.10 fair value implied by the most followed narrative, which frames a tight balance between strong cash generation and a full valuation.
The updated free cash flow allocation policy, which now directs 75% of free cash flow to shareholders once net debt falls below $16b and 100% once it reaches $13b, sets up a framework in which future cash generation is increasingly tied to dividends and buybacks, with potential implications for earnings per share and equity valuation.
See why 218 investors see Canadian Natural Resources as 3% overvalued.
At the heart of that view is a relatively low 6.44% discount rate applied to Canadian Natural Resources and a fair value of CA$75.10 that now sits just below both the CA$77.05 market price and the CA$75.1 analyst consensus target. The narrative links this slight premium to expectations that long life oil sands reserves, a formal free cash flow policy and active buybacks can support cash generation even while headline revenue is projected to contract.
Analysts in that narrative assume revenue declines of about 2.6% a year over the next three years and profit margins softening from 26.3% to 21.6%, with earnings moving from CA$11.8b today to CA$8.9b by around October 2029 and the P/E lifting from 13.4x to 20.3x on those earnings. For this path to line up with the fair value, the market would effectively be paying more for each dollar of profit in 2029 while overall earnings are lower, which asks investors to put real weight on the durability of Canadian Natural Resources reserves, capital discipline and dividend policy.
The same narrative highlights that analysts expect shares outstanding to shrink by about 1.04% a year over the next three years, which supports earnings per share even when total profit is projected to fall. That capital return focus, combined with a current intrinsic discount of 46.4% on one DCF style estimate and a reported 3.24% dividend yield, explains why some investors see room in the story even as the most popular narrative now tags Canadian Natural Resources as slightly overvalued on a fair value basis.
Result: Fair Value of CA$75.10 (OVERVALUED)
Still, analysts flag real pressure points, including stalled oil sands expansions awaiting regulatory clarity and crude price swings that have recently driven sharp short term moves in Canadian Natural Resources.
Find out about the key risks to this Canadian Natural Resources narrative.
Another View: Canadian Natural Resources On Earnings Multiples
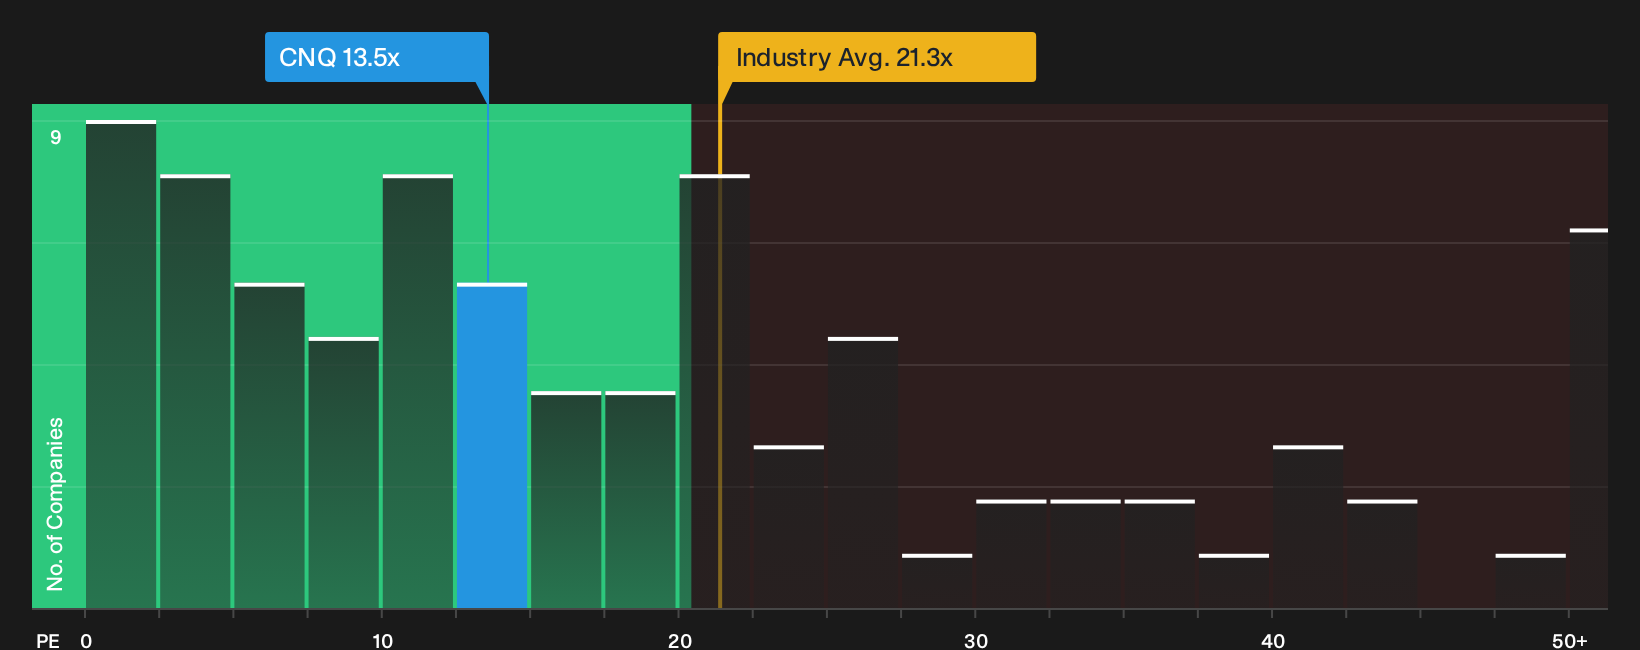
That slightly overvalued fair value call clashes with what the earnings multiple is hinting at. Canadian Natural Resources trades on a P/E of 13.5x, versus 21.3x for the broader Canadian Oil and Gas group and 34.7x for peers. A fair ratio of 14.5x suggests only a small move would close the gap.
If the market edges closer to that fair ratio, investors are weighing whether this current discount on P/E signals opportunity or simply reflects the forecast declines in revenue and earnings.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Canadian Natural Resources valuation and outlook are clear, so consider acting while sentiment is divided and weigh both sides of the story for yourself by checking the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Canadian Natural Resources?
If you want a broader view than Canadian Natural Resources alone, use the Simply Wall St screener to spot fresh ideas that fit your own risk and income goals.
- Target potential bargains that combine quality fundamentals with compressed valuations by scanning our curated list of 4 high quality undervalued stocks.
- Prioritise resilience by running through a 8 resilient stocks with low risk scores that highlights businesses with more defensive risk profiles.
- Hunt for future leaders that many investors may be overlooking by checking a 8 high quality undiscovered gems before they get crowded.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com