


EN
Is BridgeBio Pharma (BBIO) Undervalued On Earnings That Showed Higher Revenue And A Smaller Loss?
BridgeBio Pharma earnings jolt puts Q3 loss and revenue in focus
BridgeBio Pharma (BBIO) just put a fresh earnings print in front of investors, with third quarter figures showing US$353.17 million in revenue and a net loss of US$56.71 million.
The latest report comes after a strong multiyear run for BridgeBio Pharma, with a 1-year total shareholder return of 11.61% and a 3-year total shareholder return of about 16x. This comes even as the 90-day share price return declined 11.69% and year-to-date performance fell 9.59%.
Scan beyond BridgeBio Pharma and see how other biopharma stocks with improving revenue and shrinking losses stack up in the 18 high quality undiscovered gems.
BridgeBio Pharma just posted a sharp swing in revenue and a smaller loss, yet the share price has cooled in recent months. Does that mix set up a better entry now, or does patience make more sense?
Most Popular Narrative: 183% Overvalued
BridgeBio Pharma last closed at $70.73, while the most followed valuation story on Simply Wall St pegs fair value at $25.00. This puts a big gap between the trading price and where that narrative thinks the stock belongs.
The "BridgeBio Commercial Bonanza" is priced for perfection, treating the upcoming Acoramidis launch as an automatic cash cow while ignoring a brutal multi-front commercial dogfight.
Here is why the market is mispricing the structural hurdles for BBIO:
1. The Pfizer Moat & SG&A Bleed: Outperforming Vyndaqel in a clinical trial does not guarantee market share. Pfizer’s commercial entrenchment in the ATTR-CM space is institutional. For BBIO to compete, marketing and launch expenses will skyrocket, severely depressing free cash flow and delaying true profitability far past consensus timelines.
See why 4 investors see BridgeBio Pharma as 183% overvalued.
Result: Fair Value of $25.00 (OVERVALUED)
Still, if BridgeBio Pharma executes on its pipeline or if market competition proves less punishing than feared, that commercial dogfight narrative could start to look overstated.
Find out about the key risks to this BridgeBio Pharma narrative.
Another View: SWS DCF Model Flips the Script
That fair value of $25.00 paints BridgeBio Pharma as stretched, yet our DCF model points in the opposite direction. Based on those future cash flow assumptions, SWS estimates value at $287.59 per share, which would leave the current $70.73 price looking heavily undervalued. Which story do you consider more compelling: the cash flow math or the commercial risk concerns?
Look into how the SWS DCF model arrives at its fair value.
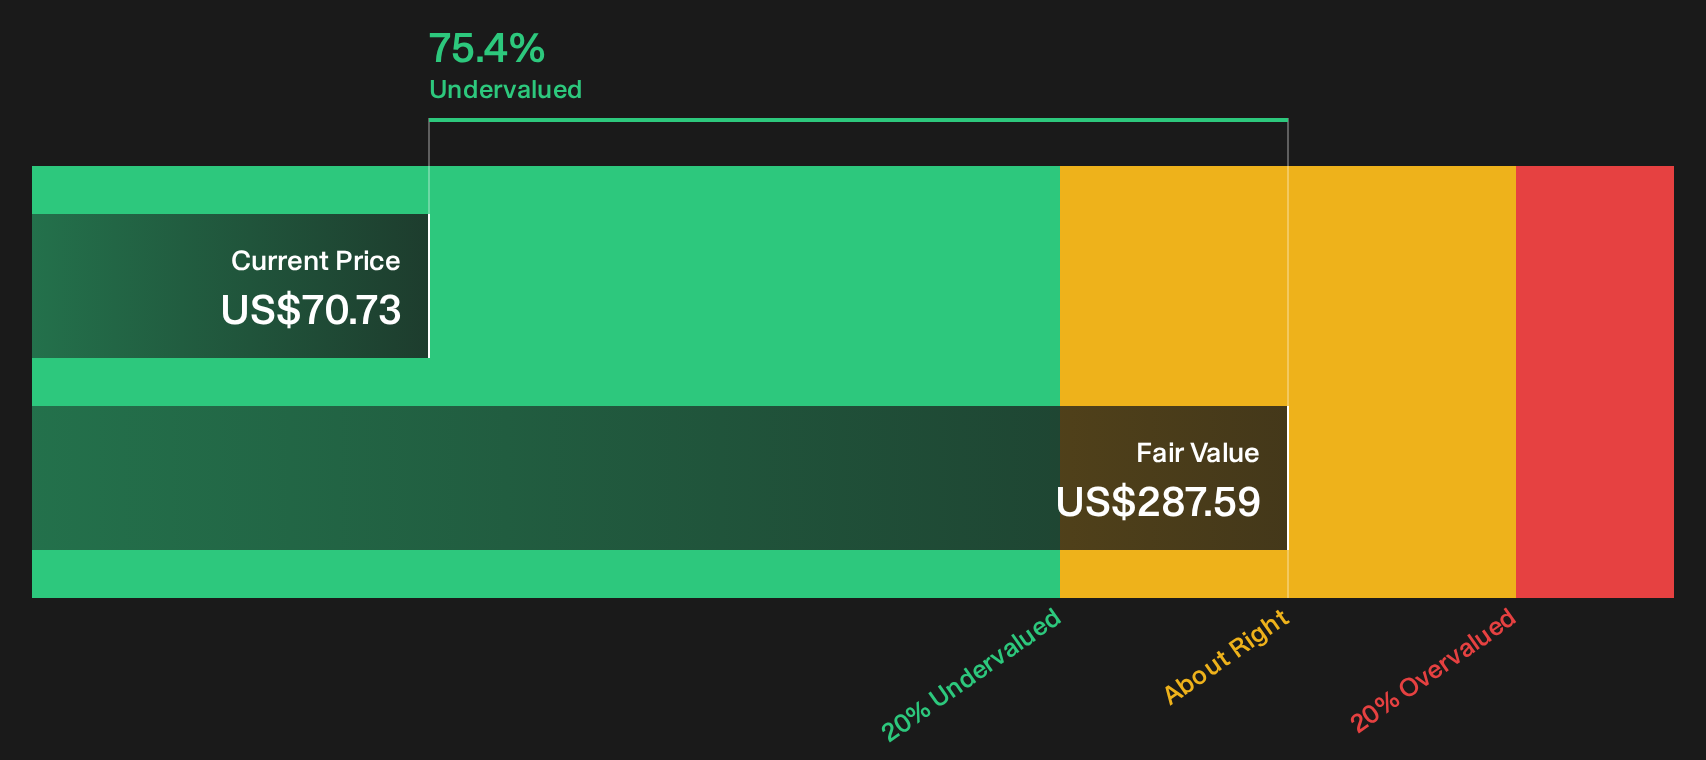
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BridgeBio Pharma for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on BridgeBio Pharma so far, right. Step off the sidelines for a moment, review the same numbers, and pressure test the 2 key rewards and 1 important warning sign.
Hunting for more ideas beyond BridgeBio Pharma?
If you stop with BridgeBio Pharma, you risk missing companies that might fit your goals even better, so broaden the search before you commit fresh capital.
- Target potential mispricing in quality businesses by scanning the 30 high quality undervalued stocks that combine stronger fundamentals with more modest expectations.
- Prioritize resilience and lower downside risk by reviewing the 30 resilient stocks with low risk scores that score well on stability and business quality checks.
- Spot future market leaders early by working through the 9 elite penny stocks with strong financials that already show healthier financial markers than typical micro caps.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com