


EN
Renault Stock What Changed After EV Sales Jump And 2026 Guidance Held
- Renault reported group revenue of €11,426 million for Q3 2026, up 1.5% year on year, and €39,066 million for the first nine months, with full year 2026 guidance for an operating margin around 5.5% of group revenue confirmed.
- Electric vehicle deliveries rose 84.7% in the quarter, lifting EVs to 25.8% of Renault's sales mix and underscoring how electrified models are reshaping the business profile.
- We will look at how Renault's investment narrative is shaped by confirmed 2026 margin guidance and the sharp rise in electric vehicle sales.
See how Renault's latest EV surge compares with peers by reviewing a hand picked set of auto stocks filtered for electrification momentum and solid fundamentals in the list of solid balance sheet and fundamentals (207 results)
Renault Investment Narrative Recap
Owning Renault means believing the electrified product push, faster development under Ampere and the support from Mobilize Financial Services can keep the business on track even with only modest top line progress. The latest quarter shows that EV mix is rising quickly while overall revenue growth is more muted, so mix and cost control matter more than volume.
The confirmed 2026 operating margin aim of around 5.5% signals that management still sees its cost savings and pricing plans as achievable in the near term. For now, that helps the main short term catalyst, execution on the futuREady product and efficiency plan, outweigh the key risk from margin pressure as EV share and exposure to lower margin regions increase.
The reaffirmed guidance for an operating margin around 5.5% of group revenue, alongside an automotive free cash flow goal of about €1b, is the clearest data point from this update. It ties directly to whether Renault can offset raw material and inflation headwinds of roughly €600 million with the efficiency gains baked into the plan.
If that margin and cash generation level is delivered, it would support the idea that the combination of EV launches, Ampere time to market gains and Mobilize Financial Services dividends can fund the transition without stressing the balance sheet further. If execution stumbles, investors are likely to refocus quickly on leverage, the diesel trial risk in 2027 and how much pricing power Renault really has in a more crowded EV market.
What Analyst Assumptions Mean For Renault
Renault's narrative projects €65.0b revenue and €2.0b earnings by 2029. This rests on analysts using a 2.4% yearly revenue growth rate and an earnings increase of about €1.1b from €947.0m today.
Those analyst assumptions ask you to think beyond the latest quarter and weigh a slow build in the figures. A 2.4% annual rise in sales is not aggressive for a global automaker, so the story hinges more on the move from a 1.6% profit margin today to 3.2% in three years. The forecast step up to €2.0b of earnings by 2029 doubles current profit, so the margin lift matters more than volume.
In that framework, Renault is not pitched as a rapid growth story. It is positioned as a business that could potentially squeeze more profit out of a relatively steady revenue base if the futuREady plan, Ampere efficiencies and Mobilize dividends flow through as expected. Price discipline on electric models, tighter costs and better factory utilisation are the levers included in that view.
There is also a clear spread in analyst opinions. Earnings forecasts range from €1.8b to €2.4b for 2029, which shows how sensitive the outcome is to small shifts in margin or pricing. For you as an investor, the key question is not whether €2.0b is the precise number, but whether you think Renault can comfortably move earnings above the current €947.0m level on a sustained basis.
Uncover why Renault's fair value indicates a 37% potential upside to its current price that could narrow quickly if sentiment toward Renault shifts.
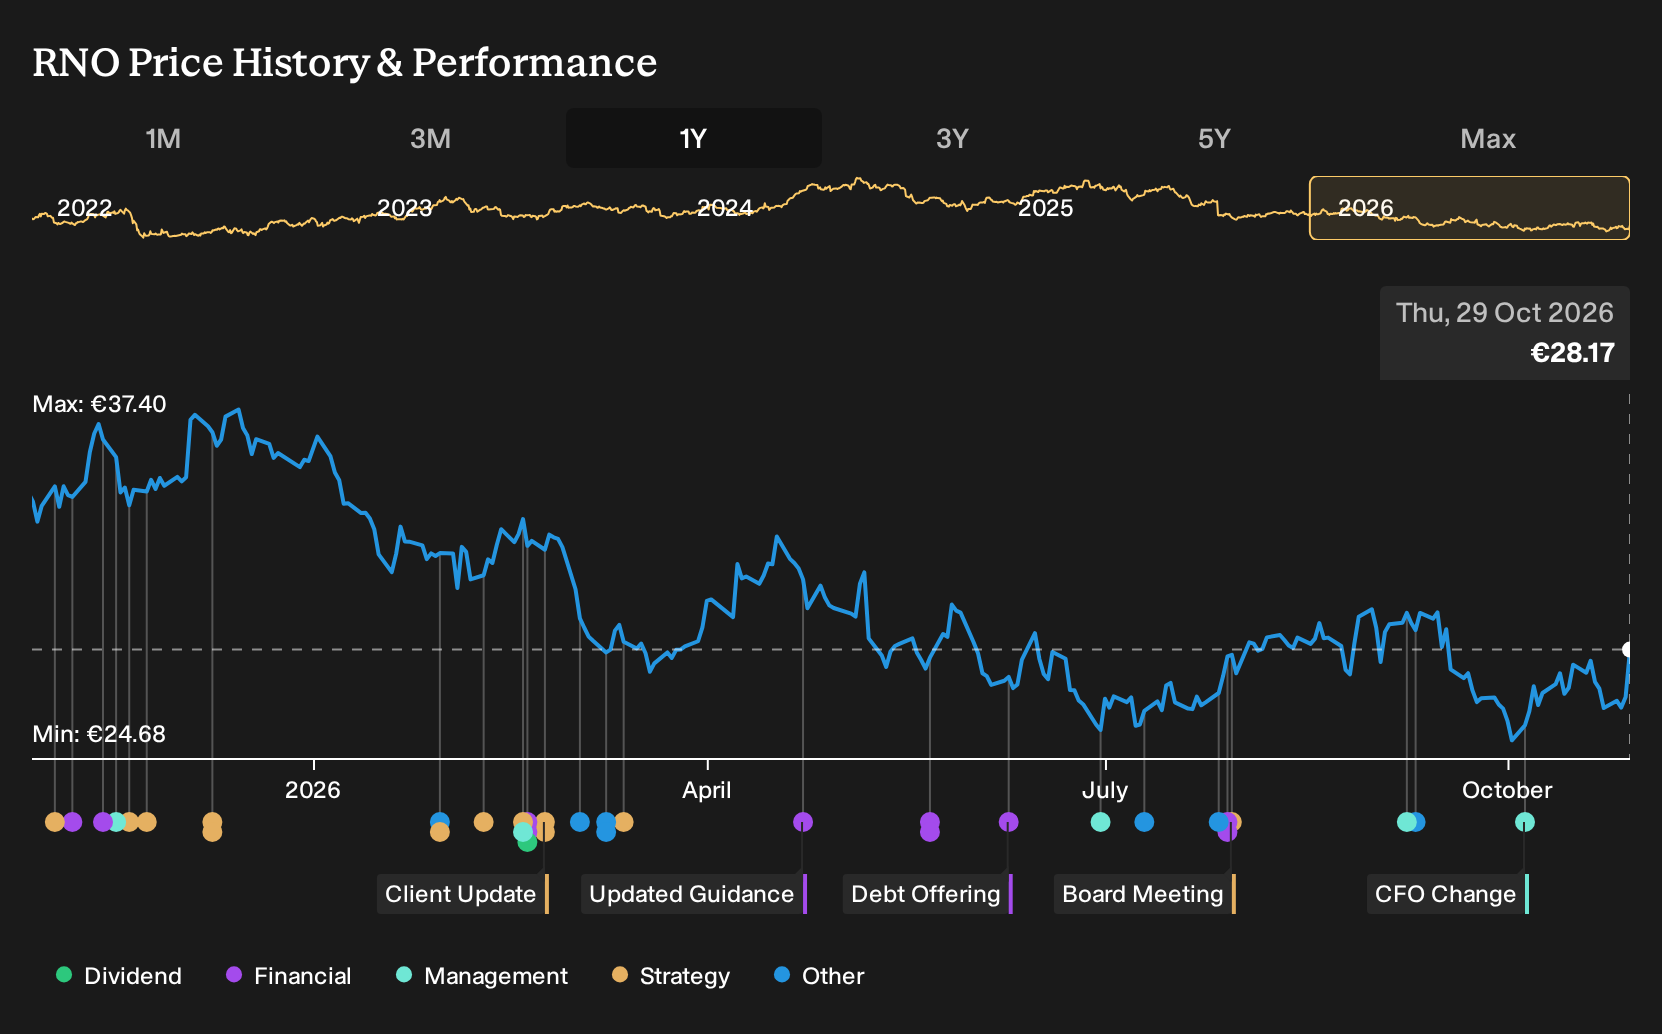
Exploring Other Perspectives
One bullish twist on Renault focuses on how far margins could stretch if the new EV mix and cost cuts really compound. The most optimistic analysts were already pencilling in around €69.8b of revenue and €2.3b of earnings by 2029 before this Q3 update. You can treat this sales statement as a fresh test of those higher expectations and decide which narrative feels closer to your own view.
Explore 3 other Renault fair value estimates, including one that suggests as much as 106% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Renault research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Renault. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Renault's overall financial health at a glance.
Looking For More Investment Ideas Beyond Renault?
Once you have formed a view on Renault, it can help to compare that thesis with other opportunities that share similar financial traits. The Simply Wall St Screener lets you filter by balance sheet strength, income reliability and risk profile so you can build a watchlist that fits your own tolerance and goals.
- If you want sturdier financial foundations, start with companies that pair healthy cash flows with robust balance sheets via the list of solid balance sheet and fundamentals (207 results).
- For investors hunting for value, look across a curated set of stocks that screen well on quality yet still trade at what looks like a discount using the 195 high quality undervalued stocks.
- If income is a priority, focus on businesses offering higher yields that also aim for staying power by checking out the 228 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com