


EN
How Raised Guidance Will Impact Sirius XM Stock (SIRI) Investors
- Sirius XM Holdings reported Q3 2026 revenue of US$2.15b with net income of US$317m, while EPS exceeded analyst expectations despite a flat top line.
- Management raised full year 2026 guidance and highlighted a shift toward higher lifetime value subscribers, along with a wider ad reach via YouTube Audio.
- The next focus will be on how Sirius XM Holdings' raised 2026 guidance could reshape its longer term investment narrative.
Sirius XM Holdings Investment Narrative Recap
To stay invested in Sirius XM Holdings, you need to believe the subscription base and growing digital footprint can support steady cash generation even if headline revenue moves slowly. Q3 fits that picture. Revenue held roughly flat while net income and basic EPS were higher, helped by cost discipline and a tilt toward higher value subscribers rather than sheer volume.
The near term swing factor is whether this mix shift and the broader audio reach, including the YouTube Audio partnership, can keep churn low and advertising relevant despite intense streaming competition. The main risk still sits on the top line. If subscription and ad revenue soften together, the earnings story becomes harder to sustain.
The regular US$0.27 quarterly dividend just affirmed by Sirius XM Holdings matters in this context. It tells you management is willing to keep returning cash even as revenue growth remains modest and the balance sheet carries a meaningful debt load. For an income focused holder, the reliability of that payout becomes a key part of the thesis.
At the same time, an unstable dividend track record sits in the risk bucket, so this new declaration does not remove dividend uncertainty. It simply extends the current pattern. If operating cash flow were to come under pressure from weaker subscriptions or slower progress in digital advertising, the ability to keep funding that dividend at the same level could be tested.
Sirius XM Holdings' narrative projects US$9.2b revenue and US$1.2b earnings by 2029. This rests on 2.1% yearly revenue growth and an earnings increase of about US$320m from US$880.0m today.
Uncover why Sirius XM Holdings' fair value indicates a 16% potential upside to its current price, which could narrow quickly.
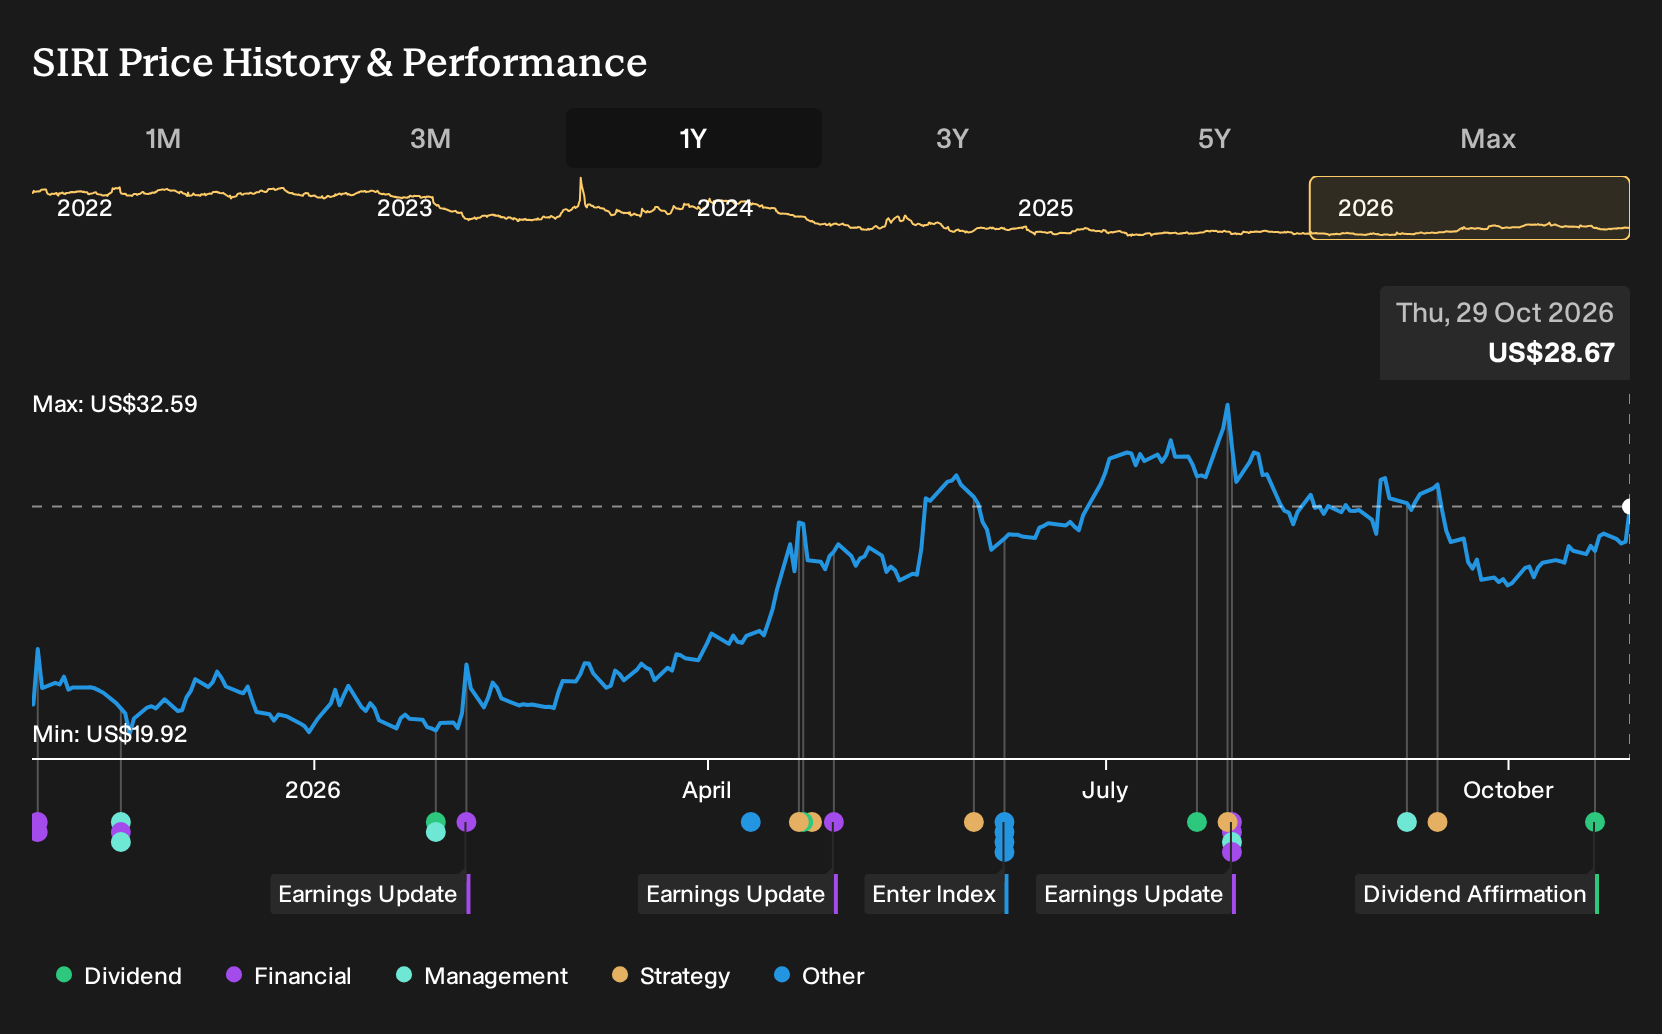
Exploring Other Perspectives
Some of the lowest ranked analysts worry that Sirius XM Holdings is already priced for success. They work off a slower top line view, with revenue nearer US$8.8b by 2029 instead of US$9.2b, and similar US$1.2b earnings. You can treat that as a far more cautious story that may shift after this quarter.
Explore 7 other Sirius XM Holdings fair value estimates, including one that suggests as much as 16% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sirius XM Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sirius XM Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sirius XM Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sirius XM Holdings?
If the Sirius XM Holdings story has you thinking about income, resilience, or underappreciated cash generative businesses, it can help to widen the lens and compare it with other opportunities on the market.
- If you want potential mispricings with solid fundamentals, scan through 30 high quality undervalued stocks and see which companies line up with your return and risk expectations.
- For a focus on consistent income, use 7 dividend fortresses to zero in on businesses where yield plays a central role in the investment case.
- To put capital behind sturdier balance sheets, weigh Sirius XM Holdings against companies in 30 resilient stocks with low risk scores and see how they stack up on financial resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com