


EN
Why Saipem Doubters Were Wrong Before A 107% Gain
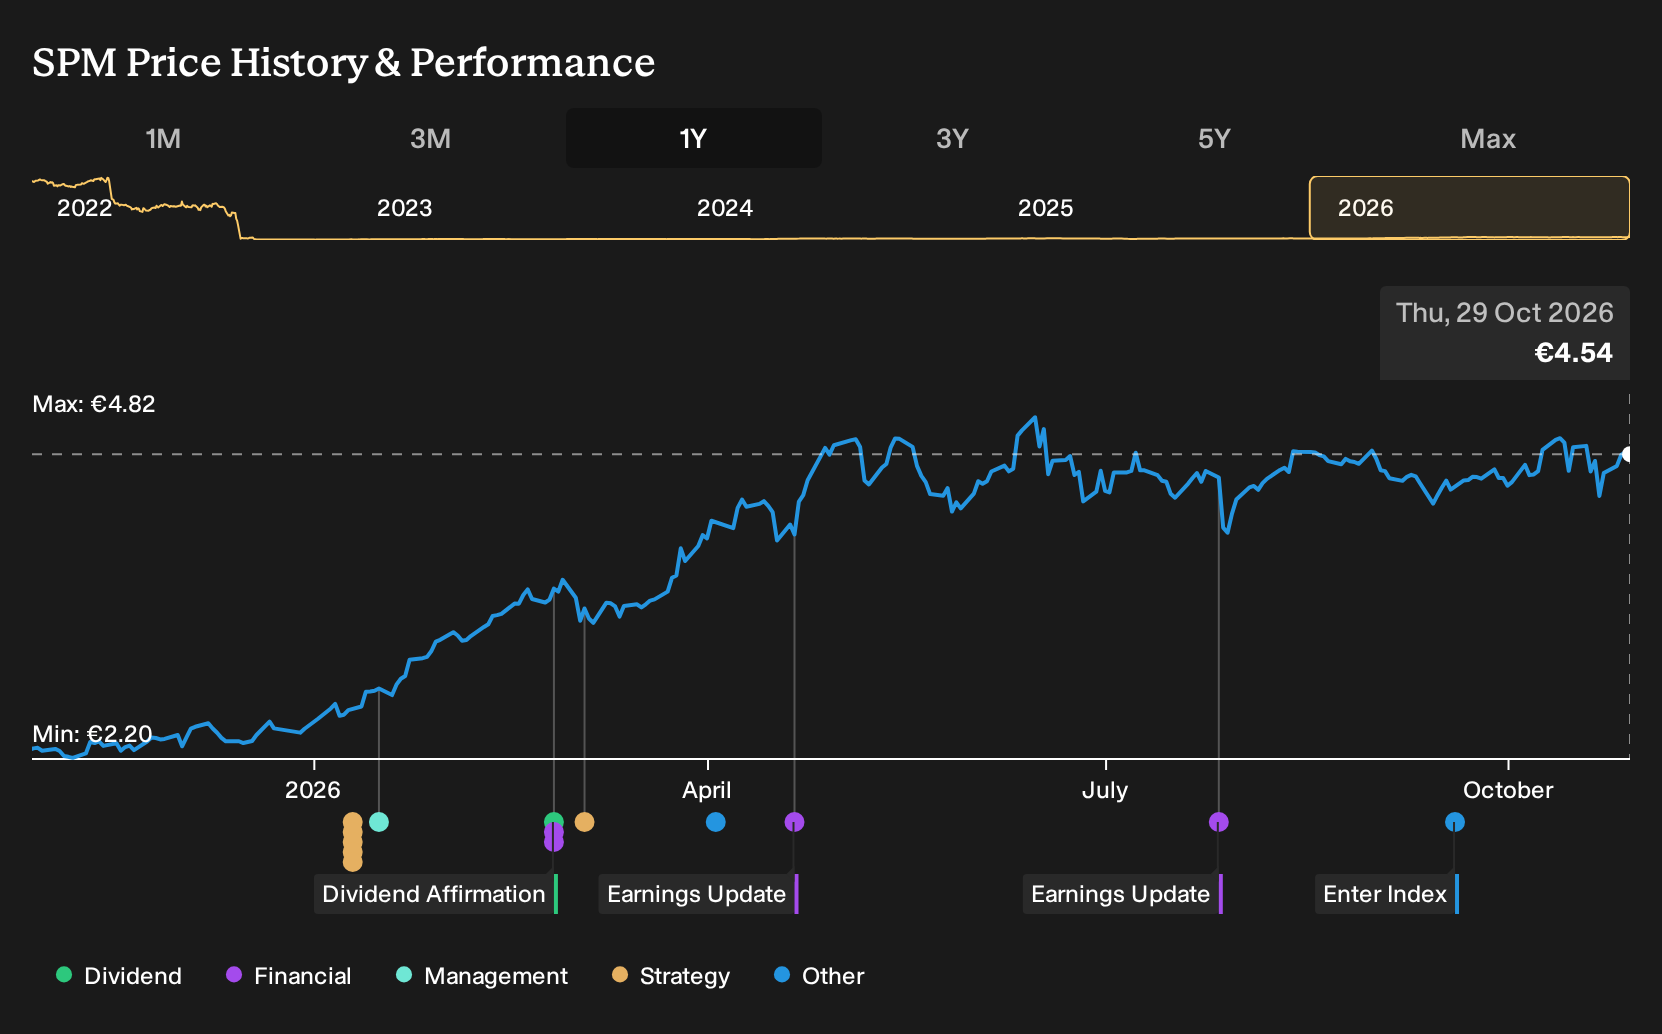
If you only glanced at Saipem’s latest accounts, the picture might look awkward. Revenue in Q2 2026 was higher than a year earlier, yet net income and margin both slipped. Holding Saipem over the past year would have returned 106.7%, including dividends. If you had seen that later payoff in advance, would the mix of LNG optimism, energy transition fears and execution risk on record in October 2025 have felt convincing enough to act?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Saipem has already moved. Pinpoint other ways to investigate the theme among 43 power grid technology and infrastructure stocks.
What Saipem Investors Were Really Debating
The shares cost €2.27 at the start of the period, and anyone looking at Saipem then had to choose between two sharply opposed stories that both sounded reasonable.
On the bullish side, the Fair Value was set at €3.54, based on the idea that LNG demand, energy infrastructure projects and Saipem’s early push into areas like CCUS and biorefining would support revenue growth and higher margins.
The bearish view put Fair Value at €2, highlighting pressure on oil and gas spending, rising ESG constraints and the risk that legacy fixed price contracts and tougher Asian competitors would keep earnings volatile.
What The Results Changed For The Saipem Debate
Saipem kept landing sizeable work, from a roughly €900m Uthmaniyah gas plant EPC award to around $1b Greater PAJ subsea infrastructure in Angola. That flow of large contracts backed the bullish idea that LNG related infrastructure, gas projects and biorefining work would feed a heavy backlog. Yet Q2 2026 told a harsher story. Revenue reached €3,826m while net income was €18m and net margin slipped to 0.5%. The outcome cut both ways.
The real lesson is simple. When an investment pitch leans on contract wins, do not stop at the headline order value. Track whether those awards later show up as higher profit and better net margin in the financial statements.
What Saipem’s 107% Run Already Prices In
Saipem now trades at €4.54, roughly double the €2.27 level from a year ago, and the selected Narrative’s Fair Value sits below that market price.
The Narrative focuses on whether project costs, offshore drilling softness and Middle East conflict expenses cap margins. Anyone buying today effectively assumes Saipem can keep high vessel utilization and margin progress intact. This raises the question of how that assumption aligns with the risk of further cost overruns and slower segment recovery.
"Although Saipem points to high utilization and a strong commercial pipeline in offshore and deepwater services, the cut to 2026 adjusted EBITDA guidance to €1.75b after extra Middle East conflict costs suggests that further unplanned cost inflation on long duration offshore projects could erode the higher margin profile that is now priced in, which would weigh on earnings quality."
One Narrative disagrees with today's price. → See where this Narrative says Saipem should trade
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 40% below our estimate - sells maritime sensing gear and connectivity hardware integrated into higher value solution bundles.
- Company 2 - 50% below our estimate - shifts mine plans toward higher grade ore bodies that reshape unit costs materially.
- Company 3 - 35% below our estimate - folds acquired engineering practices into a fee-based design network with extended program pipelines.
That is three of the list. See the full list of 195 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com