


EN
Edwards Lifesciences (EW) Could Be 6% Undervalued As FDA Approvals Lift Growth Hopes
FDA approvals put Edwards Lifesciences in focus
Edwards Lifesciences (EW) is back on investor radars after the FDA cleared its PASCAL Precision system for tricuspid valve repair and the PASCAL Ace with Capture Clarity device for degenerative mitral procedures.
The approvals landed alongside a clear upswing in Edwards Lifesciences’ market performance, with the share price at US$94.44 and a 1-month share price return of 7.22% feeding into a 10.68% year to date gain. Short term momentum looks firmer, yet the picture over longer periods is mixed. A 13.13% 1-year total shareholder return and a 3-year total shareholder return of 44.12% contrast with a 5-year total shareholder return that declined 19.54%.
Scan beyond Edwards Lifesciences and line up other potential beneficiaries of medical technology tailwinds with the hand picked 36 healthcare AI stocks.
Edwards Lifesciences now has fresh FDA approvals, growing revenue and net income, and a share price that has already reacted. Is this still a strong medical technology business offered at a reasonable tag, or has the recent move used up the easy upside?
Most Popular Narrative: 6% Undervalued
Edwards Lifesciences is trading at $94.44 against a narrative fair value of about $100.96, which frames the current move as only a partial reflection of the long term thesis rather than a full rerating.
The path to at least US$2b of TMTT revenue by 2030, supported by recent guidance of US$760 to US$780 million in 2026 TMTT sales, points to further mix shift into higher growth transcatheter therapies that could contribute to overall revenue and EPS expansion.
See why 28 investors see Edwards Lifesciences as 6% undervalued.
Result: Fair Value of $100.96 (UNDERVALUED)
Still, tariff related cost pressure and the injunction tied to the blocked JenaValve acquisition could strain Edwards Lifesciences margins and unsettle the current valuation story.
Find out about the key risks to this Edwards Lifesciences narrative.
Another View: Edwards Lifesciences Through The P/E Lens
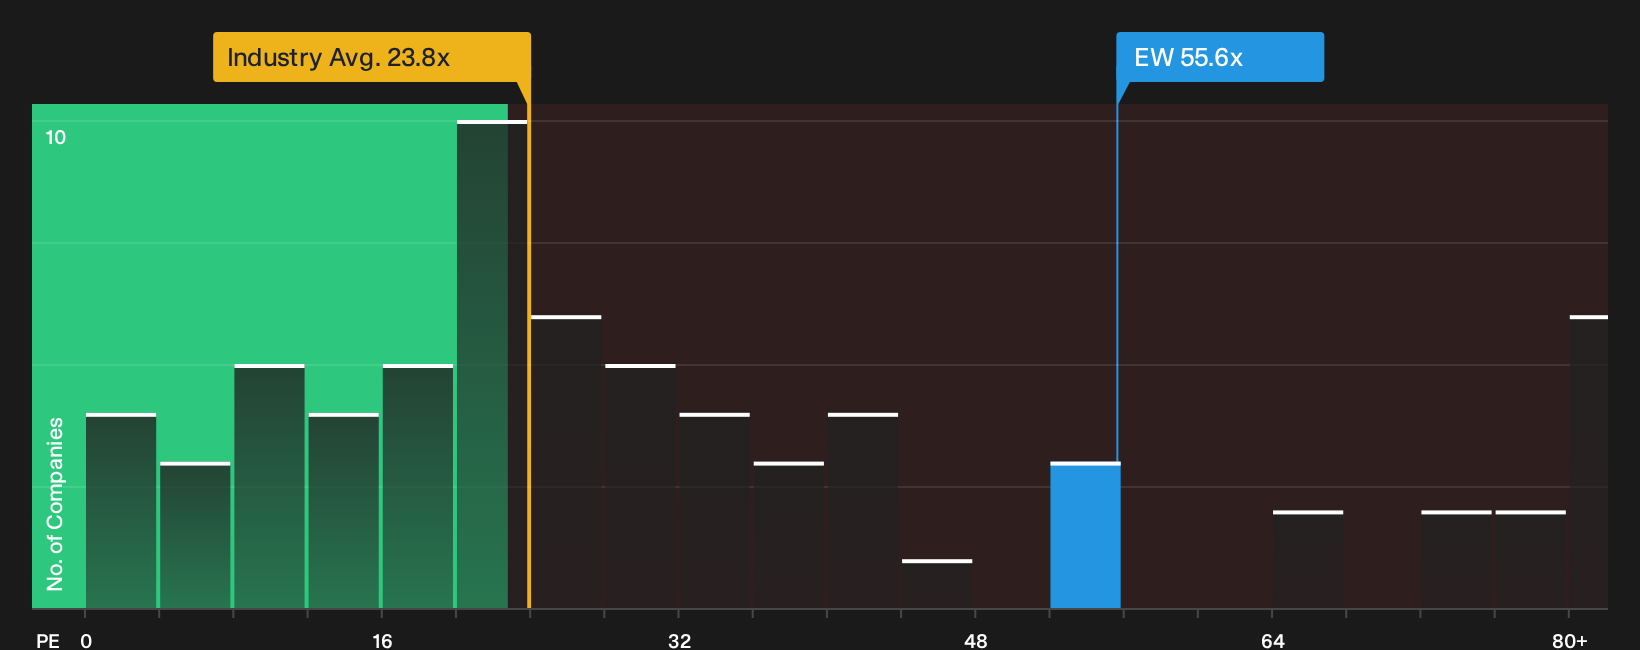
The SWS narrative fair value pegs Edwards Lifesciences at $100.96, yet the market is already paying a rich P/E of 55.6x. That is well above the estimated fair ratio of 32.6x, the US Medical Equipment industry at 27x, and peers at 28.4x, which points to meaningful valuation risk if sentiment cools.
For a closer look at how this pricing gap compares with earnings power and sector norms, check out the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Edwards Lifesciences leave you on the fence, treat that as a cue to look closer at the evidence and decide fast. To weigh both sides of the story, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Edwards Lifesciences?
You have a clear read on Edwards Lifesciences, so now is the moment to widen your opportunity set before the next wave of ideas gets crowded.
- Target resilience first and filter for companies with steadier risk profiles using the 30 resilient stocks with low risk scores.
- Hunt for pricing gaps where quality meets potential mispricing by scanning the 30 high quality undervalued stocks.
- Spot financially grounded businesses with stronger cushions against shocks through the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com