


EN
Danaher (DHR) Could Be 3% Undervalued After Strong Earnings
Danaher earnings spark fresh interest in the stock
Danaher (DHR) just reported new figures for investors. Third quarter sales reached US$6,554 million and net income came in at US$1,235 million, with higher earnings per share across both the quarterly and nine month periods.
Those numbers arrived alongside a clear shift in sentiment. Danaher’s 90 day share price return of 21.54% and 1 year total shareholder return of 11.01% point to building momentum, even though the 5 year total shareholder return is still down 10.37%.
Scan how Danaher’s earnings momentum compares with other financially resilient businesses by reviewing our curated list of solid balance sheet and fundamentals (23 results).
After that sharp 90 day jump and with Danaher now only modestly below the average analyst target and close to some intrinsic value estimates, the key issue is simple. Is most of the re rating already done, or is there still meaningful upside left as the valuation picture fills in?
Most Popular Narrative: 3% Undervalued
Danaher’s most followed narrative framework pegs fair value at $244.14 versus the latest close of $236.98, which keeps the stock framed as slightly undervalued while still pricing in a lot of execution.
The current valuation and this narrative’s view that Danaher is fairly valued and bullish suggest that the share price already reflects meaningful long-term growth in high recurring revenue segments, disciplined M&A execution, and continued cash generation.
See why 80 investors see Danaher as 3% undervalued.
Result: Fair Value of $244.14 (UNDERVALUED)
Still, that frame can crack if bioprocessing order softness lingers or if China pricing and reimbursement pressure in Diagnostics bites harder than analysts currently build in.
Find out about the key risks to this Danaher narrative.
Another View: Danaher on Earnings Multiples
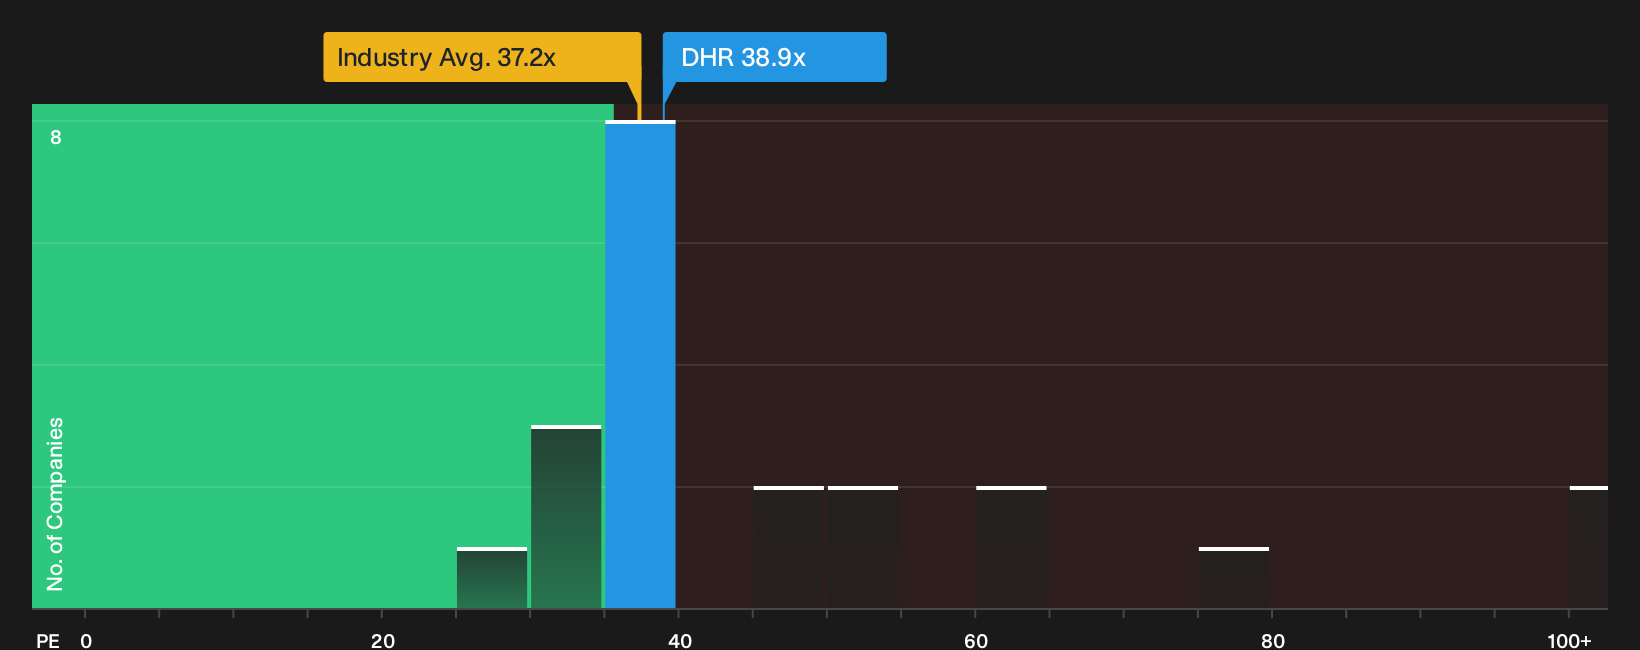
While the fair value narrative frames Danaher as modestly undervalued, the current P/E of 38.9x paints a different picture. It sits above the estimated fair ratio of 32.9x and above the Global Life Sciences average of 37.2x, which points to limited margin for error if expectations soften.
That gap suggests the market is already paying a premium for Danaher’s quality signals and recent earnings rebound, even though longer term profit trends have included years of decline. The question for investors is simple. Does that premium still feel comfortable if the next set of numbers only looks “good” rather than “great”?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece tilts cautiously optimistic, with both risks and rewards in play, so move fast, review the underlying data, and decide where you stand. To weigh those trade offs clearly, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Danaher?
If Danaher has sharpened your focus, do not stop here. Broaden your opportunity set now, or you risk missing out on stocks that fit your style.
- Target stability first by scanning a 30 resilient stocks with low risk scores that helps you focus on companies with resilient profiles when you want fewer surprises.
- Hunt for value by reviewing a 30 high quality undervalued stocks that highlights financially solid businesses trading below what their fundamentals might justify.
- Zero in on quality balance sheets using a list of solid balance sheet and fundamentals (23 results) that filters for companies combining financial strength with sound fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com