


EN
DoorDash Instacart Deal Puts Metro Stock And Grocery Peers In Focus
DoorDash’s planned US$17b move for Instacart has just redrawn the grocery delivery map, and that ripple hits far beyond apps and couriers. When one buyer controls more orders, every supermarket and wholesaler plugged into online demand feels the shift in bargaining power, customer reach and fees. This piece walks through three North American supermarket and grocery wholesaler stocks closely tied to that story, and explains why their exposure to this deal might matter to your portfolio.
The three stocks covered next are only a starter pack, and the full North American Supermarkets & Grocery Wholesalers screen surfaced 14 more listed chains and wholesalers with equally compelling stories that are not unpacked here.
If you want to move beyond headlines and quickly identify which tickers best fit your own thesis on scale, balance sheets and online exposure, head straight to the North American Supermarkets & Grocery Wholesalers screener.
Grocery Outlet Holding (GO)
Overview: Grocery Outlet Holding runs independently operated discount grocery stores across multiple U.S. states, focused on consumables, fresh food and everyday household needs.
Operations: Grocery Outlet Holding generates all of its US$4.7b revenue from U.S. grocery stores, with sales entirely sourced within the United States.
Market Cap: US$1.3b
Grocery Outlet Holding fits the screener brief as a pure discount grocer, yet its use of third party delivery platforms adds an extra angle on how digital reach can intersect with a value focused in store model.
"Re centering the model on opportunistic buying and clearer extreme value messaging, including an opportunistic sales mix that expanded by well over 300 basis points between Q1 and Q2 2026 and plans to apply the grocery playbook to deli and frozen, is expected to influence comparable sales and gross margin."
What happens to future margins and traffic will depend heavily on how one less visible shift in this playbook actually lands with shoppers.
That shopper response is exactly what the full narrative for Grocery Outlet Holding unpacks in detail, showing where Grocery Outlet Holding’s model could be accelerating or quietly stalling next.

Metro (TSX:MRU)
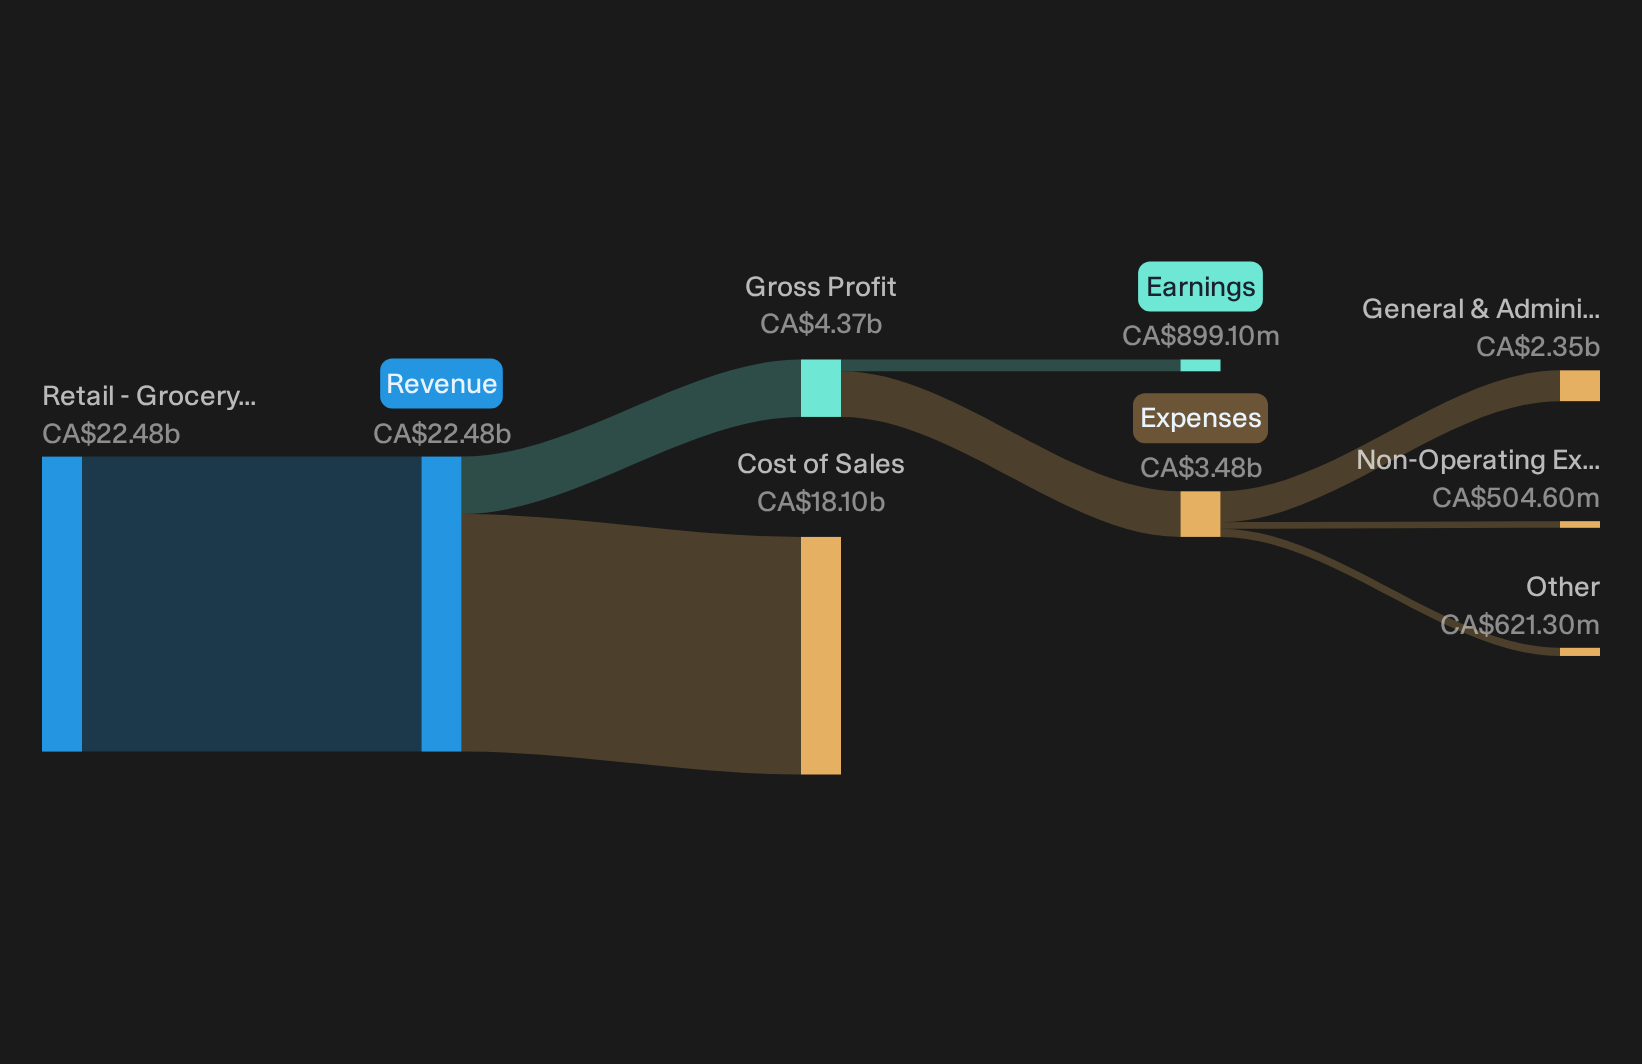
Overview: Metro is a Canadian supermarket and pharmacy group that runs banners like Metro, Super C, Food Basics and Jean Coutu with integrated online grocery and private label brands.
Operations: Metro generates CA$22.5b in revenue from grocery retail in Canada, with all sales coming from its domestic supermarket operations.
Market Cap: CA$19.9b
Metro fits this supermarkets and wholesalers screen as a large Canadian grocer where online grocery partnerships plug directly into a national food and pharmacy network.
"Ongoing investments in store modernization, new locations, and major renovations are now reinforced by network optimization that includes 10 additional Ontario conversions to Food Basics by fiscal 2027 and a wider build out of discount formats."
This raises the question of how a relatively quiet shift in where budget conscious shoppers fill their carts might influence margins and pricing power across Metro.
That shift in shopper behavior is exactly what the full narrative for Metro pulls apart, revealing where Metro’s discount tilt could be masking bigger margin and loyalty swings.
Loblaw Companies (TSX:L)
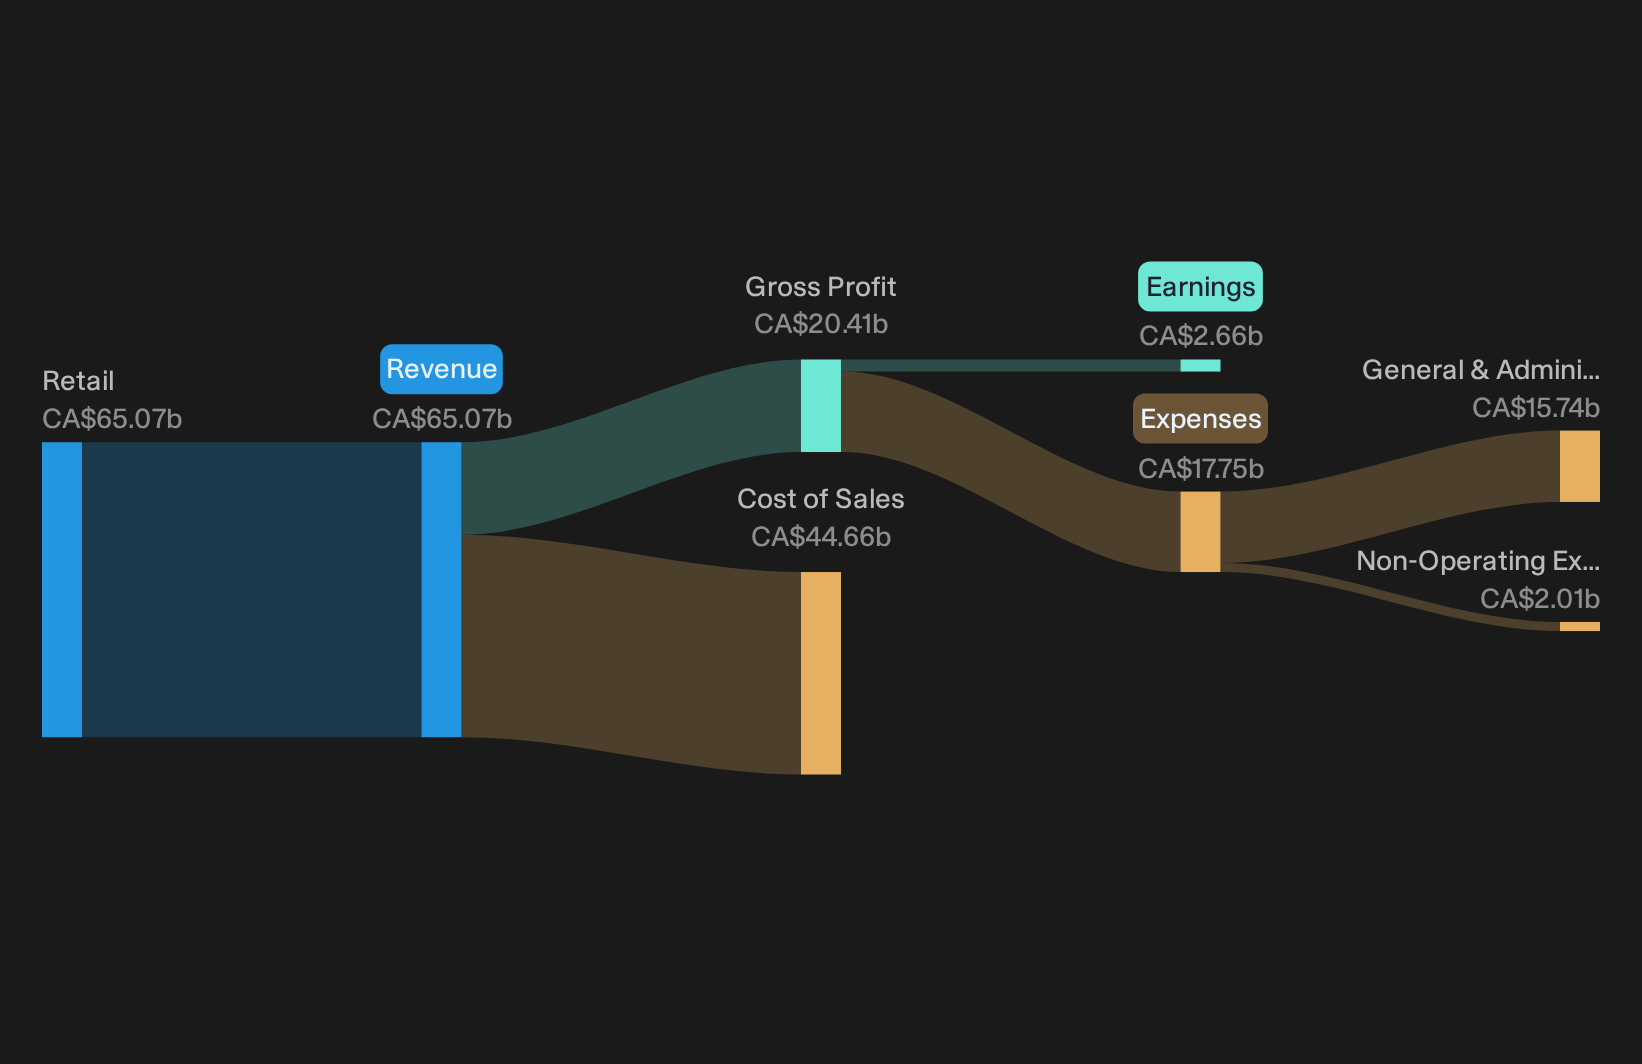
Overview: Loblaw Companies runs a nationwide network of grocery and pharmacy stores with integrated financial services and digital loyalty platforms across Canada.
Operations: Loblaw Companies generates CA$65.1b in revenue from its Retail segment, with all sales reported from customers in Canada.
Market Cap: CA$78.2b
Within this supermarkets and wholesalers group, Loblaw Companies matters because its mix of discount grocery, pharmacy and online channels is closely aligned with how Canadians shop, which is where delivery platforms and loyalty data now intersect.
"Loblaw Companies is accelerating new store openings to roughly 75 locations in 2026, with about half in food and mostly hard discount formats and half in Shoppers Drug Mart. This extends its reach into value oriented small boxes and additional pharmacy sites and supports future revenue and earnings growth as these stores mature."
What happens when one quiet shift in where those new customers spend most frequently shows up in margins and loyalty metrics will really matter.
When that spending mix starts to quietly tilt, the full narrative for Loblaw Companies shows how Loblaw Companies’ accelerating store rollout could reshape loyalty, margins and long term earnings power.
Seeking Alternatives Before Everyone Else
Fresh ideas move first. By the time momentum is flying, the easy edge is gone. Scan curated lists built for this moment while it matters and get in early.
- Spot under-the-radar quality before momentum screens catch up by running the 18 high quality undiscovered gems while these stories are still under the radar for now.
- Stack potential compounding income streams by checking the 7 dividend fortresses before yields get compressed by investors chasing the next income breakout.
- Ride real business traction instead of hype by filtering for the 38 profitable AI stocks that aren't just burning cash before the crowd wakes up to cash backed AI momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com