


EN
Does Organic Sales Growth Change The Bull Case For Symrise Stock (XTRA:SY1)?
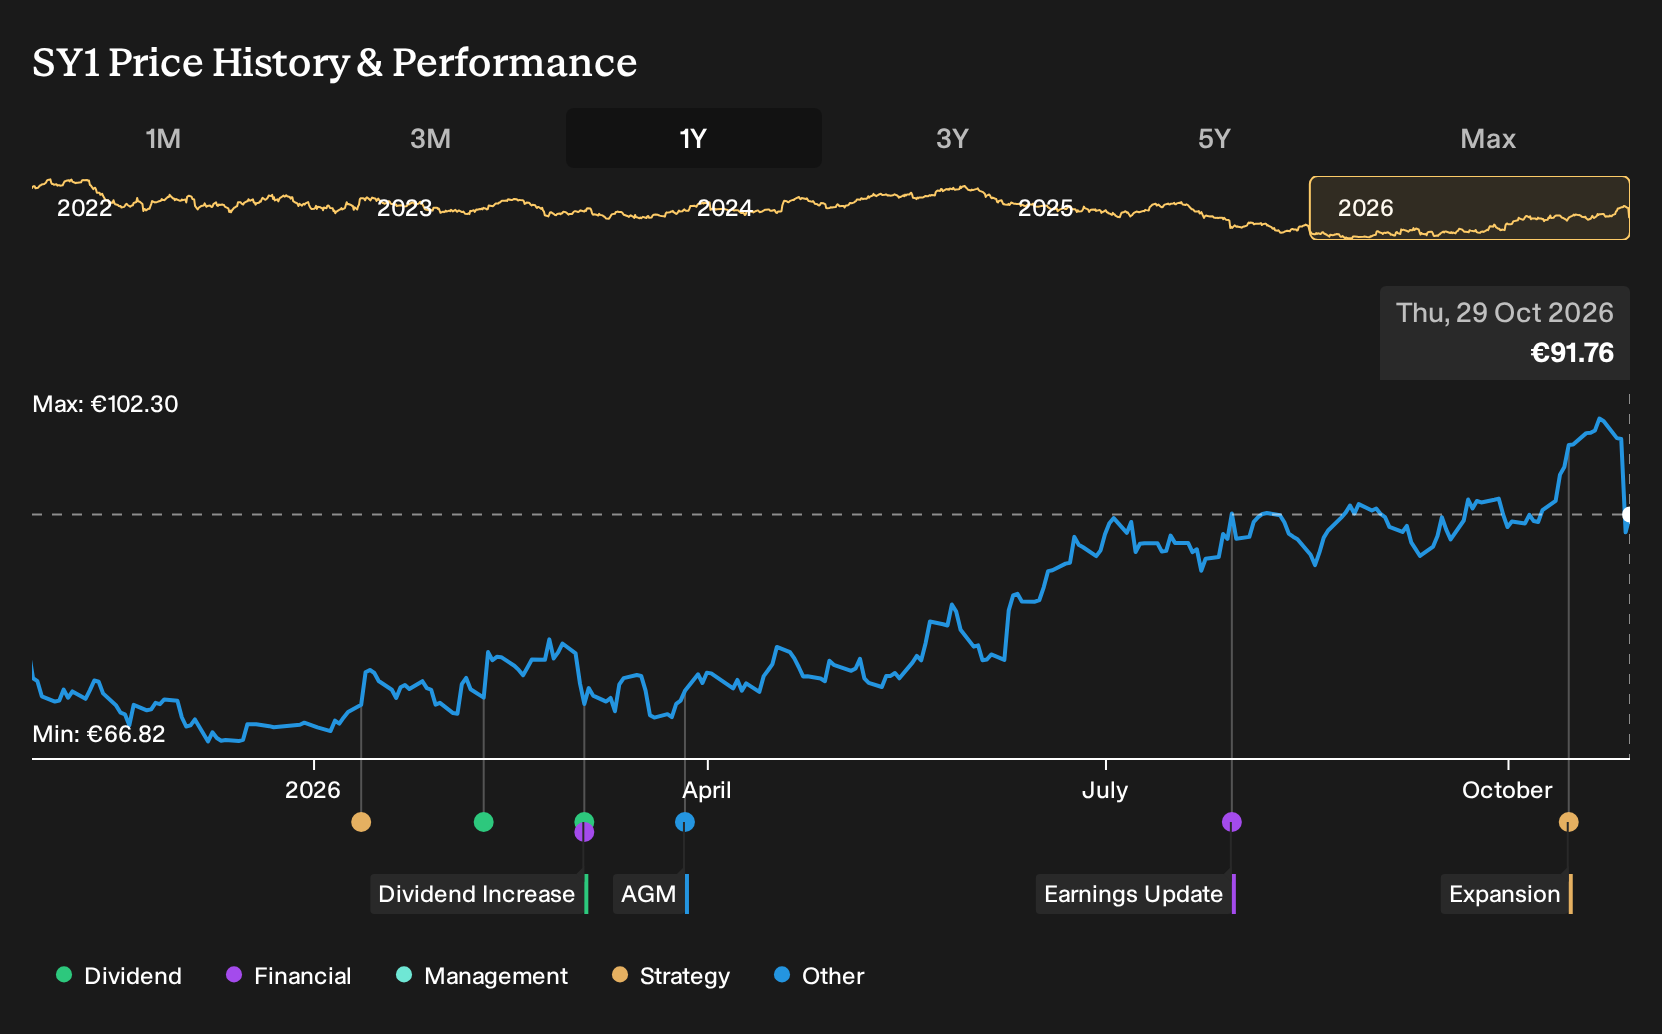
- Symrise reported 5.3% organic sales growth in Q3 2026, reaffirmed its full year outlook, and closed the Terpenes sale alongside the Floral Concept acquisition to sharpen its focus on natural fragrance capabilities.
- The combination of portfolio reshaping, capacity investments, and AI driven initiatives signals management attention on long term growth support and execution of the broader ONE SYM transformation.
- We will look at how Symrise's investment narrative evolves as recent 5.3% organic growth interacts with its ongoing portfolio reshaping.
Scan how Symrise's portfolio shift compares with other quality operators reshaping for growth by reviewing our hand picked 607 high quality undiscovered gems in similar transformation phases.
Symrise Investment Narrative Recap
To back Symrise as a shareholder, you need to be comfortable with a story built on steady top line expansion, efficiency gains from the ONE SYM program, and a shift toward higher value fragrance and care ingredients. The 5.3% organic sales growth in Q3 2026 fits that narrative but does not radically change it.
The short term swing factor remains execution on cost savings and mix improvement, while volume in slower end markets like Pet Nutrition stabilises. The biggest risk still sits in pricing pressure across menthol, UV filters and pet related categories, which could cap organic growth and weigh on EBITDA margins if input or efficiency benefits do not keep pace.
The most relevant update here is the completion of the Terpenes divestment alongside the Floral Concept acquisition. That combination tightens Symrise around natural fragrance capabilities. This sits directly in the slipstream of the ONE SYM goal to tilt the portfolio toward higher value, science based ingredients and away from more commoditised lines.
For you as an investor, the operational question is simple. Can management integrate Floral Concept cleanly, fill the new natural fragrance and musk capacity, and avoid fresh write downs like the Terpenes and Swedencare impairments, while still delivering the roughly €100m cost savings already identified? That is where the real catalyst and the real execution risk now sit.
What The Current Symrise Forecasts Assume
Symrise's narrative from analysts points to €5.7b in revenue and €657.7m in earnings by 2029. That sits on top of a 4.9% yearly revenue growth assumption and implies an earnings increase of about €411.6m from €246.1m today.
Uncover why Symrise's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One more optimistic angle on Symrise focuses on pricing stabilisation in Scent & Care as a key catalyst. The most bullish analysts were already pencilling in revenue of about €6.0b and earnings near €775.8m by 2029. You can treat those pre news forecasts as one end of the spectrum and explore how views may shift.
Explore 3 other Symrise fair value estimates, including one that suggests potential upside of up to 101% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Symrise research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Symrise. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Symrise's overall financial health at a glance.
Looking for more investment ideas beyond Symrise?
Once you have a view on Symrise, it can help to cross check that thesis against other businesses with different balance sheet strength, risk profiles, and income characteristics using the Simply Wall St Screener.
- If capital preservation sits high on your list, start with a curated set of 228 resilient stocks with low risk scores that may offer a smoother ride through market swings.
- If you want companies that pair sturdy finances with room to grow, scan our list of solid balance sheet and fundamentals (207 results) as a foundation for further research.
- If income matters more to you, use the Screener to focus on 228 dividend fortresses that combine higher yields with robust underlying businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com