


EN
Steady Toll Revenue Might Change The Case For Investing In Eiffage (ENXTPA:FGR)
- Eiffage released third quarter and nine month 2026 figures, reporting APRR and AREA revenue close to prior year levels and traffic data that showed mixed patterns across its motorway networks.
- The combination of flat revenue excluding Construction and softer traffic on APRR and AREA networks highlights that concession volumes are becoming a key operational pressure point for Eiffage.
- We will now examine how Eiffage's investment narrative relates to steady motorway revenue alongside softer APRR and AREA traffic.
Compare Eiffage's steady toll-road profile with infrastructure peers that also lean on resilient cash flows by scanning our curated list of list of solid balance sheet and fundamentals (207 results).
Eiffage Investment Narrative Recap
Eiffage appeals if you believe its mix of long duration concessions and contracted infrastructure work can keep cash generation relatively steady even when individual segments feel pressure. The latest update shows motorway revenue broadly unchanged despite softer APRR and AREA traffic, which points to tariff effects and a still resilient concession base.
The short term catalyst is whether Eiffage can keep overall group earnings supported while light vehicle traffic remains under pressure and French residential construction stays weak. On the risk side, persistent volume softness on APRR and AREA combined with high project complexity in energy and data center work could tighten headroom if execution slips.
The most relevant disclosure here is the third quarter and nine month revenue update for APRR and AREA, at €905.2m for the quarter and €2,441.6m year to date. These figures sit very close to the prior period, even as APRR and AREA traffic reached 7,450 million km in the quarter and 19,496 million km over nine months, below last year.
For you as a shareholder, that mix matters. It shows Eiffage still drawing consistent motorway income while volumes are softer, which buys time for the energy systems, German civil engineering and newer concession assets to convert the order book into profit. Any renewed traffic weakness or cost overruns on complex technical projects would likely become the key swing factors from here.
Eiffage's current analyst framework points to forecast revenue of €27.7b and projected earnings of €1.3b by 2029, based on revenue growth assumptions of 1.8% per year and consensus profit moving from €1.1b today to that 2029 level. This implies an earnings increase of about €200m from current earnings.
Uncover how Eiffage's fair value indicates a 55% potential upside to its current price, which could narrow quickly if sentiment turns.
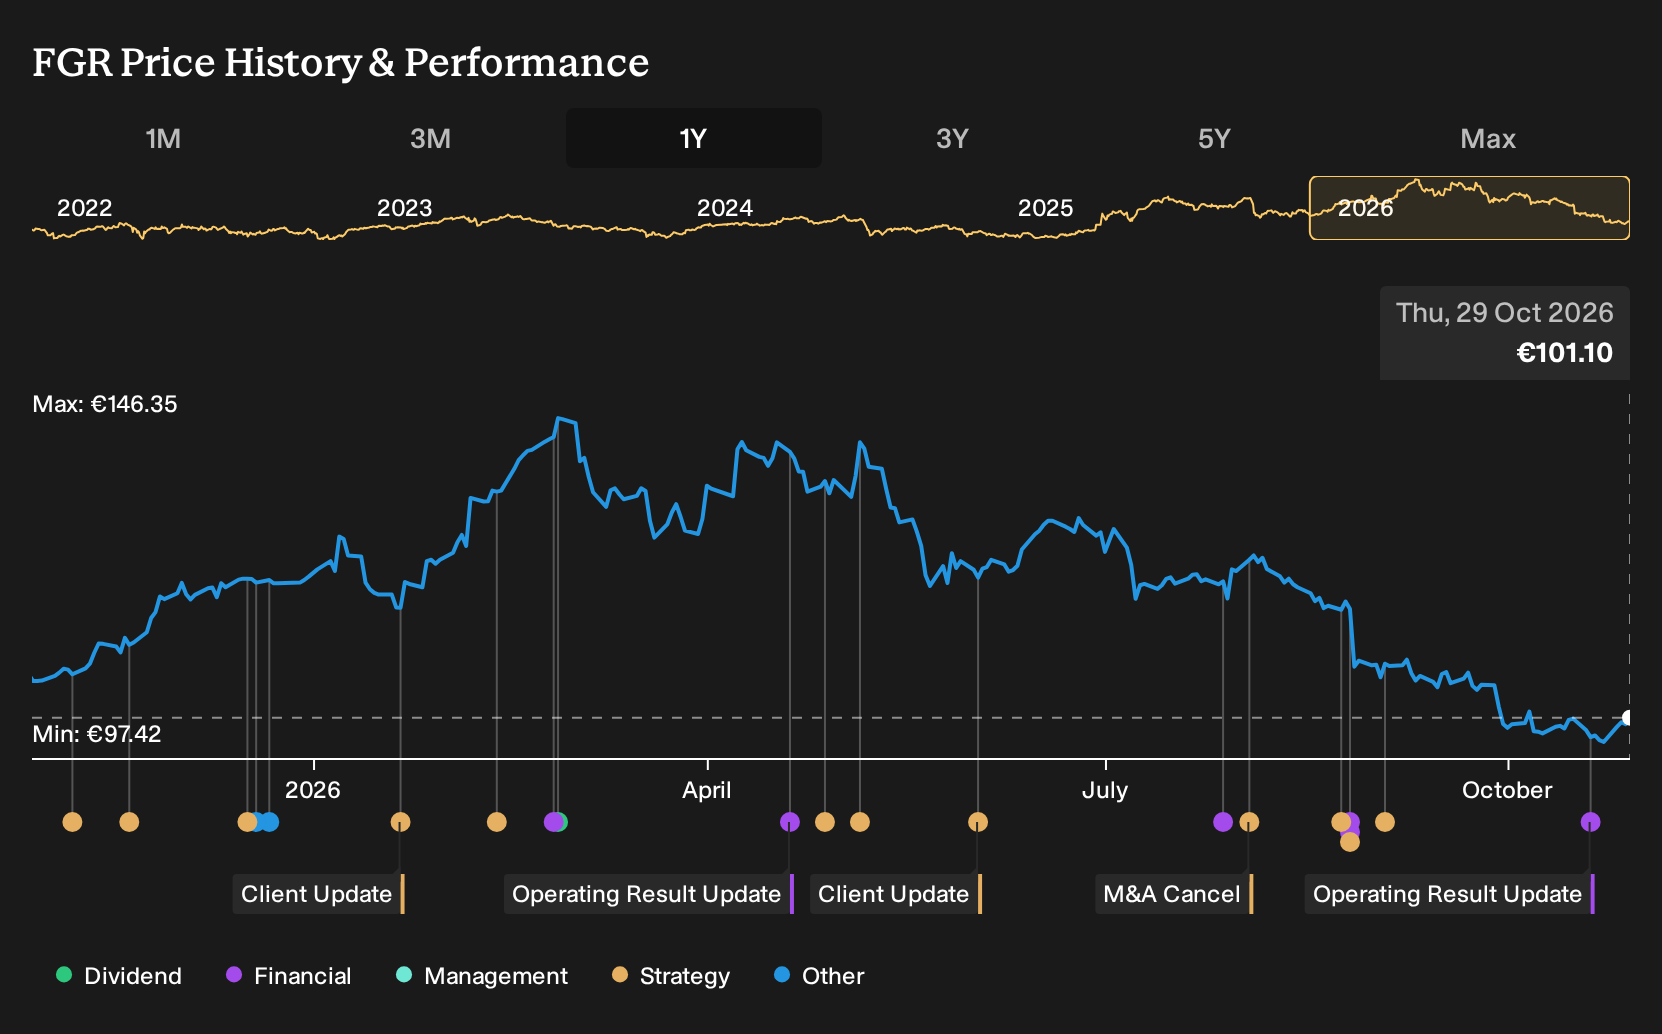
Exploring Other Perspectives
One alternate view says the real swing factor for Eiffage is not motorway volumes but how much cash its concessions can retain after heavier renewal capex and special French taxes. The most cautious analysts were only pencilling in about €26.8b of revenue and €1.2b of earnings by 2029 before this update, which is a cooler story than consensus. That gap in expectations shows how widely opinions can differ, so it makes sense for you to explore several angles as this fresh traffic and revenue news filters into future models.
Explore 4 other Eiffage fair value estimates, including one that suggests it could be worth just €129.00!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eiffage research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eiffage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eiffage's overall financial health at a glance.
Looking for more investment ideas beyond Eiffage?
If the Eiffage story has sharpened your focus on cash generation, balance sheet strength and risk, it can help to compare it with a wider set of stocks that share some of those qualities in different ways.
- If you want to zero in on smaller companies where the upside and risk can both be higher, scan a focused group of 130 elite penny stocks with strong financials that already show stronger financial metrics than most of their peers.
- If your priority is paying as little as possible for each unit of quality, broaden your watchlist with a curated set of 195 high quality undervalued stocks that combine healthier balance sheets with appealing cash flow profiles.
- If capital preservation and smoother rides matter most to you, concentrate on a hand picked pool of 228 resilient stocks with low risk scores that already score well on Simply Wall St's risk measures.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com