


EN
Flowserve (FLS) Stock Surges As Q3 Earnings Put Cash Conversion In Focus
Flowserve just dropped its Q3 2026 scorecard and the stock did not shrug. Shares jumped about 12% to US$80.35 by the close after the release, a sharp move for an industrial equipment supplier that usually trades on long project cycles, not headlines.
The emotional trigger is clear. Bookings hit roughly US$1.38b with record backlog around US$3.5b and adjusted operating margin reached 16.5%. The question now is whether this surge reflects cool judgment on a margin story gaining traction or investors chasing a single quarter of strong profitability while glossing over balance sheet and cash flow pressure.
Love Flowserve’s improving margin story but concerned about what record backlog and project timing mean for cash generation and balance sheet risk? Check out our list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$1,237.8m vs. US$1,174.4m (up about 5%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$103.0m vs. US$219.6m (down about 53%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.81 vs. US$1.69 (down about 52%)
- Adjusted Operating Margin (Q3 2026 vs. Q3 2025): 16.5% vs. roughly 14.8% (expansion of about 170 basis points)
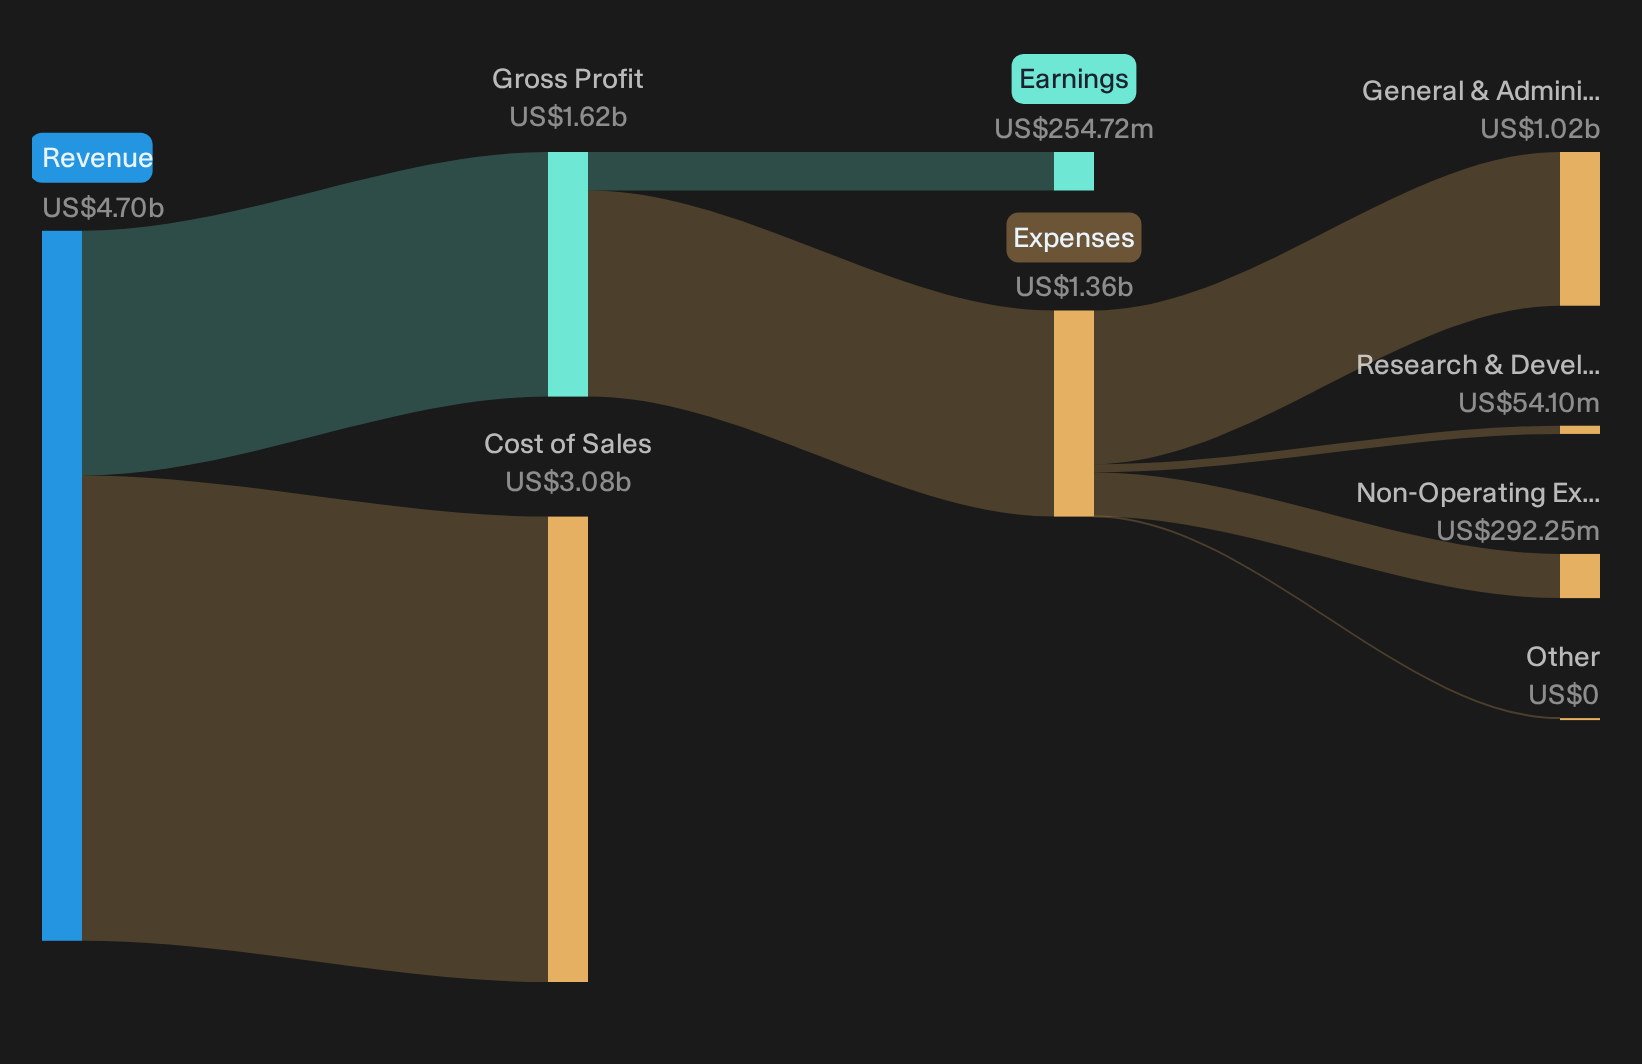
Earnings only tell part of Flowserve’s story, since the income statement can move sharply quarter to quarter while cash generation often gives a different read on how the business is really funding itself. If you focus on Flowserve’s cash flows and how they feed into a discounted cash flow model, the stock could be a notable 24% undervalued.
Flowserve’s Bull Case Hinges On Cash, Not Just Backlog
The bullish script around Flowserve rests on turning a fat order book and richer mix into reliable cash, not just higher earnings.
"The main thing that has to go right is that Flowserve continues to convert its strong bookings and high aftermarket activity into sustained free cash flow at the roughly 90% earnings conversion level while managing Middle East disruption and integration of Trillium."
Q3 hits the conversion milestone on a point in time basis. Free cash flow of US$127m was 92% of adjusted net earnings, helped by record US$728m aftermarket bookings and 16.5% adjusted operating margin. Guidance tells a tougher story. Full year free cash flow conversion is now expected around 80% because delayed Middle East shipments are tying up working capital. The bookings engine and Flowserve Business System are doing their job, yet the cash flow leg of the bull case is not consistently in the 90% zone once regional friction shows up in receivables and inventory.
The price and this Narrative do not agree. → Uncover what this Narrative says Flowserve is actually worth.
Flowserve Bear Case: Cash Friction, Not Demand Destruction
Bears argue that Middle East volatility and rebuild timing could leave Flowserve long on backlog and short on cash.
"Despite management highlighting rebuild and redundancy opportunities in the Middle East and estimating about US$50 million of related bookings into late 2026 and 2027, recent disruptions that cut year-to-date sales by about US$60 million and the downgrade that cited soft demand and regional risk suggest these projects may arrive unevenly and could fail to offset lost volume."
Q3 results lean toward timing pain rather than structural weakness. Sales took about a US$40m Middle East hit and full year organic revenue is now expected to decline, so the volume drag is visible. Yet cancellations remain minimal and free cash flow conversion sits at 92% this quarter, with full year trimmed to around 80%. The risk around uneven rebuild work is present, but so far it is delaying revenue and squeezing working capital rather than breaking demand.
Hunt For Quiet Cash Engines
Flowserve just reminded investors that a strong earnings story can move a stock fast. The real opportunity is finding stocks that could be undervalued before new information changes how they are viewed.
- Company 1 - 43% below our estimate - expands local digital payment rails that online platforms use to reach harder to serve customers.
- Company 2 - 36% below our estimate - ramps high horsepower engine capacity to support long contract commitments from data center power projects.
- Company 3 - 38% below our estimate - rolls out AI tools that screen freight carriers to reduce fraud and tighten insurance and claims exposure.
Three companies from the same screener. Open every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com