


EN
How Upcoming Earnings At Colliers International Group (TSX:CIGI) Has Changed Its Investment Story
- Colliers International Group recently appointed Jacob Snelson as data director in its business rates team, tasked with improving consistency and quality across rating datasets and supporting surveyor decision making nationwide.
- The incoming earnings report, with analyst expectations for higher revenue and earnings, comes as Colliers sharpens its data infrastructure in a core advisory unit, which could influence how investors assess the resilience of its fee based services.
- The next area of focus will be how Colliers International Group's investment narrative may shift as data capabilities expand ahead of the earnings release.
Scan how Colliers International Group's data focused shift compares with other under the radar opportunities by reviewing our hand picked list of 8 high quality undiscovered gems.
Colliers International Group Investment Narrative Recap
To own Colliers International Group, you broadly need to believe its mix of commercial real estate services, engineering and investment management can keep building fee based, recurring style income even when deal activity is choppy. The near term spotlight is on the November 4 earnings release, with the key question being how resilient fee margins look as leasing and capital markets remain sensitive to financing costs.
The biggest operational fragility is still exposure to industrial leasing and transaction cycles, alongside fundraising pressure in investment management and debt that is not well covered by operating cash flow. The Snelson hire improves internal data quality, which should support execution over time, but on its own it does not materially change those near term risks.
The recent appointment of Jacob Snelson into the business rates team plugs directly into Colliers International Group’s push on digital tools and data discipline. Better rating datasets can help surveyors price risk, structure deals and advise occupiers more consistently, which matters if transaction volumes stay uneven and every basis point of yield and fee income counts.
For you as a shareholder, the interest lies in whether this data build out feeds into the main catalysts analysts already focus on, such as efficiency gains, support for fee based services and long term return on equity forecasts. Execution still has to contend with acquisition integration challenges, softer fundraising in alternatives and exposure to commercial property cycles, so this announcement reads more as operational fine tuning than a thesis changing event.
Colliers International Group Earnings Bridge And Expectations
Colliers International Group's analyst roadmap points to revenues of $7.7b and earnings of $185.4m by 2029, built on an assumed 8.7% yearly revenue growth rate. That profile compares with earnings of $107.8m today, which implies an earnings increase of about $77.6m by the 2029 estimate year.
Uncover why Colliers International Group's fair value indicates a 59% potential upside to its current price, which could narrow quickly.
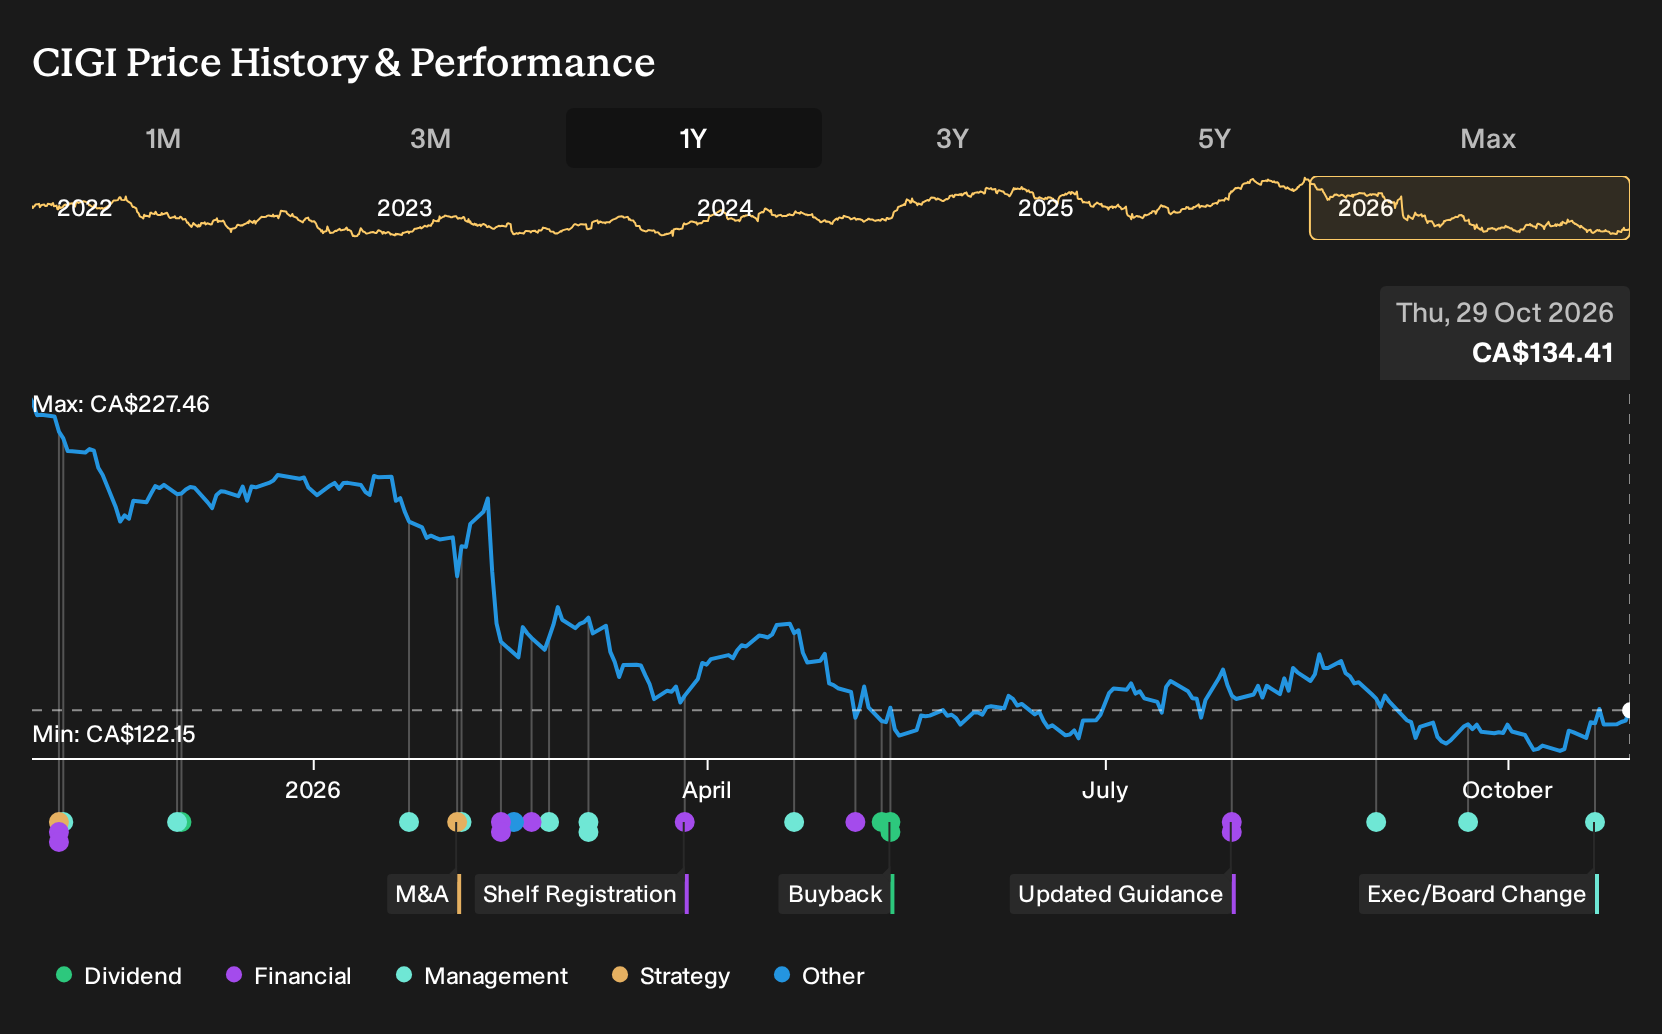
Exploring Other Perspectives
For Colliers International Group, the key swing factor in the more cautious narrative is margin pressure from competitive, cost focused outsourcing contracts. The lowest analysts were only pencilling in revenue of about $7.6b and earnings of $180.7m by 2029 before this Snelson data hire, so their view is noticeably more restrained. You can treat that as one end of a wide opinion range and decide how this new data push might shift those expectations by exploring several different analyst viewpoints.
Explore 3 other Colliers International Group fair value estimates, including one that suggests it could be worth just CA$182.97!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Colliers International Group research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Colliers International Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Colliers International Group's overall financial health at a glance.
Looking for more investment ideas beyond Colliers International Group?
Once you have a view on Colliers International Group, it helps to line it up against a wider watchlist so you can see where risk, income and value opportunities really sit by comparison.
- If you want companies that already combine quality fundamentals with attractive pricing, check out a curated set of 4 high quality undervalued stocks that may warrant a closer look.
- For investors who prefer sleeping well at night, focus on resilience by scanning a 8 resilient stocks with low risk scores that screens for businesses with sturdier profiles.
- Income focused readers can anchor their shortlist around reliable payouts by zeroing in on a hand picked group of 3 dividend fortresses that meet a 5%+ yield hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com