


EN
Agnico Eagle Mines (NYSE:AEM) Stock Falls As Q3 Results Face Cost Pressure
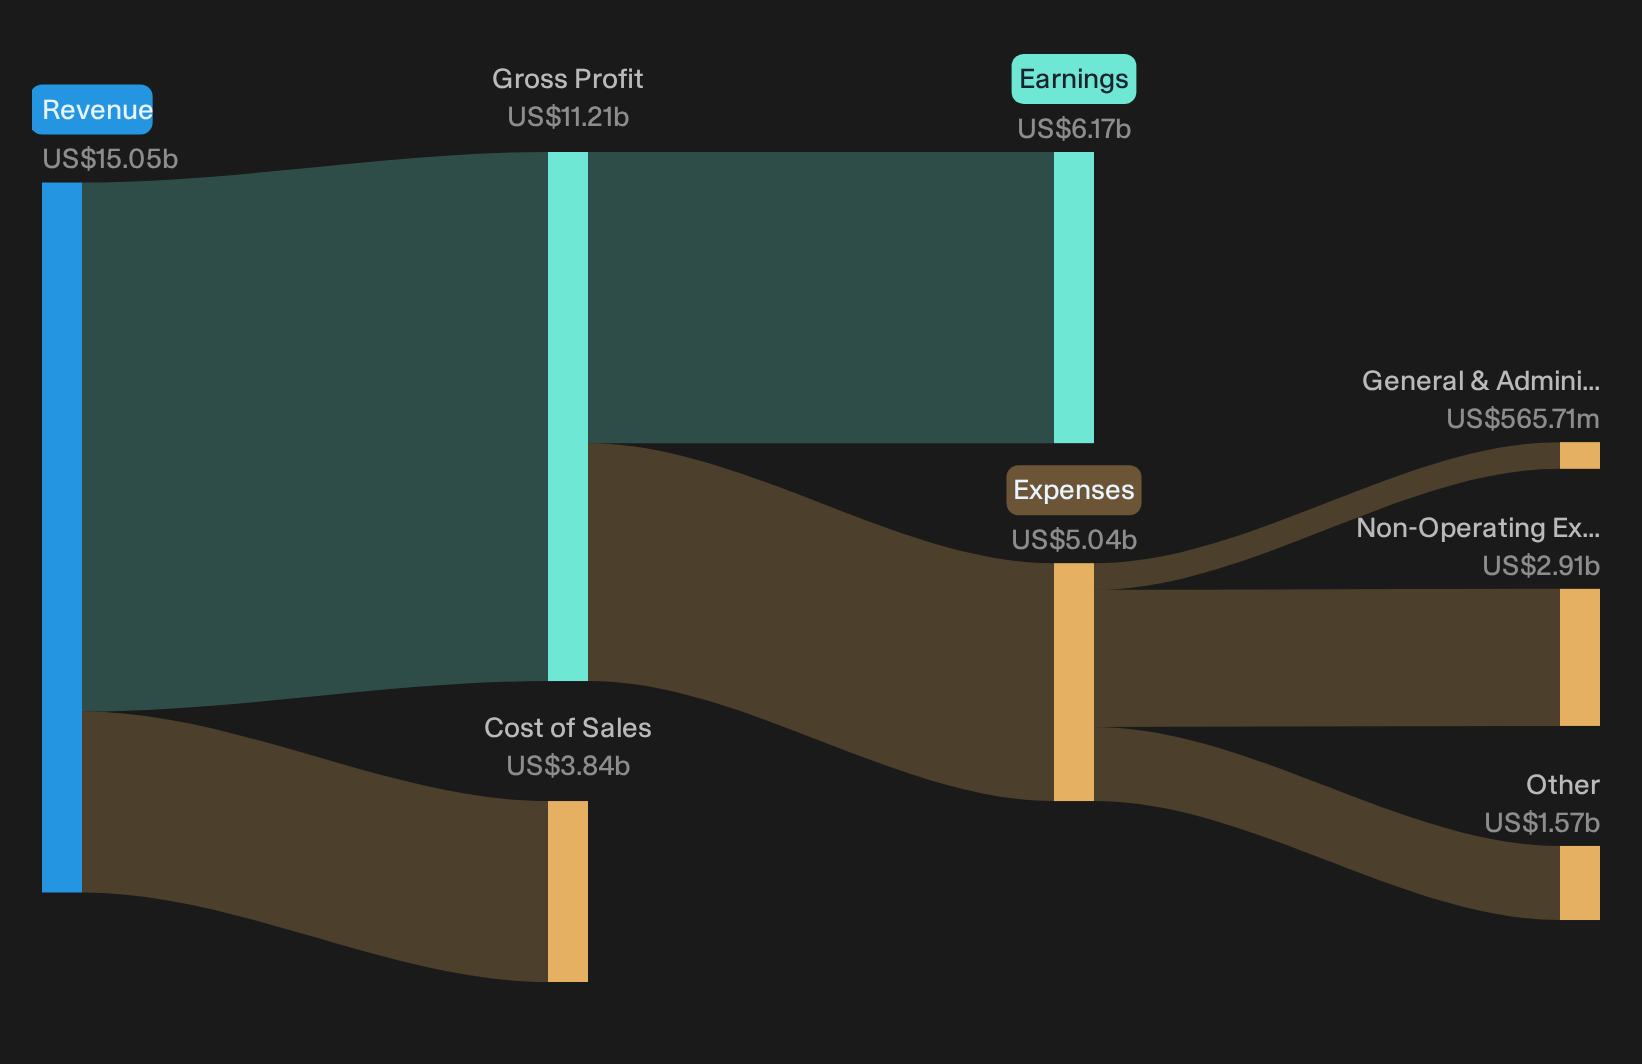
Agnico Eagle Mines just dropped Q3 2026 numbers and the stock took a hit, sliding almost 4% in today’s session from the prior close. On the surface you see a miner getting punished right after reporting quarterly earnings. Look a layer deeper and you find a gold producer that printed about US$3.6b in revenue and roughly US$1.3b in net income, while also generating solid free cash flow.
Short term traders focused on the red screen. Longer term investors are weighing a business funding multi decade growth projects off a thick cash cushion and still returning a large chunk of cash to shareholders.
Like the cash generation at Agnico Eagle Mines but want a broader set of producers with strong balance sheets and fundamentals on your radar too? Compare AEM with its peers using our screener of list of solid balance sheet and fundamentals stocks (23 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$3,583.6m vs. US$3,059.5m (up roughly 17.1%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$1,352.9m vs. US$1,055.0m (up about 28.2%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$2.67 vs. US$2.10 (up around 27.1%)
- Gold Production (Q3 2026 vs. Q3 2025): 814 koz vs. 26.96 troy ounces as reported in historical production data (the current quarter aligns with the guidance midpoint and is described as steady output)
Prefer clear visuals instead of pages of earnings tables and footnotes? View a complete chart-based overview of Agnico Eagle Mines, including its valuation profile, in the interactive company report for Agnico Eagle Mines.
Agnico Eagle Bull Case: Execution Targets Turning Into Milestones
"The key requirement for this view is disciplined execution on the five main value driver projects and the wider pipeline."
Agnico Eagle Mines is starting to back that promise with hard milestones. Malartic shaft sinking is ahead of schedule with more than 70% of construction complete and first shaft production targeted for 2027. Hope Bay moved through detailed engineering, completed a major sea lift and advanced power infrastructure. Upper Beaver and Detour underground both saw meaningful ramp and shaft progress. Heavy drilling across Malartic, Detour, Hope Bay and Finland is on track against the 1.4 million meter program, so project delivery is broadly matching the ambitious plan.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Agnico Eagle Bear Case: Costs Prove The Soft Spot
Bears worry Agnico Eagle Mines cannot turn a long project list into low cost ounces when things go wrong underground and in the pits.
"the need to increase cash cost guidance at Canadian Malartic for the second half of 2026 after the Barnat pit issues suggests that unplanned geotechnical events can quickly offset efficiency gains, which may limit how far unit cost reductions can support future net margins and earnings during periods of operational stress."
This quarter does not clear that hurdle. Group cash costs landed slightly above the guidance ceiling and full year guidance has shifted to the low end for volumes and the high end for costs. Barnat mining has restarted, so disruption is not widening, but cost pressure is real and visible in this print.
Hunt For Mispriced Earnings Power
Agnico Eagle Mines just showed how a quarter with clear positives can still leave investors debating the share price. The real opportunity sits in finding stocks that could be undervalued before the market closes that gap.
- Company 1 - 43% below our estimate - expands local payment rails so platforms can handle higher volumes and streamline cross border collections.
- Company 2 - 20% below our estimate - scales new cardiometabolic therapies while increasing manufacturing capacity and payer access to convert pipelines into prescriptions.
- Company 3 - 40% below our estimate - supplies solar tracking and control systems that project developers adopt to enhance energy yields as backlogs move into installations.
Those are three of them. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com