


EN
Should Quarterly Net Loss Require Action From Annaly Capital Management (NLY) Investors?
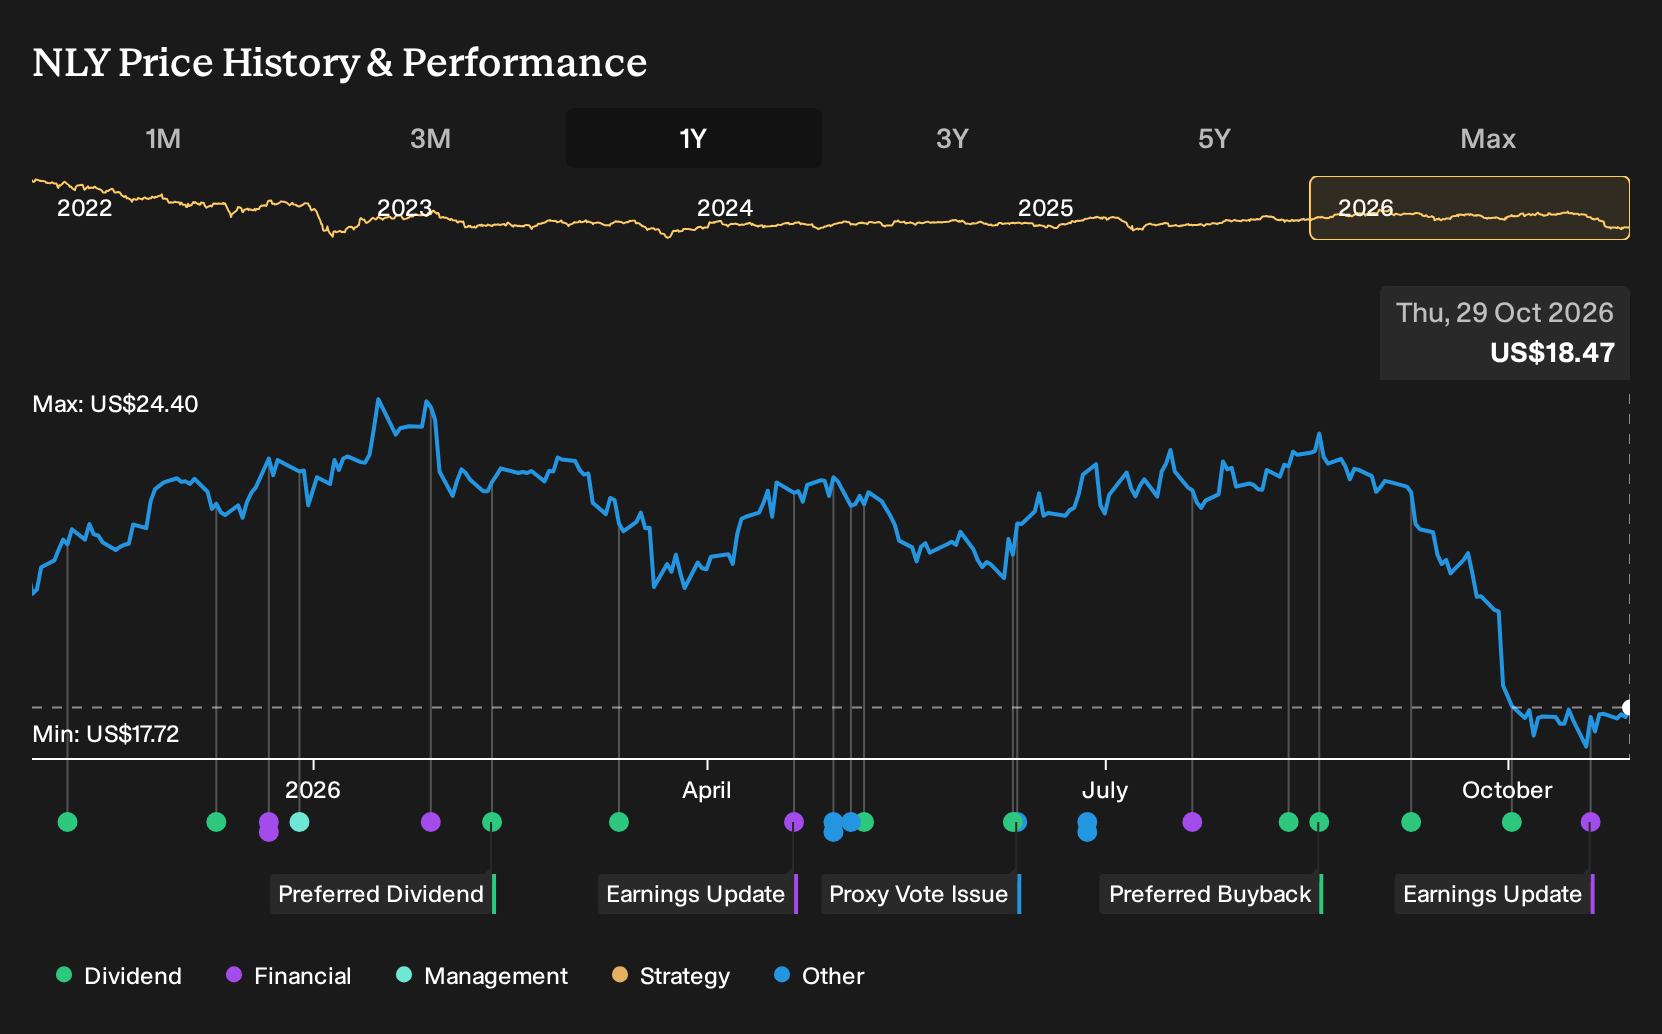
- Annaly Capital Management reported a third quarter 2026 net loss of US$1,001.76 million, with basic and diluted loss per share of US$1.36 from continuing operations, compared with earnings per share a year earlier.
- The swing from net income of US$832.45 million in the prior year period to a substantial loss reflects significant pressure on Annaly Capital Management's earnings profile and risk management decisions in its mortgage portfolio.
- We will now examine how Annaly Capital Management's investment narrative is affected by this sharp shift to a quarterly net loss.
Pressure test Annaly Capital Management's latest loss against peers and potential alternatives by scanning our hand picked 30 resilient stocks with low risk scores that prioritize resilience when earnings stumble.
Annaly Capital Management Investment Narrative Recap
To own Annaly Capital Management, you need to be comfortable with a mortgage finance model that leans on interest rate spreads, hedging and leverage. The sharp swing to a US$1,001.76 million quarterly loss puts the focus on how resilient that model is when markets move against it. In the near term, the key catalyst is whether management can stabilize portfolio returns while keeping funding costs and hedging losses contained.
The biggest immediate risk is that rate volatility, wider mortgage spreads and elevated hedging costs continue to strain earnings, especially with debt not well covered by operating cash flow and a dividend that is not well supported by earnings. If this loss is driven more by accounting and mark-to-market effects than by cash, the long-term thesis around MSR and Agency MBS positioning may be less affected, but that still needs to be tested in future quarters.
With the latest quarter showing a sizeable loss, earlier commentary about attractive Agency MBS spreads and MSR opportunities now meets a tougher reality check. Mortgage assets that looked appealing on paper can still pressure book value and distributable income if volatility stays high and funding remains reliant on higher-risk borrowing sources.
For your own assessment, it helps to connect this setback to the earlier catalyst list. The potential benefits tied to higher coupon Agency MBS, residential credit securitization and lower financing costs all depend on consistent execution and more stable rate conditions. After this result, the question becomes whether Annaly Capital Management can still convert those industry tailwinds into steadier earnings without further stressing the balance sheet or dividend coverage.
Annaly Capital Management's current analyst narrative points to revenue of US$2.7b and earnings of US$2.3b by 2029, built on an assumed 3.7% yearly revenue growth rate and an earnings uplift of US$0.4b from the US$1.9b of earnings today.
Uncover why Annaly Capital Management's fair value indicates a 30% potential upside to its current price that could close more quickly than investors expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between US$24 and about US$27.7, so you are not seeing extreme outliers yet. Those views were formed before the US$1,001.76m quarterly loss. Reassess them against ongoing rate volatility, mortgage spread risk, and shifting expectations for Annaly Capital Management's earnings power.
Explore another Annaly Capital Management fair value estimate, including one that suggests potential upside of up to 50% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Annaly Capital Management research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Annaly Capital Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Annaly Capital Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Annaly Capital Management?
If this latest Annaly Capital Management update has you rethinking risk and reward, broaden your watchlist by comparing it with other companies that score well on balance sheet strength, quality, or income potential using the Simply Wall St Screener.
- For investors who want robustness front and center, start with a list of solid balance sheet and fundamentals (23 results) and see which businesses pair healthier finances with more predictable profiles.
- If income reliability is your priority, scan a curated set of 7 dividend fortresses that focus on higher yields backed by more durable fundamentals.
- To hunt for quality that is not yet crowded, work through a hand picked 18 high quality undiscovered gems that highlights companies combining stronger fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com