


EN
Visional And 2 Japanese Undervalued Quality Stocks
Tokyo inflation has stayed above the Bank of Japan’s 2% target, yet interest rates remain very low. This keeps the reward for holding cash limited while real purchasing power is quietly eroded. That backdrop puts the spotlight on high quality Japanese businesses that generate solid cash and have sturdy balance sheets but still trade at discounted prices. This article highlights three such undervalued stocks from our quality focused screener.
The three stocks below are just a starting sample, and the full high quality undervalued screen surfaced 12 more companies with equally compelling narratives that are not covered here. To identify and analyze those potential breakout ideas for yourself, head straight into the High Quality Undervalued Stocks screener.
Visional (TSE:4194)
Overview: Visional runs BizReach and the HRMOS HR software suite in Japan, using subscription and transaction revenue for steady cash generation.
Operations: Visional earns about ¥94.1b from HR Tech and ¥5.5b from Incubation, with roughly ¥99.3b of sales generated in Japan.
Market Cap: ¥377.3b
Visional fits a high quality undervalued theme because BizReach and HRMOS generate recurring cash flow, support a strong balance sheet and sit on value scores that suggest upside despite a richer P/E than peers. The key question is how that recurring revenue behaves if one unseen pressure on client hiring appetite and HR budgets starts to bite.
If you want to see how that hiring sensitivity shows up in the numbers, check the DCF valuation analysis for Visional to see what the market might be missing.
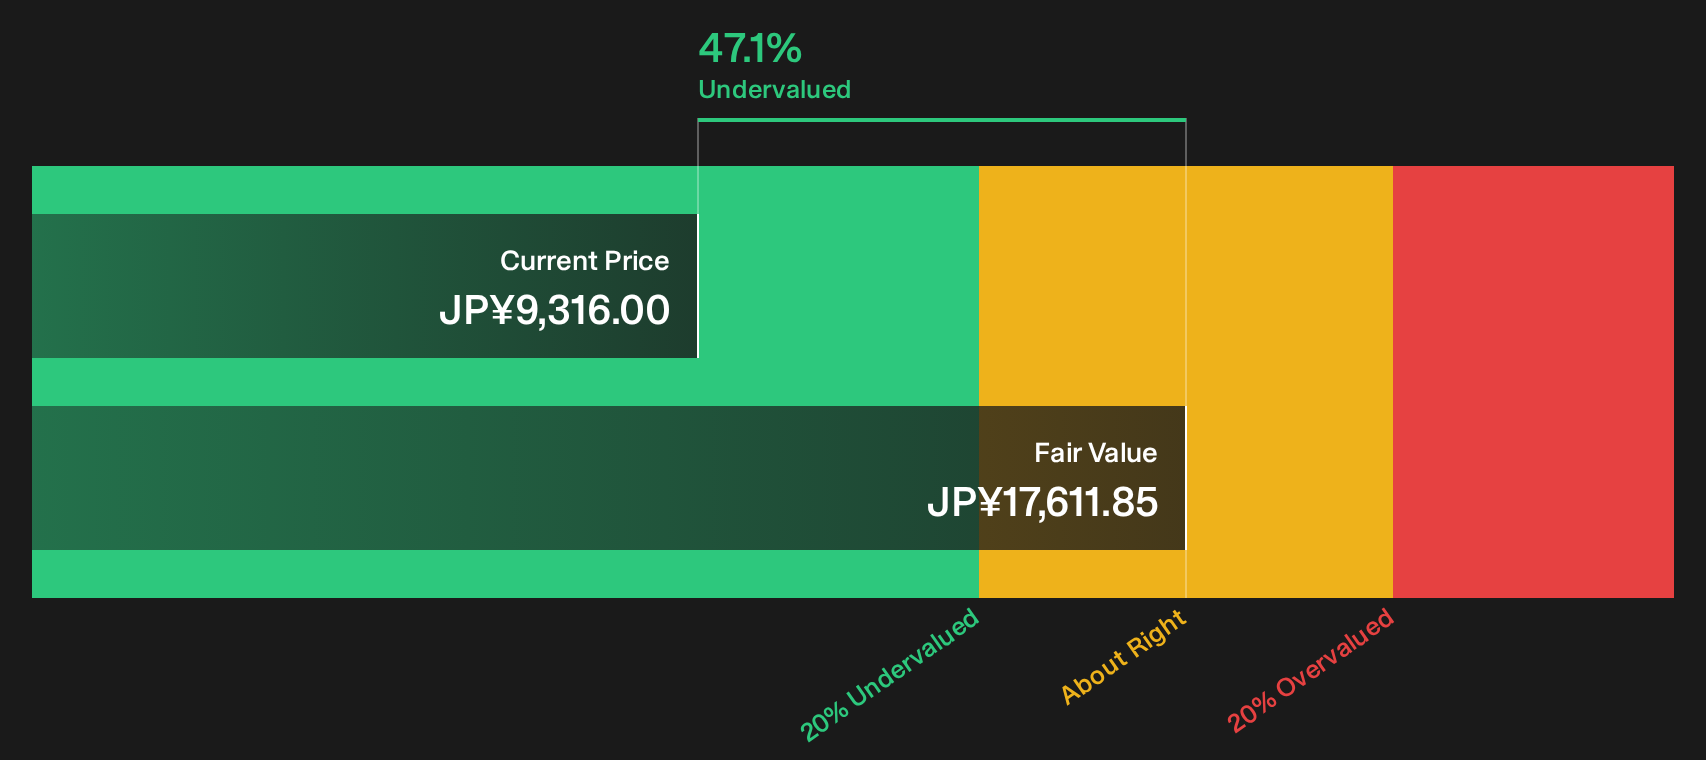
Yokohama Financial Group (TSE:7186)
Overview: Yokohama Financial Group runs a commercial and retail bank focused on deposits and loans for SMEs and individuals, generating cash flows that support its balance sheet alongside smaller securities, leasing and venture capital activities.
Operations: Yokohama Financial Group generates about ¥399.4b from banking activities, with all reported revenue coming from customers in Japan.
Market Cap: ¥1.9t
Yokohama Financial Group provides exposure to a large SME and retail lending franchise, deposit funding and a cash backed dividend profile, while trading at a discount on value scores. This combination of earnings stability and capital strength is what places it in a high quality and potentially undervalued category, depending on how one unresolved credit cycle risk develops.
That unresolved credit thread is where it gets interesting for Yokohama Financial Group, so head to the 5 key rewards and 1 important warning sign to see how the upside compares with that risk.
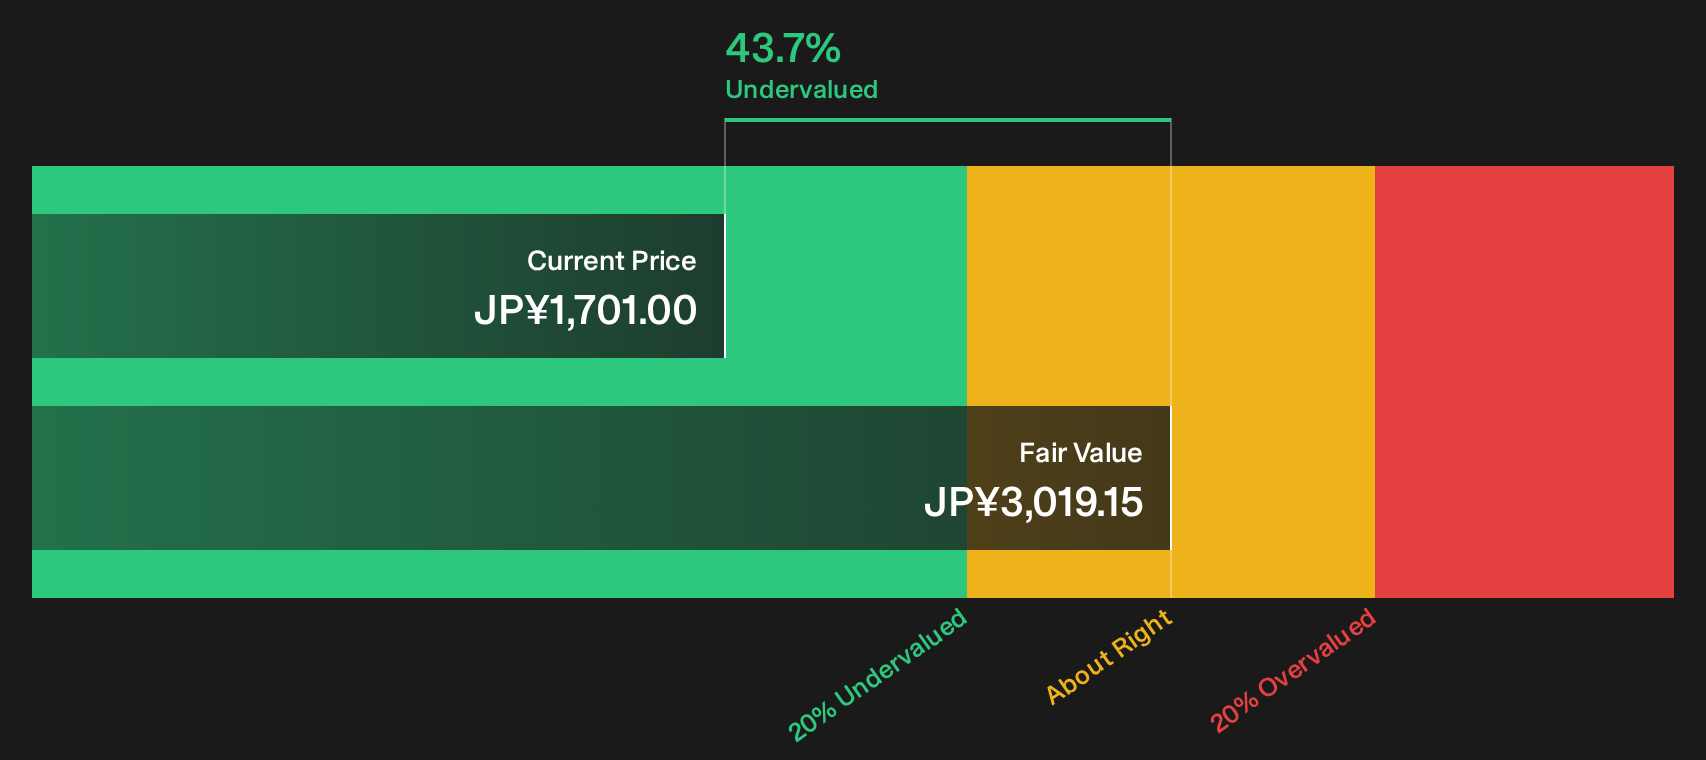
GMO Payment Gateway (TSE:3769)
Overview: GMO Payment Gateway runs payment platforms that handle online and in store transactions, generating recurring fees that underpin its high quality undervalued profile.
Operations: GMO Payment Gateway earns about ¥67.9b from Payment Processing, ¥21.7b from Money Service and ¥1.8b from Payment Enhancement activities.
Market Cap: ¥651.1b
GMO Payment Gateway ties directly into the High Quality Undervalued Stocks theme because its payment platforms convert everyday transactions into recurring cash flows, backed by a balance sheet flagged by the screen as solid. Revenue and earnings both increased in the latest nine month period. This may be relevant for valuation if a single key assumption about payment volumes and fee resilience breaks.
If that core payment volume assumption matters to you, review the analysis report for GMO Payment Gateway to see where GMO Payment Gateway’s valuation could decouple from expectations.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the best breakout ideas rarely stay under the radar for long. Scan fresh momentum, before the crowd, while it matters. Act now.
- Explore potential income strength by focusing on dependable payers using the 30 dividend fortresses before yields move lower as more investors pursue stability.
- Monitor possible infrastructure demand by tracking critical grid builders through the 43 power grid technology and infrastructure stocks while these operators are still priced as if conditions are unchanged.
- Prepare for the next automation wave by searching curated contenders within the 93 robotics and automation stocks before capital flows begin concentrating on the more established leaders.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com